Allocation: Which broad risks do you want?
Decide how much of the portfolio belongs to growth, stability and liquidity.
The wealthy-planner move is not finding a magical fund. It is giving every account and holding one clear job, then managing the risks that appear only when you look at everything together.
These decisions overlap. Pick the one creating the most uncertainty today.
Move the slider. Stocks change while bonds and cash stay flat. Nothing here predicts returns; it shows why an allocation needs a review rule.
Starting illustration: $600,000 stocks, $300,000 bonds and $100,000 cash. Taxes, fees and trading costs are omitted.
Then direct about $45,000 to bonds and $15,000 to cash in this simplified illustration.
Products come late. First define the job, the risk budget and the rules that keep the system coherent.
Name the goal, the amount, the date and how flexible each of those can be.
Diversification is about the underlying exposures, not the number of account statements or ticker symbols. The SEC specifically suggests checking fund holdings when several funds may own many of the same investments.
Asset allocation vs. diversification →Conceptual example, not a description of any specific fund. Check each fund’s current holdings and disclosures.
These are the conversations experienced planners use to connect a portfolio to the rest of a financial life.
Decide how much of the portfolio belongs to growth, stability and liquidity.
Check concentration by company, sector, geography, bond type and economic driver.
Coordinate taxable, tax-deferred and Roth space with access, taxes and portfolio job.
Use a deliberate calendar, threshold or cash-flow rule instead of a market prediction.
Growth still matters for future decades. But the next few years of spending cannot always wait for markets to recover. One portfolio must now serve two timelines at once.
These are not “more posts.” Each one answers a different portfolio question: build the mix, adapt it for retirement, coordinate larger wealth, or decide which account should hold what.
Build the broad stock, bond and cash mix around goals, time horizon and the job the money must do.
Read the guide →
See how spending needs, reliable income and sequence risk can change the allocation after paychecks stop.
Read the guide →
Add concentrated positions, liquidity, tax exposure and legacy goals to the allocation conversation.
Read the guide →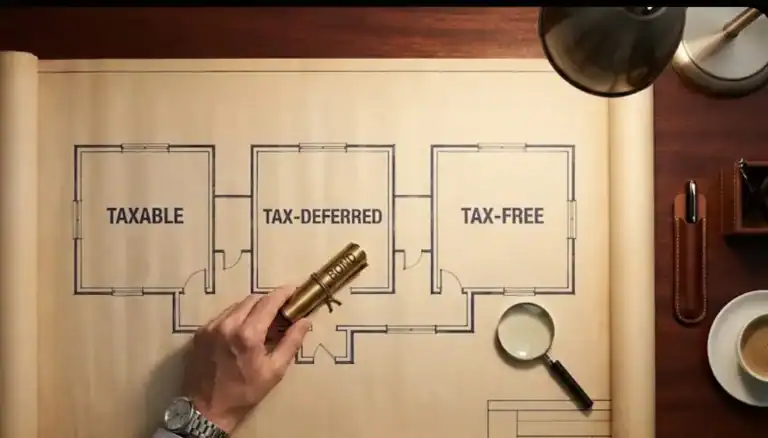
Keep the intended portfolio risk while deciding what belongs in taxable, traditional and Roth accounts.
Read the guide →Use these educational tools to organize the questions you may need to discuss with a qualified professional.
Use Ask Michael as the weird-question escape hatch.
Financial Clarity brings the same practical, planner-shaped framework to your inbox. Try it and see whether it earns a place there.
The durable decisions stay above. The category’s newest and most recently improved resources stay discoverable here.
Let’s stop guessing about your risk tolerance. After nearly 30 years in financial planning, one pattern showed up repeatedly. People often feel comfortable with risk while markets are rising, then…
Read the guide → Sep 29, 2026High Net Worth Asset Allocation: A Legacy Playbook
 Sep 29, 2026Asset Allocation Guide: Build a Portfolio That Fits Your Goals
 Sep 29, 2026Asset Allocation Models: How to Choose Beyond 60/40
 Sep 29, 2026Asset Allocation for Retirees: Stocks, Bonds & Cash
 Sep 29, 2026Modern Portfolio Theory Calculator: Maximize Returns, Minimize Risk