


When should you take Social Security: at 62, at full retirement age, or at 70? The frustrating answer is that the best age is not the same for everyone. But the decision is much easier when you stop trying to find one magic break-even age.
After nearly three decades in financial planning, I found the useful question was rarely, “Which age gives me the biggest lifetime total?” It was, “What job does Social Security need to do in this retirement plan?”
Quick Answer
If you need income now, have a meaningfully shorter life expectancy, or have a household reason to claim earlier, starting before 70 can be reasonable. If you can comfortably delay, expect a long retirement, or you are the higher earner in a couple, waiting can buy a larger inflation-adjusted monthly income floor and potentially a larger survivor benefit.
Do not let a break-even calculator make the decision by itself. First check cash flow, longevity, work status, spouse/survivor effects, and taxes.
Step 1: Understand What Changes at 62, Full Retirement Age, and 70
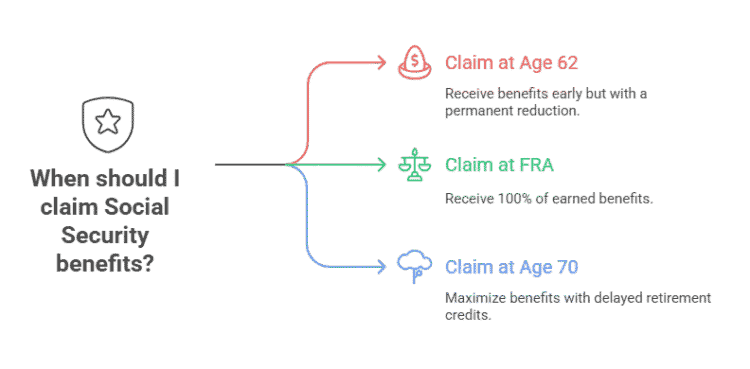
Social Security retirement benefits can generally start as early as age 62. Starting before your full retirement age permanently reduces your monthly retirement benefit. Waiting after full retirement age increases your benefit through delayed retirement credits, and those increases stop at age 70. The Social Security Administration explains the early-retirement reduction here, and its delayed-retirement-credit chart shows how waiting after full retirement age raises the benefit.
Claiming at Age 62: Earlier Cash Flow, Smaller Monthly Benefit
For someone whose full retirement age is 67, starting at 62 can reduce the retirement benefit by as much as 30% compared with the full-retirement-age amount. That does not automatically make 62 a bad choice. It means you are choosing five extra years of payments in exchange for a smaller monthly benefit for life.
Claiming at Full Retirement Age: Your Unreduced Retirement Benefit
Your full retirement age depends on your birth year. For people born in 1960 or later, it is 67. At full retirement age, the retirement earnings test no longer withholds benefits because of wages or self-employment income.
Claiming at Age 70: The Largest Monthly Retirement Benefit
For people born in 1943 or later, delayed retirement credits add 8% per year for delaying after full retirement age, measured monthly, until age 70. For someone born in 1960 or later with a full retirement age of 67, starting at 70 produces about 124% of the full-retirement-age benefit. There is no additional delayed-retirement increase for waiting past 70.
Social Security Claiming-Age Comparison Engine
Compare claiming ages using your own Social Security estimates, calculate simple crossover ages, and identify household issues that the dollar comparison alone cannot answer.
Social Security Comparison Results
Cumulative benefit comparison
| Planning age | Claim at 62 | Claim at FRA | Claim at 70 | Highest in this simple comparison |
|---|
Pairwise crossover estimates
Decision factors the math does not settle
Questions to resolve before filing
Official verification
Step 2: Start With Your Actual Social Security Estimates
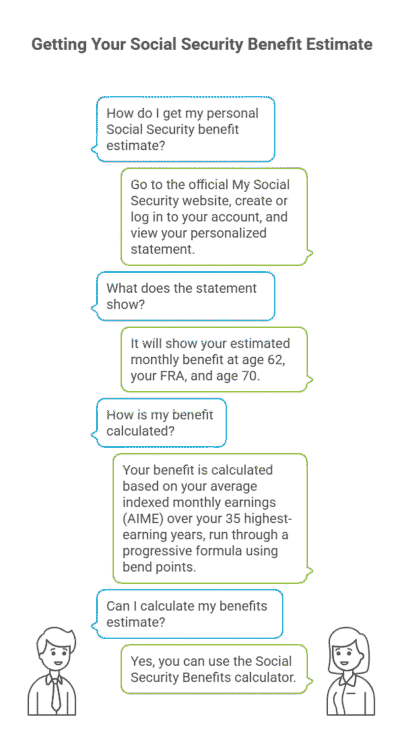
Do not compare generic percentages if you can compare your own numbers. Sign in to your my Social Security account and write down the estimated monthly retirement benefit at 62, at your full retirement age, and at 70.
- Write down the monthly benefit at age 62.
- Write down the benefit at your full retirement age.
- Write down the benefit at age 70.
- Check that your earnings record looks complete before treating the estimate as your planning number.
Your benefit calculation is based on your earnings history, including your highest 35 years of indexed earnings. If you have fewer than 35 years of covered earnings, zeros can be included in the calculation. Continuing to work can also replace a lower-earning year with a higher one.
Step 3: Use Break-Even Age as a Check, Not the Verdict

A break-even calculation asks a narrow question: How long would I have to live before the larger checks from delaying make up for the checks I skipped? That is useful. It is also incomplete.
Michael’s Take
I would never let one break-even age make this decision for a client. Break-even math usually treats Social Security like an investment account. It is also lifetime income insurance. For a married couple, the higher earner’s claiming decision can affect the income that survives after the first spouse dies.
The spreadsheet can tell you when two payment streams cross. It cannot tell you which risk you most need Social Security to insure.
This is exactly where real-world decisions split. Some people value getting money earlier while they are healthier and more active. Others value the larger guaranteed income later in life, especially when one spouse may outlive the other by many years. Both can be rational. The mistake is pretending they are answering the same question.
Step 4: Run the Five Questions That Actually Change the Claiming Decision
1. Do You Need the Income Now?
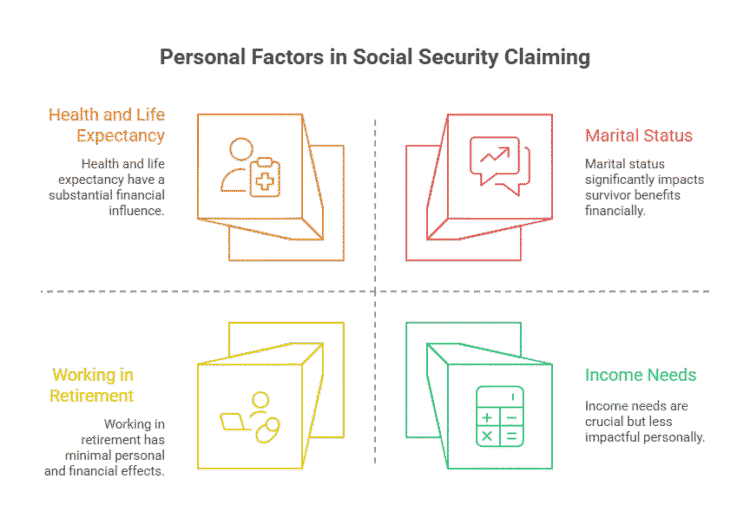
If Social Security is needed to cover housing, food, insurance, or other essential expenses, claiming earlier may be reasonable even if delaying would produce a larger monthly check. A retirement plan that requires you to burn through cash or take investment risk you cannot tolerate just to “win” a break-even calculation is not automatically a better plan.
2. What Are You Insuring Against: Dying Early or Living a Very Long Time?
Health and family longevity matter, but avoid turning them into false certainty. None of us gets our personal expiration date in advance. If your health is poor or longevity is clearly less likely, earlier claiming can become more attractive. If you are healthy and worried about living into your late 80s or 90s, a larger inflation-adjusted monthly benefit later can become more valuable.
3. Will You Keep Working Before Full Retirement Age?
This is one of the easiest factors to miss. If you claim before full retirement age and keep working, the retirement earnings test can cause Social Security to withhold some benefits when earnings exceed the annual limit.
For 2026, if you are under full retirement age for the entire year, SSA says the earnings limit is $24,480, with $1 in benefits withheld for every $2 earned above the limit. In the year you reach full retirement age, the 2026 limit is $65,160 for earnings before the month you reach full retirement age, with $1 withheld for every $3 above the limit. Beginning with the month you reach full retirement age, there is no earnings-test limit. SSA later recalculates your retirement benefit to give credit for months benefits were withheld because of excess earnings. See SSA’s 2026 working-while-receiving-benefits rules.
4. Are You the Higher Earner in a Married Couple?
Couples should not analyze two claiming decisions independently. A spouse’s maximum spousal benefit is generally based on up to 50% of the worker’s full-retirement-age benefit, not the worker’s delayed amount. But delayed retirement credits can increase the benefit used to determine a surviving spouse’s benefit. That makes the higher earner’s delay decision especially important when one spouse is likely to depend on the larger benefit after the first death. SSA explains the spouse-versus-survivor distinction here.
5. What Else Happens to Your Taxes and Retirement Income if You Claim Now?
Social Security does not arrive in a vacuum. Claiming can change taxable income, how much you need to withdraw from investments, and the room available for other retirement-income moves. Up to 85% of Social Security benefits can be included in taxable income depending on your other income and filing status.
If taxes or Medicare premiums are the main reason you are considering one claiming age over another, use the dedicated Social Security timing and IRMAA guide. This page owns the claiming decision itself; that page owns the deeper tax-and-Medicare interaction.
Step 5: Make the Decision With a Simple Claiming Framework
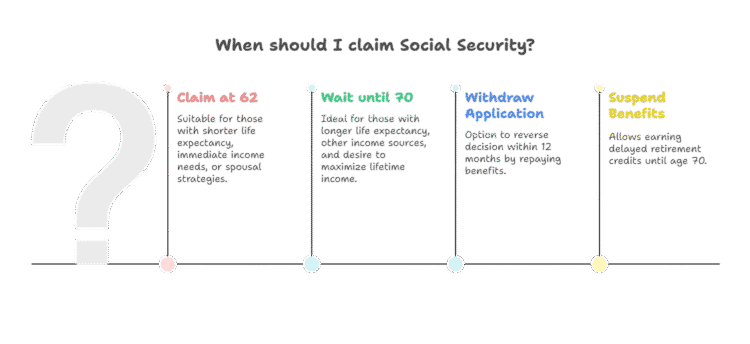
Claim Earlier May Fit Better If:
- You need the income for essential spending.
- Your health or longevity outlook meaningfully favors receiving benefits sooner.
- You are no longer working enough for the earnings test to materially withhold benefits, or you have modeled that effect.
- Your household strategy supports the lower earner claiming earlier while protecting the higher earner’s larger future benefit.
Waiting Longer May Fit Better If:
- You can comfortably fund retirement without Social Security for now.
- You are healthy and want more protection against a very long retirement.
- You are the higher earner and maximizing the potential survivor benefit matters.
- You are still working before full retirement age and the earnings test would otherwise withhold a meaningful portion of benefits.
The Decision Rule I Would Use
Claim Social Security when the benefit does the most useful job for your household—not merely when a spreadsheet says you have “broken even.”
If the money solves a real cash-flow problem now, that matters. If delaying materially strengthens the survivor’s income floor or protects against living into your 90s, that matters too.
What If You Claim and Change Your Mind?
There are two different rules people often lump together:
- Withdraw the application: If it has been less than 12 months since you were first entitled to retirement benefits, you may be able to withdraw the claim. SSA requires repayment of benefits received, including affected family benefits and certain amounts withheld. A retirement-benefit withdrawal after entitlement is generally limited to once in a lifetime. SSA explains the withdrawal process here.
- Voluntarily suspend benefits: Once you reach full retirement age and before age 70, you can request that retirement benefits be suspended. Delayed retirement credits can then increase the benefit for months of suspension, subject to SSA’s rules for people receiving benefits on your record. See SSA’s suspension rules.
Final Verdict: The Best Social Security Age Is the One That Protects the Right Risk
There is no universal best age to claim Social Security. Age 62 buys earlier cash flow. Full retirement age removes the retirement earnings test and provides the unreduced retirement benefit. Age 70 buys the largest monthly retirement benefit available from delaying.
The better decision comes from knowing which risk matters most in your plan: running short of cash now, dying earlier than expected, living much longer than expected, reducing a surviving spouse’s income, or creating unnecessary friction with work and taxes.
That is why I would use break-even age as a dashboard light, not the steering wheel.
Sources
- Social Security Administration — Starting Your Retirement Benefits Early
- Social Security Administration — Delayed Retirement Credits
- Social Security Administration — Receiving Benefits While Working
- Social Security Administration — Spouse’s and Survivor Benefits
- Social Security Administration — Cancel or Withdraw Your Benefits Application
- Social Security Administration — Suspending Retirement Benefit Payments
