Rebuild, replace and keep the household functioning.
A typical homeowners policy can combine dwelling, personal-property and additional-living-expense coverage, subject to limits, deductibles and policy terms.
Home and auto insurance are not just about replacing things. The bigger job is keeping one fire, crash, lawsuit or uncovered peril from reaching the rest of your financial plan.
The right question is not “Do I have insurance?” It is “What could still reach me after the policy responds?”
These paths overlap. A single event can create property damage, temporary living costs and liability at the same time.
Choose a loss to see the coverage stack. The examples are intentionally simplified so the policy job is easy to see; the contract, exclusions, limits and state rules control the actual claim.
A typical homeowners policy can combine dwelling, personal-property and additional-living-expense coverage, subject to limits, deductibles and policy terms.
Flood insurance is a separate protection layer. FEMA says flood risk exists outside high-risk zones too, so lender requirements are not the same thing as your actual exposure.
Verify with the National Flood Insurance Program ↗Home and auto liability normally respond first. A personal umbrella policy can add liability and defense protection above qualifying underlying policies for covered claims.
NAIC: What’s an umbrella policy? ↗Liability addresses injury or property damage you cause. Collision addresses physical damage to your own vehicle from a collision, while comprehensive generally addresses many non-collision losses.
Read the full car insurance guide →Insurance is solving for the cost of the covered loss, not what Zillow, a buyer or the land says the property is worth.
Includes land, location and market demand.
The cost to repair or rebuild the covered structure with comparable materials, subject to the policy.
Replacement-cost coverage generally pays based on repair or replacement with like kind and quality, subject to the policy and limits.
Actual cash value generally reflects age and wear, which can leave a larger out-of-pocket gap after a loss.
A higher deductible may reduce premium, but it increases the amount of a covered property claim the household retains.
Photos, receipts, serial numbers and a home inventory can make a property claim easier to support after a major loss.
A replaceable vehicle is one exposure. Injury, lost income and property damage to someone else can be much larger.

Use this to separate liability, uninsured motorists, collision and comprehensive instead of treating “car insurance” as one number.
Read the car insurance guide →As assets and future income grow, the liability limit deserves a separate review from the replacement value of the property.
Use the walkthrough as an organizing sequence, not as a substitute for your policy’s claim instructions or state-specific deadlines.
Handle emergencies first. Take reasonable steps to prevent additional damage when it is safe to do so, and keep receipts for temporary protective work.

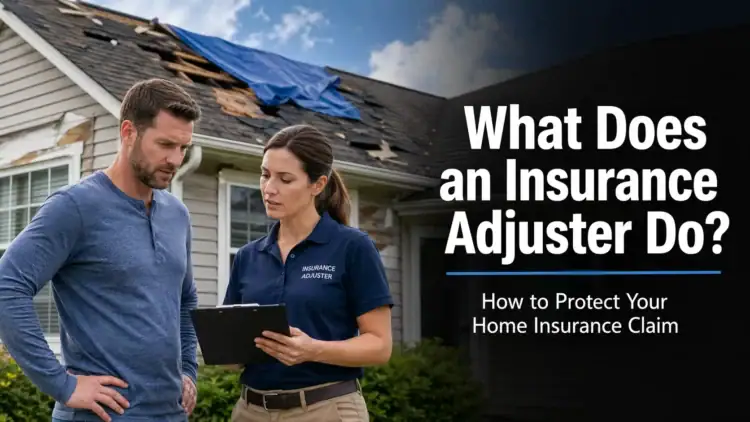
Understand what the adjuster does, how the claim is valued and where documentation changes the conversation.
Read the guide →
Use this after the initial claim when scope, depreciation, documentation or settlement language becomes the real issue.
Read the guide →These are policy-review questions, not assumptions about your coverage.
Most homeowners and renters policies do not cover flood damage. A separate flood policy may be needed.
NFIP flood guidance ↗Market value and rebuild cost are different numbers. Confirm what the dwelling limit is designed to replace.
NAIC homeowners guidance ↗Actual cash value can shift more replacement cost back to the household than replacement-cost coverage.
NAIC ACV vs. RCV ↗The property may be fully insured while a large covered liability claim still exceeds the primary policy limit.
NAIC umbrella guidance ↗Imported and gray-market cars can create underwriting, valuation and parts-availability questions that ordinary auto coverage does not surface.

A niche example of the bigger lesson: when the asset is unusual, verify that the policy valuation and underwriting assumptions are unusual enough too.
Read the import-car guide →Financial Clarity connects insurance, cash reserves, retirement income, taxes and the balance-sheet decisions that determine how much risk you can safely keep.
This is a small library today, so the flagship hub does more of the teaching itself instead of pretending four articles are a deep archive.