Risk tolerance is your willingness to accept investment losses and uncertainty in pursuit of a financial goal. But willingness is only part of the decision. Before choosing how much risk to take, you also need to consider your risk capacity—whether your finances can absorb a decline—and your risk composure—how you are likely to behave when one happens.
I’ve spent nearly 30 years in financial-planning conversations. One pattern comes up repeatedly: people can be perfectly comfortable with their portfolio in theory and discover a very different reaction when real money is at stake. The answer isn’t to ignore their discomfort or tell everyone to buy the same mix of stocks and bonds. It’s to build a plan around all three dimensions before the next bad market.
Start with the practical question: If your investments fell tomorrow, would the damage threaten something you need to pay for, or would it mainly test your nerves? Those are different problems. They deserve different solutions.
Show the 30-second version
- Tolerance: Willingness to accept investment uncertainty; the SEC also uses a broader ability-and-willingness definition.
- Capacity: Whether market losses would threaten withdrawals, obligations or the timing of important goals.
- Composure: How your actual behavior and decision rules stand up when markets decline.
- Next decision: Reconcile willingness, capacity and behavior before selecting an asset allocation.
On This Page
- What risk tolerance means—and what it doesn’t
- The three dimensions: willingness, capacity, and composure
- How to assess your risk before choosing investments
- Try the MRM 3-D Risk Profile Analyzer
- How your risk profile should affect your portfolio
- When should you reassess risk tolerance?
- Three questions to answer before your next portfolio decision
- How We Verified This
What risk tolerance means—and what it doesn’t
An investment with higher expected long-term returns may also expose you to larger, longer or less predictable losses. Risk tolerance describes how willing you are to accept that uncertainty. The SEC’s Investor.gov risk-tolerance guidance connects that decision to your goals, timing and ability to live with losses.
A terminology distinction matters: the SEC defines risk tolerance as both ability and willingness to lose money. This guide separates emotional willingness (tolerance) from financial ability (capacity) and behavior under stress (composure), so a mismatch is easier to recognize.
Being willing to see a 20% market decline does not mean you can afford one. Conversely, having substantial assets does not obligate you to hold an aggressive portfolio. The right level of investment risk follows the job the money must do—not a personality label. If the terms are getting blurred, see the separate explanation of asset allocation versus diversification.

If you want to see how standard questionnaires frame the issue, MRM also has a separate Risk Tolerance Questionnaire. This guide has a different job: help you interpret your answers before choosing investments.
The three dimensions: willingness, capacity, and composure
Risk tolerance — willingness
- What it asks
- How much uncertainty or loss can I emotionally accept?
- What changes the answer?
- Actual reaction to volatility, goals, experience, expectations.
Risk capacity — ability
- What it asks
- Could my finances absorb a decline without disrupting important plans?
- What changes the answer?
- Time horizon, withdrawal timing, cash needs, stable income, debts and reserves.
Risk composure — behavior
- What it asks
- Will I follow the plan when markets are frightening?
- What changes the answer?
- Past behavior, decision rules, support, the gap between intentions and actions.
These dimensions can point in different directions. When they conflict, treat the conflict as useful information—not a reason to average everything into a single score. This is a practical teaching model, not a framework the SEC mandates; John Grable’s CFA Institute Research Foundation review discusses risk capacity, preference and composure as distinct inputs in financial risk profiling.
A fourth issue to examine is risk need: the return or financial outcome your goals require is not necessarily the risk you can afford or are willing to take.
Example: a couple with very different attitudes toward risk
Consider a hypothetical couple approaching retirement. One spouse has a stable pension and feels comfortable with stock-market volatility. The other expects to begin portfolio withdrawals soon and finds a large loss difficult to tolerate. Their household might have meaningful financial resources, but an aggressive allocation designed around the first spouse alone could still fail the household.
The planning answer isn’t simply “be conservative” or “take more risk.” First isolate money needed soon from money intended for much later, then choose a mix and a set of decision rules that both people understand and can realistically maintain. Capacity, willingness and behavior must all fit.
What risk capacity looks like in practice
Capacity isn’t one fixed age cutoff. A 63-year-old with steady income, separate emergency reserves and a long-term legacy allocation may be able to take more investment risk with that portion than a 35-year-old whose down-payment money is needed next year.
Check when you expect to spend the money, whether withdrawals can be postponed, how stable other income is, and how a prolonged downturn would affect required payments. Someone whose spending keeps rising with every raise may also have less flexibility; MRM explains that pressure in its lifestyle creep guide. The SEC’s asset-allocation guidance explains why investment time horizon and risk tolerance affect an appropriate allocation.
A broad “five years” or “ten years” rule of thumb cannot replace your actual spending schedule.
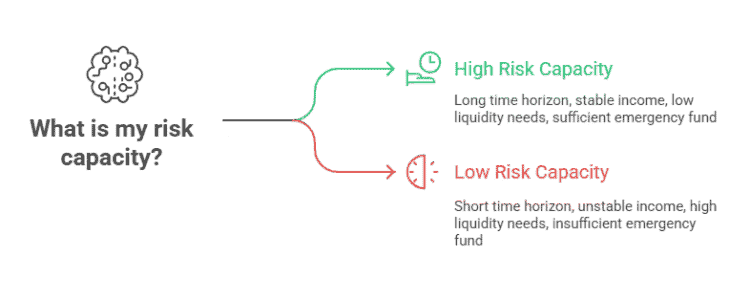
Read the diagram carefully: A long horizon, stable income and sufficient reserves may increase capacity to bear risk, but they do not automatically increase someone’s emotional willingness. The two can move in opposite directions.
What risk composure adds
A questionnaire asks what you think you would do. Composure asks what your history and habits suggest you actually do. Did you sell at a loss during a past market decline? Did you rebalance according to a written rule? Did you keep contributing because the money was long-term? There’s no value in pretending past reactions didn’t happen.
An imagined stress test helps, too, but it’s not a psychological diagnosis. If a $1 million portfolio temporarily fell 20%, the statement would show about $800,000. Would you still be able to fund planned withdrawals? Would you want to sell immediately? The first question tests capacity; the second probes willingness and composure. The same numerical loss can have very different consequences for two households.
How to assess your risk before choosing investments
Step 1 — Identify the money’s job. Write down which goals are near-term, which are decades away, and which depend on regular distributions. Separate emergency and known spending needs from assets that can remain invested through a downturn. Readers building a cash buffer from scratch may find the seven baby steps approach useful as a separate starting point.
Step 2 — Use a questionnaire as an opening conversation. Answer honestly about acceptable losses, volatility and what would make you uncomfortable. Don’t mistake a quiz result for a guaranteed allocation recommendation or a prediction of your behavior.
Step 3 — Check your financial capacity. Ask what happens to cash flow and planned withdrawals if the portfolio declines and remains lower for years. Include fixed expenses, other reliable income, debt and how flexible the goal really is.
Step 4 — Review behavior and build guardrails. Look at the decisions you actually made during prior downturns. Consider predetermined rebalancing rules, a written investment policy, an appropriately sized reserve, and a check-in process that avoids trading on a scary headline.
Step 5 — Reconcile the result. If willingness, capacity and composure disagree, don’t hide the disagreement by selecting the middle quiz score. Adjust the allocation, time horizon, withdrawal plan or behavioral support until the plan makes sense as a whole.
Try the MRM 3-D Risk Profile Analyzer
The interactive tool below explores your willingness to take risk, the financial circumstances that constrain it, and how you may react under pressure. Use it to find useful questions and a starting point for a planning conversation. It cannot determine a universally correct allocation from a few inputs, replace your full financial picture, or eliminate market risk.
The 3D Risk Profile Analyzer
Explore three separate dimensions of investment risk: your willingness to accept volatility, your financial ability to absorb losses, and your likely behavior during difficult markets.
Your 3D Risk Profile
Illustrative allocation range
Michael’s perspective
What to examine before choosing an allocation
How your risk profile should affect your portfolio
The practical output isn’t a permanent label such as “aggressive.” It’s an allocation and an investment policy you can explain when markets are calm and follow when they are not.
For someone making withdrawals soon, that might mean giving near-term spending a more stable funding source so a market decline doesn’t automatically force stock sales. For a younger investor saving for a distant goal, the same framework might support greater long-term growth exposure—but only if they can sustain the risk and still meet nearer obligations.
Diversification matters because it spreads risks across investments and assets; it does not make losses impossible. Use Investor.gov’s explanation of asset allocation and diversification to understand the building blocks rather than chasing one universal stock/bond percentage.

If a proposed portfolio looks comfortable only when markets are rising, it isn’t finished. Put the plan through an ordinary-language test: What could make me change this allocation, and what would not? A changed retirement date or spending requirement may justify a deliberate revision. A startling headline by itself usually doesn’t establish a new financial need.
When should you reassess risk tolerance?
Reassess when your circumstances or goals materially change: retirement moves closer, income becomes less predictable, you begin withdrawals, you take on significant obligations, or a major life event changes who relies on the money. Also reassess after discovering a persistent mismatch between your stated comfort and actual investment behavior.
That doesn’t mean changing the portfolio after every market swing. An annual planning review can be sensible; a genuine change in circumstances can warrant attention sooner. Document what changed and how the proposed adjustment addresses it.
Three questions to answer before your next portfolio decision
- Willingness: What loss or volatility would make me feel compelled to abandon the strategy?
- Capacity: What happens to required spending and near-term goals if that loss occurs and recovery is slow?
- Composure: What decision rules, support and safeguards make it realistic for me to follow the strategy when emotions run high?
Your answers should lead to a specific action: update the allocation, revise the spending plan, strengthen a reserve, write an investment-policy rule, or confirm that the existing plan still fits. Then connect it to the broader financial planning process rather than treating risk as an isolated questionnaire result. A quiz score without a decision is trivia.
My takeaway: The best risk profile isn’t the boldest one. It’s one that can survive contact with both the market and your actual life.
If you’re working through those decisions around retirement, the Financial Clarity Newsletter offers practical explanations of investment, tax and retirement trade-offs.
How We Verified This
These are the authorities and references used to verify the material facts in this article.
