

SIPC coverage protects customers when a SIPC-member brokerage firm fails financially and cash or securities are missing from customer accounts. It does not insure you against market losses, bad investment advice, or every dollar of value in an account simply because the balance is above $500,000.
That distinction matters because the number most investors remember is $500,000. The number is real, but the mental model around it is often wrong.
Quick Answer
SIPC is primarily protection against custody failure, not investment loss. If a member brokerage fails and customer property is missing, SIPC protection can cover a shortfall up to $500,000 per customer in each separate capacity, including a $250,000 limit for cash claims. If your stocks simply fall in value, SIPC does not make you whole.
During the 2008 financial crisis, I took calls from clients who were terrified by brokerage failures and the word “bankruptcy” on the news. The useful conversation was never “your investments cannot lose money.” They obviously could. It was separating market risk from the risk that the firm holding their assets could fail to return property that should still belong to them.
After nearly three decades in financial planning, that is still the first distinction I would make today. Before worrying about whether your account has $400,000 or $900,000, ask a better question: What exactly is in the account, where is it held, and which protection applies?
Key Takeaways Ahead
What SIPC Coverage Actually Protects
The Securities Investor Protection Corporation says SIPC protects cash and securities held by customers at financially troubled SIPC-member brokerages when customer assets are missing. Its job is to restore the custody function of the broker-dealer.
That can include stocks, bonds, Treasury securities, certificates of deposit held as securities, mutual funds, exchange-traded funds, and money market mutual funds. SIPC’s current statutory protection limit is $500,000 per customer in each separate capacity, including up to $250,000 for cash claims.
The $500,000 limit is a shortfall limit, not a portfolio-size warning
This is the point that gets lost. A brokerage customer’s securities are supposed to be segregated and accounted for. If your brokerage fails but your 1,000 shares of an ETF are properly there, SIPC does not need to “insure” the market value of those shares. The liquidation process is designed to return or transfer customer property.
The $500,000 limit becomes relevant when there is a shortfall in customer property. The SEC and SIPC’s joint Investor Bulletin on SIPC protection describes SIPC as advancing up to $500,000 per customer, including a $250,000 cash-claim limit, to cover such a shortfall.
Don’t Read the Limit Backward
A $700,000 brokerage account does not mean $200,000 is automatically “uninsured” in the same way an excess bank deposit may be above an FDIC limit. First ask whether the securities are present and properly recorded. SIPC addresses missing customer property after a member broker failure.
What SIPC Does Not Cover
SIPC is narrow on purpose. It is not a warranty on your investment choices.
- Market losses: If a stock, bond, fund, or other investment drops in value, SIPC does not reimburse the decline.
- Bad investment advice: SIPC does not cover losses caused by poor recommendations or unsuitable investment advice.
- Worthless or fraudulent investments: Buying a security that turns out to be worthless is different from the brokerage failing to return a security that should be in your account.
- Most crypto assets: SIPC says a digital or crypto asset that does not qualify as a “security” under SIPA is not protected. Unregistered digital-asset investment contracts also do not qualify for SIPA protection.
- Many non-security products: Commodity futures, foreign-exchange trades, and fixed annuity contracts that are not registered securities generally fall outside SIPC protection, subject to the specific rules SIPC describes.
The crypto point deserves the qualification. The old shortcut “crypto has zero SIPC protection” is too broad. The current rule turns on whether the specific digital asset qualifies as a security under the Securities Investor Protection Act and meets the applicable registration requirements. For many crypto assets, the answer is still no, but the legal classification matters.
Cash Is Where SIPC vs. FDIC Gets Tricky
The word cash can describe several different things inside a brokerage relationship, and they do not all receive the same protection.
- Brokerage cash held for buying or from selling securities: SIPC can protect qualifying cash, subject to the $250,000 cash-claim sublimit.
- Money market mutual fund: This is a security, not a bank deposit. SIPC treats a qualifying money market mutual fund as a security.
- Bank sweep deposit: Cash swept from a brokerage to an FDIC-insured program bank may receive FDIC coverage under the bank-deposit rules rather than SIPC protection while it is on deposit at the bank.
- Cash held only to earn interest: Do not assume the SIPC cash limit automatically applies. The SEC’s investor bulletin warns that the purpose and location of the cash matter.
This is why “my brokerage cash is insured” is not specific enough. Check the account disclosure or statement to see whether the balance is brokerage cash, a money market mutual fund, or a bank-sweep deposit.
Michael’s Take
If you remember only one question from this article, make it this: What is the legal and financial wrapper around this dollar? The same screen may show a stock, a money market fund, brokerage cash, and an FDIC bank sweep. They can look equally liquid while sitting under different protection rules.
SIPC Separate Capacity: Why Two Accounts Are Not Automatically Two Limits
SIPC does not simply give you another $500,000 because you click “open new account.” Protection for multiple accounts is determined by separate capacity.
SIPC’s multiple-account guidance says accounts held in the same capacity are combined for the protection limit. Different capacities can receive separate protection.
- Two individual brokerage accounts in the same person’s name at the same member firm are generally combined for SIPC-limit purposes.
- An individual account and a qualifying joint account are separate capacities.
- A traditional IRA and a Roth IRA are listed by SIPC as separate capacities.
- Trust, corporation, executor, and guardian accounts can also represent separate capacities when the SIPC rules are satisfied.
The important word is capacity, not account. Do not retitle assets, create trusts, move retirement money, or split ownership just to chase a higher SIPC number without understanding the tax, estate-planning, beneficiary, creditor, and control consequences. SIPC capacity is a protection rule, not an investment strategy.
SIPC vs. FDIC: The Difference in Plain English
SIPC and FDIC both support confidence in financial institutions, but they protect different things. The FDIC standard insurance amount is $250,000 per depositor, per insured bank, for each ownership category. SIPC, by contrast, protects qualifying customer property at a failed SIPC-member brokerage, subject to its separate-capacity rules.
| Feature | SIPC | FDIC |
|---|---|---|
| Primary job | Restore missing qualifying customer cash and securities when a SIPC-member brokerage fails | Insure qualifying deposits if an FDIC-insured bank fails |
| Standard limit | $500,000 per customer in each separate capacity, including a $250,000 cash-claim limit | $250,000 per depositor, per insured bank, per ownership category |
| Stocks and mutual funds | May be protected as securities against a custody shortfall | Not FDIC-insured deposits |
| Market losses | Not covered | Not an investment-loss program |
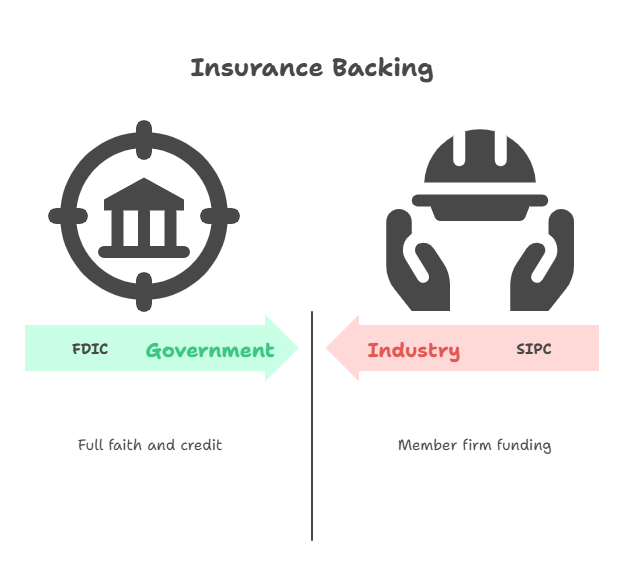
| Government backing | Nonprofit corporation created under federal law and funded through member assessments | Deposit insurance is backed by the full faith and credit of the U.S. government |
For a deeper look at deposit insurance itself, see my guide to FDIC insurance.
What Happens If Your Brokerage Actually Fails?
A brokerage failure does not automatically mean every customer files a $500,000 insurance claim. SIPC liquidation is a legal process focused first on identifying customer property and restoring it.
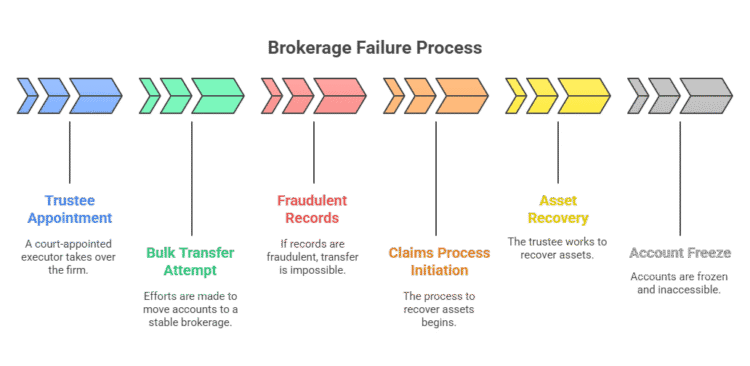
- A liquidation begins. A court-appointed trustee, or SIPC in a smaller case, takes control of the failed firm’s books and records.
- Customer records and property are identified. SIPC notes that poor records can make this step take longer in difficult cases.
- Accounts may be transferred. When possible, customer accounts can be moved to another brokerage firm rather than liquidated into cash.
- Claims are processed when needed. Customers receive information about filing with the trustee and must pay attention to the applicable claim deadlines.
- SIPC advances can cover an eligible shortfall. The protection limits apply to missing qualifying customer property after the liquidation rules are applied.
SIPC’s current liquidation guide intentionally avoids promising one universal timeline. Some records can be organized quickly; disarray can take weeks or months. That is more useful than pretending every failure produces the same frozen-account period.
How to Check Your Own Brokerage Protection
You do not need a crisis to answer the important questions. A five-minute protection check is usually enough to expose the gaps.

- Confirm the brokerage is a SIPC member. Most SEC-registered broker-dealers serving the investing public are members, but verify rather than assume.
- Identify what you actually own. Separate securities, brokerage cash, money market mutual funds, bank-sweep deposits, crypto, and other products.
- Identify the account capacity. Individual, joint, IRA, Roth IRA, trust, and other capacities can be treated differently under SIPC rules.
- Read the cash disclosure. If your brokerage uses a bank-sweep program, identify the program banks and the applicable FDIC treatment. If it uses a money market fund, remember that a mutual fund is a security rather than an FDIC deposit.
- Check for excess coverage separately. Some firms buy additional private insurance above SIPC limits, but terms, exclusions, aggregate caps, and triggers vary by firm. Treat it as a contract to verify, not a universal benefit.
The Five-Minute Test
For every large balance, be able to finish this sentence: “This is a security, brokerage cash, money market fund, bank deposit, or other asset, held in a specific account capacity, and the protection that applies is SIPC, FDIC, private excess coverage, or none of those.” If you cannot fill in those blanks, that is the next thing to verify.
Want One Practical Account-Safety Check Each Week?
If this SIPC review made you realize that “cash,” “insured,” and “protected” can mean very different things depending on the account, I’ll help you keep spotting those distinctions before they become expensive surprises. My newsletter gives you one practical money check at a time, with the same plain-English line between what matters and what is just financial noise.
SIPC Coverage FAQ
Is it safe to have more than $500,000 at one brokerage?
Having more than $500,000 at a brokerage does not automatically mean the amount above $500,000 is exposed to ordinary brokerage bankruptcy. Customer securities are supposed to be held for customers. SIPC’s limit applies to an eligible shortfall in missing customer property after a SIPC-member firm fails. Your actual risk also depends on the assets, account capacity, broker, clearing arrangement, and any excess coverage.
Is SIPC coverage $500,000 per account?
Not simply. SIPC uses separate capacity. Accounts in the same capacity at the same firm are combined, while qualifying accounts in different capacities can receive separate protection. SIPC gives examples including individual, joint, traditional IRA, Roth IRA, trust, corporation, executor, and guardian capacities.
What is the difference between SIPC and FDIC insurance?
SIPC protects qualifying customer cash and securities when a SIPC-member brokerage fails and customer property is missing. FDIC insurance covers qualifying bank deposits if an FDIC-insured bank fails. The standard FDIC limit is $250,000 per depositor, per insured bank, per ownership category.
Does SIPC cover cryptocurrency?
Do not assume it does. SIPC says a digital or crypto asset that does not qualify as a security under SIPA is not protected, and unregistered digital-asset investment contracts do not qualify for SIPA protection. The classification and registration status of the specific asset matter.
How do I file a SIPC claim?
If a SIPC liquidation requires claims, the trustee provides claim instructions and deadlines. File with the trustee using the process established for that case. SIPC maintains current open-case and claim information on its website.
Bottom Line: Know What SIPC Is Protecting Before You Count the Limit
SIPC is best understood as a brokerage-custody protection system. It helps restore qualifying cash and securities when a SIPC-member brokerage fails and customer property is missing. It does not protect you from owning a bad investment, watching the market fall, or assuming every “cash” balance on a brokerage screen is the same financial product.
The $500,000 number matters. But before moving assets around because a statement crossed that line, identify the asset, the custody arrangement, the account’s separate capacity, and the protection that actually applies. That is the difference between using the rule and merely reacting to the number.
Sources
- SIPC: What SIPC Protects
- SIPC: Investors with Multiple Accounts
- SIPC: How a Liquidation Works
- SEC Investor.gov: SIPC Protection, Part 1
- FDIC: Deposit Insurance at a Glance
This article is for general educational purposes and is not investment, legal, or tax advice. Brokerage arrangements, account terms, asset classifications, clearing relationships, private excess insurance, and regulatory treatment can vary. Verify the current terms for your specific account and firm.
