Take a different kind of investment risk quiz. Test your past behavior, your temptation to time the market, and whether this money can afford the trip you have planned.
An investor with $100,000 and an investor with $5 million can both tell a questionnaire they’re comfortable with a 20% decline. That’s a checkbox.
Now send each of them a brokerage statement. One shows a $20,000 decline. The other shows $1 million gone from the account value. Neither person necessarily panics. They might hold every investment. But suddenly the question isn’t hypothetical. That statement is sitting right there.
And a funny thing can happen even to someone who genuinely accepts market risk: “My tolerance hasn’t changed. But if we know the market’s about to drop, why don’t we just get out and buy back afterward?”
That’s the question a standard risk tolerance questionnaire often misses. The issue isn’t always fear. Sometimes it’s the entirely human belief that we can see the next detour coming—and know precisely when to get back on the road.
The short answer: An investment risk questionnaire should help you examine three separate questions: how you have actually reacted to losses, whether you can financially withstand them, and whether your plan makes sense for what this particular money must accomplish. Your answers are clues, not a precise risk score or a stock-allocation recommendation.

On This Page
- Take the Risk Tolerance Reality Check
- The statement test: your brain sees dollars, not percentages
- Brake lights aren’t a reason to turn the car around
- What actual investor behavior research can—and cannot—prove
- Risk tolerance, risk capacity, and risk composure are different questions
- A millionaire and a beginner can get the same result for different reasons
- Different trips require different transportation
- What to do with your quiz result
- Risk Tolerance Questionnaire FAQs
- Michael’s final thought
Take the Risk Tolerance Reality Check
Start with what has happened, not the brave version of what you promise you’ll do next time. This three-part assessment uses a dollar-loss scenario, questions about past transactions, your temptation to move into cash and back, and the timing of your financial goals.
Michael Ryan Money • Interactive reflection tool
Risk Tolerance Questionnaire: What Happens When the Loss Is Real?
Most quizzes ask what you would do. This one starts with what you've actually done, then checks your urge to predict the market and whether your money can afford the trip.
The result is deliberately different from the typical conservative / moderate / aggressive investor label. It identifies a question that needs attention, shows why the answer matters, and gives you one practical next step. It cannot tell you a suitable percentage to invest in stocks, bonds, or cash.
The statement test: your brain sees dollars, not percentages
On a risk assessment, “Would you stay invested through a 20% market decline?” sounds straightforward. But a decline is not a trivia question. Your reaction can change when the amount at stake becomes real.
- $25,000: a $5,000 decline leaves $20,000.
- $250,000: a $50,000 decline leaves $200,000.
- $1,000,000: a $200,000 decline leaves $800,000.
- $5,000,000: a $1,000,000 decline leaves $4,000,000.
These are arithmetic examples of a uniform 20% portfolio decline, not forecasts. A diversified portfolio may gain or lose a different amount from a stock-market index. But the emotional point stands: the same percentage carries very different dollar consequences.
A 20% drop also requires a 25% gain from the lower value just to return to the starting amount, before fees, taxes, withdrawals or deposits. None of this means you should sell. It means the scenario deserves more thought than a quick checkbox.
Ask a better question: “What happened the last time my account dropped a meaningful amount?” Did you stay invested? Follow a rebalancing rule? Make contributions? Move into cash? Stop checking statements? Call an adviser? Sell because you needed money for a real obligation?
Don’t mark all those behaviors as “panic.” Selling to meet an unavoidable expense isn’t the same as selling because a headline made you predict another 15% decline. Even the investor who didn’t sell may have spent weeks searching for reasons to change course. Composure is not the absence of discomfort; it is what you actually do with it.
If you have never lived through a major decline with a large balance, “I don’t know yet” is a more useful answer than pretending to have proof.
Brake lights aren’t a reason to turn the car around
Imagine you’re driving across the country. Before you left, you knew you would encounter construction, thunderstorms, traffic jams and stretches where you barely move. An hour into the trip, you see brake lights ahead.
Do you turn around and go home?
Probably not. You look at the road conditions, maybe adjust your route, and keep the destination in mind. The traffic isn’t a surprise. It was always part of the trip.
Investment volatility is similar—but the analogy has an important limit. A road can close completely. You can run short on fuel. A medical emergency can change your destination. Those are real reasons to alter the plan. The lesson is not “never change investments.” It’s “know whether the facts have changed, or you’re reacting to a forecast.”
The market version of seeing brake lights is hearing, “Recession is coming. Stocks are going to fall.” You might reply, “Fine, let’s just step aside until it’s over.”
That sounds reasonable. It doesn’t even sound like panic. But it introduces a second, harder question: What gets you back in?
When news becomes reassuring? When stocks stop falling? When they’ve recovered half their losses? Each possibility requires a forecast about the future. The first call—getting out—doesn’t complete the strategy.
Charles Schwab’s research on market timing illustrates why waiting for perfect timing can have a meaningful opportunity cost. Its examples don’t prove that every tactical move is wrong. They do challenge the assumption that a market decline will give you an obvious, safe exit and re-entry window.
In a 2025 Bogleheads discussion, an investor described selling a broad-market fund expecting another tariff-related decline, only for the market to reverse after a policy announcement hours later. That’s one self-reported experience, not a statistical sample. It captures the precise moment your “I’ll get out and come back” question should force you to confront.
Better risk-quiz question: “If you temporarily sold because you expected further declines, what specific condition would make you invest again—and what would you do if prices rose before that condition arrived?”
The purpose isn’t to shame someone for considering tactical changes. It’s to make the second decision visible before the first one is made.
What actual investor behavior research can—and cannot—prove
Morningstar’s 2026 Mind the Gap research estimates that the average dollar invested in U.S. mutual funds and ETFs earned 8.7% annually in the ten years ended December 31, 2025, compared with 9.9% for those funds’ aggregate annual total return. The 1.2-percentage-point difference reflects the timing and size of investor cash flows.
That is important evidence for the role of investor decisions. It is not proof every shortfall came from panic selling. Scheduled deposits and withdrawals, changing financial needs, volatile funds, and other factors all affect dollar-weighted results. The strongest lesson is that how and when money enters or leaves a strategy can matter substantially—not that all action is irrational.
A May 2026 peer-reviewed study of 108 retail investors compared a standard risk-preference survey with an incentivized decision exercise and actual portfolio choices. The experimental measure predicted those investors’ portfolio choices better at onboarding and six months later. It was a small, specific study—not proof all risk questionnaires fail or that this page’s unpaid hypothetical scenarios predict behavior. The useful conclusion is narrower: what someone says about risk and the choices they make under real incentives are not interchangeable.
Online investors put this more plainly than a questionnaire’s “high tolerance” box. In a 2026 Bogleheads discussion, participants debated whether a short drawdown followed by a quick recovery really tests the ability to endure a deep, prolonged bear market. In the comments on Erin Talks Money’s risk-capacity video, one retiree described maintaining a cash buffer—and wondering what happens if a slump outlasts it. These are individual experiences, not population data. Together, they suggest better questions about how long, how much, and what bills still have to be paid.
This is why the revised quiz asks about actual trades, untested experience, and written rules—not just how brave you expect to be.
Risk tolerance, risk capacity, and risk composure are different questions
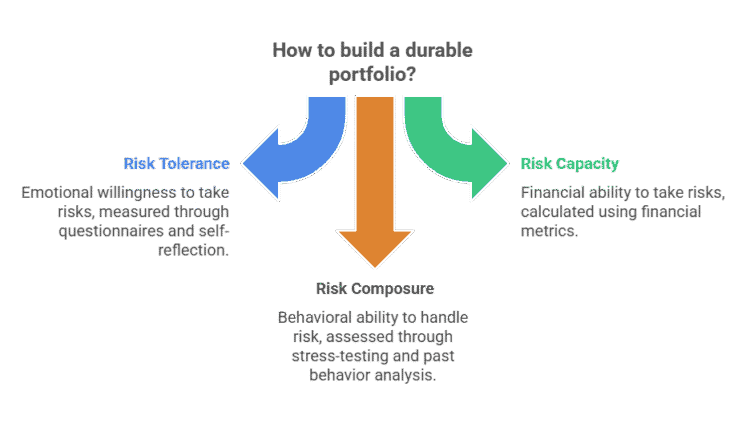
The SEC uses risk tolerance to mean an investor’s ability and willingness to lose investment value in pursuit of potential returns. That’s the broad definition. For making better personal decisions, it is useful to separate the ingredients:
Emotional risk tolerance — what loss are you willing to live through? This includes your preferences for stability, how losses affect you, and what trade-off between possible gain and loss you willingly accept. Loss aversion is one behavioral-finance explanation for why losses may loom especially large, but a basic quiz cannot clinically diagnose your biases.
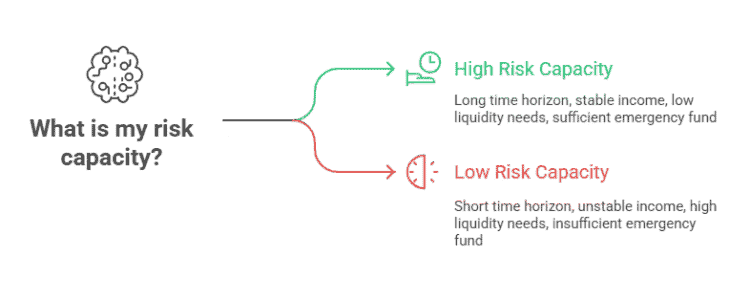
Risk capacity — what loss can you financially absorb? This depends on your financial obligations, investment time horizon, reliable income, access to liquid assets, emergency needs, and flexibility to adjust spending. Someone with a pension covering basic expenses may be in a different position from someone who must withdraw from the same portfolio every month. FINRA’s investor guidance stresses this distinction.
Risk composure — what behavior can you sustain when events become uncomfortable? Your transaction history and decision habits can provide evidence: selling based on a forecast, rebalancing by plan, rushing to “buy the dip,” or avoiding changes despite discomfort. Memories of past decisions are imperfect, so they’re a conversation starter rather than a validated prediction of future conduct.
Risk perception and market-timing confidence — how certain do you think you are? This is the trap in “my risk tolerance hasn’t changed, but I know the market is going down.” The person may have good emotional tolerance and reasonable financial capacity while still treating a speculative forecast as a known event. Behavioral-finance research describes how investor overconfidence can contribute to excessive trading; it does not tell us which particular prediction will prove right. See the NBER review by Daniel and Hirshleifer.
The dedicated Risk Tolerance in Investing guide explains these concepts in more depth. This page owns the questionnaire, interpretation and immediate action.

A millionaire and a beginner can get the same result for different reasons
Consider three illustrative scenarios—not real clients or proof that a particular allocation is right.
A new investor with $15,000 has decades before the money is intended for retirement, steady income and a separate emergency reserve. A 20% drop is $3,000. The investor knows the theory but has never actually experienced a serious bear market. The useful result isn’t “aggressive.” It’s “Your future behavior is untested; write the rule before the next storm.”
A household nearing retirement with $1 million receives a statement showing $800,000 after an illustrative 20% decline. Its pension covers essentials, and planned discretionary spending can be deferred. It may have greater financial flexibility than another $1 million household—but that doesn’t tell us how the couple will feel about a $200,000 statement loss, or whether their investments are appropriately diversified.
A retired household with $5 million sees the same 20% decline: a hypothetical $1 million drop. It may be financially resilient if other resources cover required spending. Or it may have a concentrated portfolio, significant near-term obligations or a lifestyle dependent on withdrawals. A big net-worth number doesn’t settle the question. Neither does being calm. The money’s job is what matters.
Ask the same practical questions of all three: What is this pool of money for? When will I need it? What else pays the bills if markets are down? What did I actually do last time?

Different trips require different transportation
You don’t charter a jet to go five miles. You also can’t sensibly plan to walk from the United States to China. The destination, distance, conditions and schedule influence the way you travel.
An emergency reserve, a home down payment due soon, a retirement withdrawal plan, and a long-term legacy portfolio don’t have identical time horizons or liquidity requirements. They shouldn’t automatically use identical investments because the same person filled out the same risk tolerance test.
The SEC’s asset-allocation guidance connects asset allocation—the mix of stocks, bonds and cash—to time horizon and risk tolerance. It also explains why diversification and periodic rebalancing matter. Those are related, but not interchangeable, decisions:
- Asset allocation is the mix you choose for the goal and risk exposure you can support.
- Diversification limits dependence on any one holding or risk source; it does not remove losses or guarantee protection.
- Rebalancing restores a pre-chosen mix after markets change relative weights. This differs from changing the whole strategy because you predict next month’s headlines.
- Liquidity planning identifies resources that can fund near-term obligations without forcing sales of depressed risk assets. Cash has inflation costs and bonds can lose value; neither is a magical shield.
- Sequence-of-returns risk concerns the damage adverse returns can cause when withdrawals happen early in retirement. It belongs in the next-stage retirement income and allocation plan, not in a six-question personality score.
If the trip is changing, update the plan. If the road is simply experiencing normal traffic, follow the plan unless a documented rule or new fact calls for a change.
For actual portfolio implementation, use Asset Allocation for Retirees. A numeric asset-allocation model can help illustrate trade-offs, but check the underlying investments, withdrawals and assumptions before treating a modeled result as a personal plan.
What to do with your quiz result
Why an old-fashioned investor risk profile is not an investment prescription
You may recognize five labels from a traditional risk tolerance quiz: conservative, moderately conservative, moderate, moderately aggressive, and aggressive. They can describe a stated preference. They cannot, by themselves, establish an appropriate portfolio. A person with a high willingness to lose money may have a short investment time horizon or required withdrawals; someone who prefers stability may have decades before a particular goal.
The useful result is not another label for your personality. It is a clearer answer to what this money is for, what you actually did under stress, and which decision rule you can defend before the next decline.
A conventional investor risk profile may label you conservative, moderate, or aggressive. Such labels can describe a preference, but they cannot determine a suitable portfolio from this limited information. The Reality Check instead identifies a decision to investigate:
“Money-to-goal mismatch.” You may need investments to pay near-term expenses without a clear income or reserve source. First identify the actual bills, dates and other sources. That’s different from anxiety about markets.
“Market-timing temptation.” You are thinking about getting out until things look better. Write down the exit rule and the re-entry rule. Consider taxes, transaction costs and the possibility of a fast recovery. A clear rule is not proof you will outperform buy-and-hold.
“Past action worth reviewing.” Find the transaction or statement. Was it an unplanned change driven by prediction, a scheduled rebalance, or money needed for an obligation? Learn from what occurred without assuming history will repeat exactly.
“Response untested.” No major loss with this balance yet? That’s useful honesty. Compare a dollar-loss scenario with your goals and build a written response before circumstances test you.
“Decision rule needs writing.” It is hard to hold to a strategy that exists only in your head. Write a simple investment policy statement explaining the goal, intended mix, rebalancing method, near-term cash needs and the conditions that legitimately require reconsideration.
A five-minute risk decision memo
Write one sentence for each of these—not a new investor personality score:
- Destination: The money is intended to fund ______ by approximately ______.
- Statement shock: If this account dropped ______ dollars, the first thing I would verify is ______.
- Spending resilience: Essential withdrawals would come from ______ if markets were down.
- No crystal ball: I would not change investments solely because ______ predicts a decline; an actual reason to reconsider would be ______.
- Return to plan: Before selling or buying based on market conditions, I would check ______.
This gives you something you can use when the statement arrives, not a number that disappears when you close a browser tab.
Financial Clarity Newsletter
One practical money decision at a time. Get Michael Ryan Money’s Financial Clarity Newsletter.
Risk Tolerance Questionnaire FAQs
What does a risk tolerance questionnaire measure?
A questionnaire explores your willingness, and sometimes ability, to accept uncertainty. It cannot prove how you will act in the next decline without appropriate validation and real financial context.
How accurate is a risk tolerance score?
Accuracy depends on how the tool was developed and validated. This Risk Reality Check is an educational reflection tool, not a scientifically validated risk score or a stock-allocation recommendation.
Is moving to cash before a crash the same as panic selling?
No. It can be a calm choice, but if the decision depends on predicting the next decline, it is market timing and requires both an exit and a re-entry decision. Actual spending needs may justify reviewing the investment plan.
How often should I retake an investment risk assessment?
Review your strategy when a meaningful fact changes: retirement, withdrawals, job loss, new income, major expenses, an allocation shift or actual behavior that differs from what you expected.
If I am comfortable with a 30% loss, should I own more stocks?
Not from that answer alone. Your ability to absorb losses, time horizon, withdrawal needs, diversification and goal matter as much as willingness.
Michael’s final thought
I don’t need you to promise me you’ll never worry. People are allowed to worry when a statement shows six or seven figures disappearing from an account.
I want to know what the worry will make you do—and whether you can still afford the trip if that rough stretch lasts longer than expected.
Traffic was in the itinerary. A wrong destination wasn’t.
