


To read a check, start with the line of numbers along the bottom. On a standard U.S. personal check, the 9-digit routing number is at the bottom left, the account number is directly to its right, and the check number appears in the upper-right corner and is often repeated in the bottom line.
The part people miss is not the location. It is the job of each number. The routing number identifies the financial institution; the account number identifies your account at that institution; the check number identifies that individual check. If a form asks for bank information, matching the number to the transaction matters more than memorizing the layout.
Quick Answer
Routing number: 9 digits, usually the first number at the bottom left of a standard personal check.
Account number: the number immediately to the right of the routing number; its length varies by bank.
Check number: the serial number in the upper-right corner and often again in the MICR line.
Before you submit anything: if the form specifically asks for a wire-routing number, stop and use your bank’s official wire instructions rather than assuming the routing number on the check is the right one.
Watch: How to Read Your Check
If you would rather see the numbers on a real check, here is my short video walkthrough:
If your goal is to fill out the front of the check rather than identify the numbers at the bottom, use my How To Write A Check.
Key Takeaways Ahead
How to Read a Check: The MICR Line and the Three Numbers That Matter
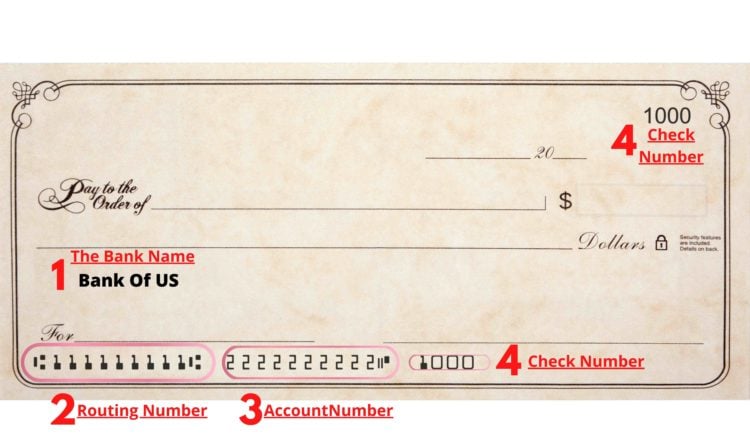
The bottom line is called the MICR line, short for Magnetic Ink Character Recognition. The Federal Reserve explains how MICR modernized check processing by letting machines read routing and account information from the check. In plain English: this line is where a machine — and you — can tell which bank, which account, and which check are involved.
Interactive Check Routing and Account Number Locator
Use the interactive explorer below to tap or hover over each field on a sample check.
[check_parts_explorer]
1. Routing Number: The Bank’s 9-Digit Identifier
For a standard U.S. personal check, the routing number is the 9-digit number at the bottom left. The American Bankers Association routing-number system identifies the paying financial institution. The routing number is not your personal account number.
- Use it for: transactions that ask for an ABA routing number, including many ACH and direct-deposit setups.
- Do not guess: banks can have more than one routing number, and wire instructions can be different. If a form says wire, verify the wire routing instructions with your bank.
- Sanity check: if what you think is the routing number is not exactly nine digits, you are probably looking at the wrong field.
Michael’s rule: copy the number from the place your bank tells you to use for that transaction. A check is a useful reference; your bank’s current ACH or wire instructions are the final authority.
2. Account Number: The Number for Your Specific Account
The account number is usually directly to the right of the routing number. Unlike the ABA routing number, account-number length is not standardized across banks. That is why trying to identify it by digit count is a bad shortcut.
- Include leading zeros. If your bank displays them as part of the account number, enter them.
- Do not substitute the check number. The check number identifies a piece of paper; the account number identifies where money is credited or debited.
- Verify before a high-stakes setup. For payroll, tax refunds, autopay, or a new ACH connection, compare what you typed with your bank app or online banking before you submit.

3. Check Number: The Serial Number for This Check
The check number is a short serial number used to identify that individual check. You will usually see it in the upper-right corner, and it is often repeated in the MICR line. It is not the number to use when a direct-deposit form asks for your bank account number.
If the printed check number and the serial number encoded at the bottom do not appear to agree, do not jump straight to “fraud,” but do pause. Verify the check with the issuing bank or payer before relying on it, especially when something else about the check looks wrong.
Which Number Do You Use for Direct Deposit, ACH, Wires, and Checks?
This is the practical distinction worth remembering. The same check can show all three numbers, but a form may be asking for only one of them. This is where the opening rule pays off: match the number to the transaction, not just to the spot where you found it.
| What you are doing | Number usually needed | What to verify |
|---|---|---|
| Direct deposit | Routing number + account number | Use the bank’s ACH/direct-deposit instructions and correct account type. |
| ACH autopay or bank debit | Routing number + account number | Confirm the company is legitimate and the account information is entered correctly. |
| Domestic wire | Bank’s wire instructions | Do not assume the routing number printed on the check is the wire-routing number. |
| Tracking a paper check | Check number | Match it to your register or bank’s check image. |
| Mobile check deposit | You normally deposit the check image, not manually type the MICR numbers | Follow your bank’s endorsement, photo, amount, and eligibility instructions. |
A one-digit error can create an annoying recovery problem. The cheap move is the boring one: compare the routing and account numbers one last time before you hit Submit.
Get Better at the Money Details That Cause the Biggest Headaches
You just learned the difference between a routing number, account number, and check number. I send one practical money move each week built around the same idea: catch the small detail before it becomes the expensive problem.
- Spot banking and payment mistakes before money gets delayed.
- Recognize check-fraud and account-security red flags.
- Know which number, form, or next step actually matters.
Join the weekly Michael Ryan Money email:
Why Check Numbers Still Matter in a Digital Banking World
Checks may be old technology, but the information printed on them is still connected to modern payments. The Consumer Financial Protection Bureau’s Regulation E coverage rules specifically recognize electronic transfers created when a merchant or payee captures routing, account, and serial numbers from a check.
Direct Deposits and ACH
Direct deposit and many ACH setups depend on the routing number identifying the right financial institution and the account number identifying the right account. If you use an account that is supposed to receive payroll or other recurring deposits, verify the details in your bank app or official account information before you submit them.
Check Washing and Fraud
A paper check exposes useful payment information: your name, bank routing number, account number, check number, and usually your signature. That does not make every check unsafe, but it is a reason to treat blank checks and mailed checks like sensitive financial documents.
The U.S. Postal Inspection Service warns about check washing, where stolen checks can be altered by changing the payee or dollar amount. Its practical advice is simple: protect outgoing mail, avoid leaving blank spaces on the check, and review cleared-check images and account activity.
Mobile Deposits and MICR Errors
With mobile deposit, your bank reads information from the check image. A cropped, blurry, poorly lit, or improperly endorsed check can create problems even when the routing and account numbers themselves are correct. If you use Chase, my Chase Mobile Check Deposit Guide walks through the current process and common rejection points.

Check 21 and Checks Older Than Six Months
The Federal Reserve’s Check 21 materials explain the legal framework that allowed banks to use substitute checks and check images in modern processing. That is one reason a physical check can become a digital image very quickly after it enters the banking system.
Age matters too. Under UCC Section 4-404, a bank is generally not obligated to pay a noncertified check presented more than six months after its date, although it may pay the check in good faith. If you find an old check, verify it rather than assuming “six months” automatically makes it worthless.
Can Someone Steal Money With Your Routing and Account Number?
Potentially, someone can misuse routing and account information, but those two numbers are not the same thing as handing over your online-banking password. A routing number identifies the bank and is widely used. Your account number is more sensitive because it identifies your specific account.
Bank-account information can be misused in an attempted unauthorized debit. For consumer electronic fund transfers, federal Regulation E provides error-resolution and liability rules in qualifying situations. The practical takeaway is not to panic over every legitimate request for these numbers; it is to share them only when needed, with a party you trust, through a secure process.
Your Best Defense
- Do not post or casually email a check image. A check can reveal your account number, routing number, address, check number, and signature.
- Use secure bank or employer portals when entering direct-deposit or ACH information.
- Review account activity and cleared-check images. Catching an unauthorized transaction quickly gives you more options.
- If something is wrong, contact your bank or credit union immediately. The CFPB explains the investigation process for unauthorized transactions and why reporting speed matters.
- If a mailed check was stolen or washed, report the mail theft or fraud. The Postal Inspection Service provides a reporting portal.
Michael’s take: the useful habit is not “never share your banking numbers.” You sometimes have to share them to get paid or authorize a legitimate debit. The habit is share the minimum information, through the right channel, for a transaction you understand.
How to Find Your Routing and Account Numbers Without a Physical Check
No checkbook? You do not need to hunt for an old paper check. The ABA Foundation direct-deposit guidance points people to bank statements, the bank’s mobile app or online platform, or the bank itself. Start with your bank’s app or online platform; if a statement does not show the full account number, use another official bank channel.
- Open your bank’s official app or website. Look for account details, direct deposit, or routing/account information.
- Check a recent statement. It may show the routing number and some or all of the account number.
- Call the bank using a number you independently verified. Ask which routing number applies to the transaction you are setting up.
- For a wire, ask specifically for wire instructions. Do not turn an ACH/direct-deposit routing number into a wire-routing number by assumption.

The 60-Second Check Before You Submit the Numbers
Before you hand your banking information to an employer, biller, tax preparer, or payment service, run this short check:
- Read the field label. Does it ask for routing, account, check, or wire information?
- Verify the routing number. For a standard personal check it should be nine digits; for wires, use official wire instructions.
- Verify the full account number. Keep any leading zeros your bank shows as part of the number.
- Ignore the check number unless the form specifically asks for it.
- Compare your entry one more time before submitting. Do not rely on memory for a number this easy to mistype.

That last comparison is the whole game. The routing number gets the transaction to the right institution. The account number gets it to the right account. The check number identifies the piece of paper. Expensive headaches start when those jobs get swapped.
Final Thoughts: Read the Job of the Number, Not Just the Number
You do not need to become a check-processing expert. You need to be able to look at a check, identify the routing number, account number, and check number, and understand why a form is asking for each one.
My rule is simple: identify it, match it to the transaction, verify it once, then submit it. That extra ten seconds is much cheaper than trying to unwind a payroll deposit, tax refund, autopay, or fraud problem after the fact.

Sources
I used the following primary or controlling sources to verify the banking, check-processing, fraud, and consumer-protection points in this guide:
- American Bankers Association — Routing Number policy and resources
- Federal Reserve Financial Services — History and Modernization of Check Services
- Federal Reserve Financial Services — Check 21 Act
- ABA Foundation — Direct Deposit consumer guidance
- Consumer Financial Protection Bureau — Regulation E coverage
- Consumer Financial Protection Bureau — Unauthorized transaction guidance
- U.S. Postal Inspection Service — Check Washing
- Uniform Commercial Code § 4-404 — Checks more than six months old
- U.S. Postal Inspection Service — Report mail theft or fraud
