

Closing a joint bank account sounds like a paperwork problem. Sometimes it is. Sometimes it is the moment you discover that the bank’s rules and the relationship’s rules are two very different things.
I once worked through a joint-account breakup where the other owner kept creating overdrafts after the relationship had already gone bad. At that point, nobody cared about the elegant definition of a joint account. The question was much simpler: How do I stop this account from doing more damage?
Here is the part most people miss: your partner may not have to cooperate for the bank to let you close the account. The CFPB says that, in most circumstances, either owner of a joint checking account can withdraw money and close it. But your account agreement and state law still matter, and a bank’s permission to move money does not settle who legally owns that money between you and the other person.
Quick Answer
If you want to close a joint bank account, first check the account agreement or ask the bank whether one owner can close it alone. Many banks allow it. Removing the other person’s name is different and usually requires consent. If the money itself is disputed because of divorce, separation, a business breakup, or litigation, do not treat bank access as a property settlement. Secure your own banking, reroute your income and bills, preserve records, then get legal advice before moving contested funds.
Key Takeaways Ahead
Can One Person Close a Joint Bank Account Without the Other?

Often, yes. The Consumer Financial Protection Bureau says that in most circumstances either joint owner can withdraw money and close a joint checking account. The CFPB also tells consumers to check the account agreement because the exact rule can vary.
That is not just theoretical. Chase says each joint owner can close the account. Bank of America says generally one owner can make that choice, although some banks require both parties. U.S. Bank’s current guidance says only one owner is needed to close a joint account.
Michael’s Take
This is where people get into trouble. Bank authority is not the same thing as legal entitlement. Your bank may let you transfer every dollar. A divorce court, partnership agreement, or state property law may have a very different opinion about whether you should have.
Keep that distinction in your pocket. We are going to use it again when the other owner refuses to cooperate.
Removing a Name Is Different From Closing the Account
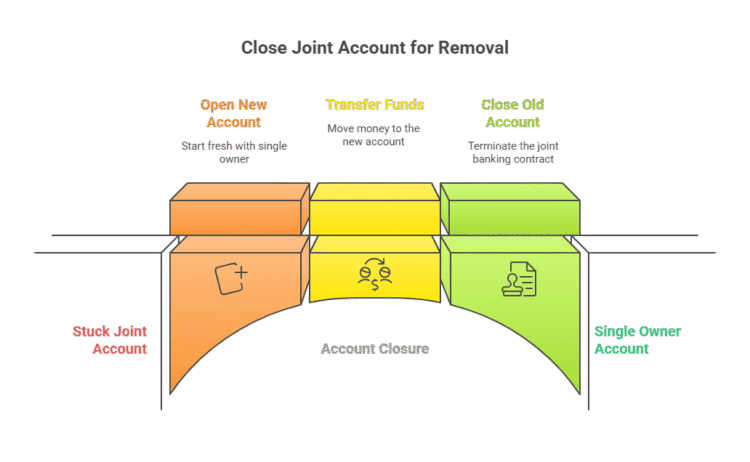
This is the first fork in the road. If you want to keep the same account and simply delete the other owner, the rules are usually stricter. The CFPB says you generally need the other owner’s consent to remove them from a joint checking account.
Wells Fargo, for example, says that if the joint owner being removed will not agree or cannot sign the required paperwork, the account needs to be closed and a new account opened. Chase takes a different approach: it says a joint owner can remove themselves, but one owner cannot simply kick out the other.
So if the relationship is over, stop thinking of the old account as something you need to edit. Think of it as plumbing you need to disconnect.
The 4-Step Financial Decoupling Plan
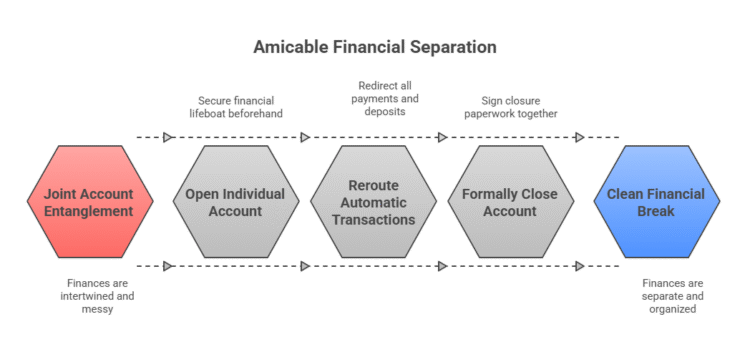
The safest sequence is boring on purpose. Boring is underrated when your paycheck, mortgage, and ex-partner are all touching the same checking account.
1. Secure Your Own Account First
Open an individual checking account before you dismantle the joint one. You need somewhere safe for your future paycheck, Social Security payment, tax refund, or other income to land.
If the breakup is hostile, consider using a different bank and update passwords, contact information, and security questions on accounts that are yours alone. This is the same basic principle behind getting your personal finances back under your control: build your own clean operating system first.
2. Detangle Direct Deposits and Automatic Payments
Make a list of everything that flows through the joint account. Do not rely on memory. Review several months of statements and look for:
- paychecks and benefit deposits;
- mortgage or rent;
- utilities and insurance;
- credit-card and loan payments;
- subscriptions and memberships;
- checks that have not cleared;
- scheduled ACH transfers and bill-pay instructions.
Move the items that are yours to your new account. Then give the old account enough time for pending transactions to surface. Closing an account while forgotten checks are still wandering around is how a clean break turns into an overdraft scavenger hunt.
3. Decide What Happens to the Balance
If the split is amicable, document the agreed division and transfer the money. If the money is disputed, especially during divorce or a business breakup, slow down.
The fact that a joint owner can often withdraw the entire balance does not answer who is ultimately entitled to keep it. That is the bank-rule-versus-legal-right distinction from earlier. Do not turn a checking-account button into a property-settlement strategy.
4. Close the Account and Verify It Is Really Closed
Once the balance and pending items are handled, follow your bank’s closure procedure. Depending on the institution, that may be online, by phone, by mail, or in a branch. Ask for written or electronic confirmation.
Do not confuse a zero balance with a closed account. A zero-balance account can still be an account.
I once watched a simple closure turn into a notary scavenger hunt because one owner was overseas. The lesson was not “always get a notary.” The lesson was: ask the bank what this specific account requires before you build your whole exit plan around assumptions.
What If Your Partner Refuses to Cooperate?
Now we get to the part the title promised.
If your partner refuses to sign, first find out whether their signature is actually required. Do not spend three weeks fighting someone for cooperation the bank never needed in the first place.
If your account agreement allows any joint owner to close the account, the bank may let you proceed alone. Chase’s deposit agreement, for example, says any joint owner may close a joint account without the consent of the others. Capital One says the same for its 360 Checking account. But remember the callback: the bank’s ability to follow your instruction is not a ruling on who owns disputed funds.
If the bank will not close the account on one owner’s instruction, ask what options the account agreement provides when co-owners are in conflict. Some banks reserve the right to restrict or block a disputed account, but they may not be required to do it. Chase, for example, says it may block a joint account when one owner asks it not to honor the other’s transactions, but it is not obligated to do so.
Watch Out
Do not call the bank and demand a “two-signature rule” or a freeze as though every institution must offer one. Ask what dispute restrictions your actual account agreement allows. The answer can vary by bank, account type, and state law.
If the account is part of a divorce, lawsuit, business dispute, or restraining order, that is where banking procedure stops being enough. A family-law or business attorney can tell you what you may do with the funds without creating a second problem while trying to solve the first one.
What About Overdrafts, Pending Checks, and New Charges?
A joint account can keep creating problems until it is actually closed. The CFPB warns consumers to account for pending checks, fees, and automatic payments before closing an account because those items can bounce or trigger fees.
Liability for an overdrawn joint account is governed by the account agreement and applicable law. Many agreements make each joint owner responsible for the full overdraft. Chase’s current deposit agreement does exactly that.
That is why “we stopped using it months ago” is not a closure strategy. Banks are annoyingly literal about this stuff. If the account still exists, the account can still have consequences.
If You Need to Protect Yourself Today, Do These Things First
- Download recent statements and transaction history. Preserve the record before anything changes.
- Open an individual account. Give your future income somewhere independent to go.
- Redirect income and bills that are yours. Do not leave your paycheck dependent on a disputed account.
- Call the bank and ask four exact questions: Can one owner close this account? Can one owner remove another owner? What happens if one owner reports a dispute? What pending items must clear before closure?
- Do not move disputed money just because the app lets you. If ownership is contested, get legal advice first.
- Get written confirmation when the account closes. Save it with your final statement.
If separating the account leaves you without a cash cushion, rebuilding an emergency fund becomes one of the first jobs of the new financial setup.
The Bottom Line
Closing a joint bank account is not always a two-person job. In many cases, one owner can do it. Removing the other owner’s name is usually harder and often requires consent.
But the bigger lesson is the one we kept coming back to: the bank question and the ownership question are not the same question.
The bank can tell you who has authority to click “transfer” or “close.” It cannot settle a divorce, divide a partnership, or decide whose money should ultimately end up where. Handle the plumbing quickly. Handle disputed ownership carefully.
