

You deposited a check, opened your banking app, and now the question is simple: when can you actually use the money?
For most ordinary U.S. check deposits in 2026, the answer is one to two business days. Under current Regulation CC funds-availability rules, the first $275 of a standard check deposit generally must be available by the next business day, with the remainder of a local check generally available by the second business day.
Quick Answer: How Long Does a Check Deposit Take to Clear?
- Most personal and business checks: first $275 available the next business day; the rest generally by the second business day.
- Some Treasury, government, cashier’s, certified, teller’s, and on-us checks: can qualify for next-business-day availability when the deposit meets Regulation CC’s conditions.
- Large or higher-risk deposits: can be held longer under specific exceptions.
- Mobile deposits: check the availability date shown by your bank; mobile-deposit policies can differ from an in-person deposit.
The important catch: “available” does not mean “guaranteed good forever.” A check can still be returned unpaid after your bank has made some or all of the deposit available.
In nearly three decades as a financial planner, I have seen the same cash-flow mistake in different forms: people treat an availability date as if it were a guarantee that the underlying check can never come back. Those are two different questions.
Key Takeaways Ahead
Available vs. Cleared: The Difference That Matters
Your banking app may use words such as pending, available, posted, or hold. The practical distinction is this: funds availability tells you when the bank lets you use the deposit; it does not prove the check cannot later be returned unpaid.

Federal rules intentionally require banks to make many check deposits available on a schedule. That is good for consumers—you should not have to wait indefinitely for routine deposits. But the check-collection process and the funds-availability schedule are not identical.
The Office of the Comptroller of the Currency explains that a bank may make deposited funds available before collection is complete. If the paying bank later returns the check unpaid, your bank can reverse the deposit. That is why a balance that looks spendable can still create trouble if the check turns out to be counterfeit or otherwise unpaid.
Do Not Treat “Available” as a Fraud Guarantee
If someone sends you a check and then asks you to send part of the money back, buy gift cards, pay a third party, or forward funds elsewhere, do not assume the check is safe because your bank released the money. The FDIC warns about counterfeit-check scams built around exactly that misunderstanding.
How Long Check Deposits Usually Take in 2026
For a standard check deposited into an established U.S. transaction account, the most useful baseline is:
- Day of deposit: Your bank determines the banking day based on its cutoff time.
- Next business day: The first $275 of a check that is not already a next-day item generally becomes available.
- Second business day: The remainder of a normal local check generally becomes available.
The Federal Reserve’s current examples use the same 2026 thresholds and show how the clock changes when a deposit is made after the bank’s cutoff.
| Deposit situation | Typical federal availability baseline | What can change it |
|---|---|---|
| Ordinary personal/business check | First $275 next business day; remainder generally second business day | Exception hold, cutoff time, new account |
| Qualifying Treasury / government / cashier’s / certified / teller’s check | Often next business day when Reg CC conditions are met | Deposit method, required special slip, new-account rules, exceptions |
| Check at a nonproprietary ATM | May be available by the fifth business day | Bank policy and applicable exceptions |
| Mobile check deposit | Use the bank’s stated mobile-deposit availability date | Bank’s mobile terms, cutoff, review, deposit risk |
Friday Deposit Example
Suppose you deposit a normal check after your bank’s cutoff on Friday. Saturday and Sunday are not business days, and the deposit may be treated as received Monday. Under the normal schedule, the first $275 would generally be available Tuesday and the remainder Wednesday. A Monday federal holiday pushes that sequence back another business day.
This is why “I deposited it Friday” does not always mean the clock started Friday. The bank’s cutoff time and the definition of a banking day matter.
Banking Rules Change Quietly. Your Cash Flow Notices Loudly.
The Regulation CC inflation adjustment is exactly the kind of quiet rule change that can make an old banking guide wrong overnight. Get practical banking and money-rule updates translated into what you actually need to do next.
A $10,000 Check Deposit Example Under the 2026 Rules
A large check is where the standard “one or two days” answer stops being enough.
The Federal Reserve gives a useful example of a $10,000 local check deposited with a teller on Monday:
- Tuesday: the first $275 must be available.
- Wednesday: another $6,450 is available, bringing the standard-schedule amount to $6,725.
- Amount above $6,725: the bank may use the large-deposit exception for the excess. In the Fed’s example, the final $3,275 becomes available the following Wednesday.
That does not mean every $10,000 check will be held that long. It means the bank is allowed to extend availability on the portion above the current $6,725 large-deposit threshold when it applies that exception and gives the required notice.
Michael’s Take
The planning mistake is not “depositing a big check.” It is scheduling rent, payroll, taxes, a closing, or another irreversible payment around money whose availability date you have not confirmed yet. For a large or unusual check, look at the bank’s actual hold notice before you promise that money somewhere else.
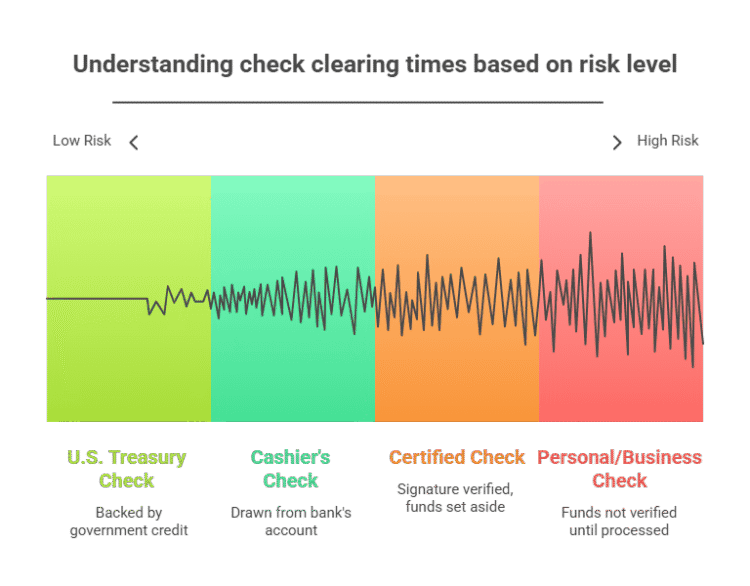
U.S. Treasury Check
Typical availability: Next business day when Reg CC conditions are met
Why? Treasury checks can qualify for next-day availability when deposited under the rule’s conditions. Counterfeits still exist, so availability is not the same as final payment.
Cashier’s Check
Typical availability: Next business day when deposited in person and other Reg CC conditions are met
Why? Cashier’s checks are next-day items under qualifying conditions, but a counterfeit cashier’s check can still be returned.
Certified Check
Typical availability: Next day when qualifying conditions are met; otherwise the normal check schedule may apply
Why? Certified checks receive special availability treatment under Regulation CC when the deposit meets the rule’s requirements.
Personal/Business Check
Typical availability: First $275 next business day; remainder generally by the second business day
Why? Personal and business checks generally follow the standard local-check schedule and may be subject to exception holds.
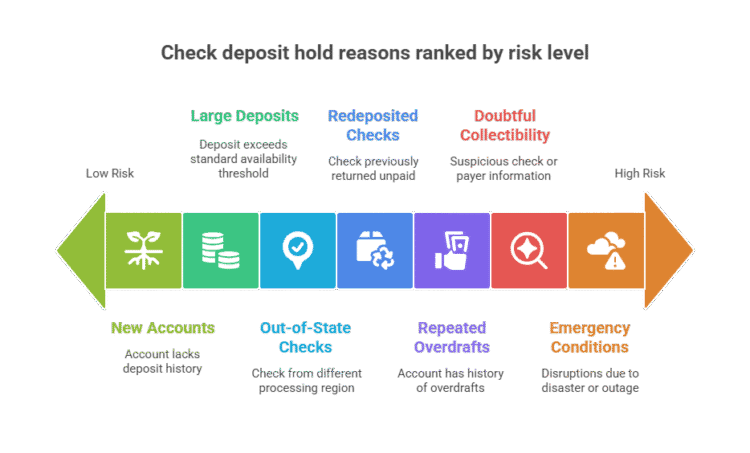
6 Reasons a Bank Can Hold a Check Longer
Regulation CC does not give banks unlimited discretion, but it does permit longer holds in specific situations. The Federal Reserve lists six main exception categories for check deposits.
| Exception | 2026 rule | What it means for you |
|---|---|---|
| Large deposit | Total check deposits exceed $6,725 in one banking day | The bank may extend the hold on the amount above $6,725. |
| New account | Account has been open fewer than 30 days | Special new-account availability rules apply; some non-next-day checks can be held under the bank’s new-account schedule. |
| Redeposited check | A check was previously returned unpaid and deposited again | The bank may delay availability, with limited exceptions when the original problem was corrected. |
| Repeated overdrafts | Account meets Regulation CC’s repeated-overdraft tests | Longer holds may apply to check deposits. |
| Reasonable cause to doubt collectibility | Bank has specific facts supporting concern that the check may not be paid | The notice should state the reason for the bank’s concern. |
| Emergency conditions | Events beyond the bank’s control disrupt normal processing | Availability can be delayed while the emergency prevents normal processing. |
For many ordinary local checks placed on an exception hold, the Federal Reserve describes a reasonable extension as generally up to five additional business days—which can make the total period seven business days. But seven days is not an automatic rule, and longer holds may be permitted when the bank can establish that the longer period is reasonable.
For the repeated-overdraft exception, the current threshold also changed. An account can qualify based on six or more banking days of negative balances in the previous six months, or on two or more banking days with a negative balance of $6,725 or more, subject to the rule’s details.
2026 Rule Update
The inflation-adjusted Regulation CC thresholds became $275 for the minimum next-day amount and $6,725 for the large-deposit threshold on July 1, 2025. Those are the applicable figures in 2026.
Does the Type of Check Change the Hold Time?
Yes—but not as simply as “cashier’s checks clear instantly” or “government checks can’t be held.” Regulation CC gives certain check types next-day treatment when specific conditions are met.
Checks That Can Qualify for Next-Day Availability
- U.S. Treasury checks deposited into the payee’s account.
- Certain state and local government checks.
- Cashier’s, certified, and teller’s checks.
- U.S. Postal Service money orders.
- Certain Federal Reserve Bank and Federal Home Loan Bank checks.
- Qualifying “on-us” checks drawn on the same bank.
The conditions matter. Some official checks must be deposited in person into the payee’s account, and a bank may require a special deposit slip for certain categories. If those conditions are not met, the ordinary schedule can apply instead.
Myth: “A Cashier’s Check Is Guaranteed, So There Can’t Be a Hold”
A genuine cashier’s check has special characteristics, but counterfeit cashier’s checks are real. The check type can affect the availability schedule; it does not make fraud physically impossible. If a cashier’s check is unusual, high-value, or from someone you do not know, verification still matters.
Does the Deposit Method Matter?
- Teller deposit: gives you a clear receipt and is required for next-day treatment of some official check types.
- Your bank’s ATM: can follow different timing for certain next-day checks than an in-person deposit.
- Nonproprietary ATM: Regulation CC can allow availability as late as the fifth business day.
- Mobile check deposit: follow the availability date in your bank’s app or mobile-deposit terms rather than assuming an in-person timetable.
If you use Chase, I have a separate walkthrough of Chase mobile check deposits, including the practical mechanics that belong on that bank-specific page rather than here.
[check_parts_explorer]
What to Do If Your Check Is on Hold
If your deposit is pending longer than you expected, do not start by arguing about whether the check is “obviously good.” Start by identifying the exact rule and date the bank is using.
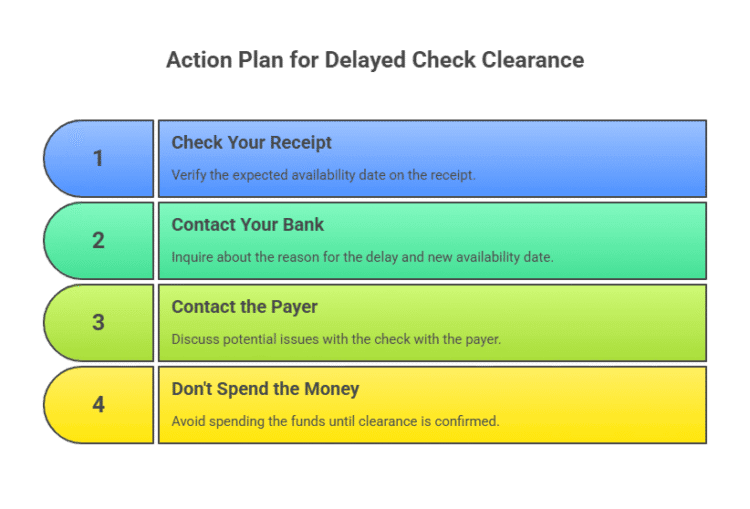
- Find the official availability date. Check your deposit receipt, app, email, or mailed hold notice.
- Confirm the banking day. Ask whether the deposit was received before or after the bank’s cutoff time.
- Ask for the hold reason. Is this a large-deposit exception, new-account rule, redeposited check, repeated overdraft, reasonable-cause hold, emergency condition, or a mobile-deposit policy?
- Ask what can actually be reviewed. A teller or branch manager may not control a fraud or back-office hold, but the bank should be able to tell you the scheduled availability date and the stated reason.
- Keep the notice. If the bank extends availability beyond its normal policy, Regulation CC generally requires a notice explaining why and when the funds will be available.
If the timeline still appears inconsistent with the bank’s disclosure or Regulation CC, escalate through the bank’s complaint process. For national banks and federal savings associations, the OCC’s HelpWithMyBank funds-availability guidance explains the current $275 baseline and the principal reasons a hold may be extended.
Best Question to Ask the Bank
Instead of “Has my check cleared yet?” ask: “What is the funds-availability date for this deposit, and what hold reason or policy produced that date?” That question is much harder to answer with a vague “it’s still processing.”
If slow paper-check timing keeps creating problems, electronic payments can avoid the paper-check availability cycle, although ACH transfers, wires, and person-to-person payments each have their own limits and fraud risks. For the ACH side of the problem, see why a direct deposit can be late.
Frequently Asked Questions
Why did my bank only make $275 of my check available?
For a check that is not otherwise entitled to next-day availability, Regulation CC generally requires the first $275 of the day’s check deposits to be available by the next business day. The remainder of a normal local check is generally available by the second business day unless an exception or other applicable rule changes the schedule.
Can a bank hold a check longer than 7 business days?
Yes, in some circumstances. The Federal Reserve describes five additional business days as a generally reasonable exception-hold period for local checks, which can produce a seven-business-day total. A longer exception hold may be permitted when the bank can establish that the longer period is reasonable.
Does a mobile check deposit take longer to clear?
It can. Mobile-deposit availability depends heavily on the bank’s mobile-deposit policy, cutoff time, and review. Use the availability date shown in the app or deposit confirmation rather than assuming the same timeline as an in-person teller deposit.
Can a check bounce after the money is available in my account?
Yes. Funds availability and final payment of the check are different concepts. If the check is later returned unpaid or determined to be counterfeit, the bank can reverse the deposit, which may leave you responsible for money you already spent or sent elsewhere.
Bottom Line: When Can You Use a Check Deposit?
For most standard U.S. check deposits in 2026, think $275 on the next business day and the remainder generally by the second business day. Then check for the factors that can change that answer: the bank’s cutoff, deposit method, check type, account age, deposit size, account history, and any exception hold.
For a large or unusual check, your best planning tool is not a generic “two-day” or “seven-day” rule. It is the specific availability date your bank gives you for that deposit.
And keep the second question separate: Is the check unquestionably legitimate? A bank making funds available does not convert a counterfeit or unpaid check into good money. If the payer is unfamiliar, the amount is unusual, or anyone wants you to send money back, slow down before the availability screen gives you false confidence.
