

A late direct deposit usually comes down to one of five things: your employer or payroll provider sent the file later than usual, the ACH settlement date is later than you expected, a weekend or Federal Reserve holiday shifted processing, the account information is wrong, or your bank has not posted the payment yet.
But before you start calling everybody, check one thing that causes a surprising amount of panic: has your actual payday passed, or did your usual early direct deposit simply not show up? Those are not the same problem.
I get why the distinction feels academic when rent is due. You refresh the bank app every ten minutes. You start moving bills around in your head. A paycheck that normally appears Wednesday evening is suddenly missing, and by 8:30 p.m. it feels very late even if Friday is still the official payday.
That is exactly why I use a simple order of operations. First decide whether the deposit is truly late. Then use my P.A.T. Protocol™: Paystub, Administrator, Trace. The goal is to find out which side of the payment chain owns the next answer instead of making three frustrated phone calls that go nowhere.
Quick answer if your direct deposit hasn’t hit
- If the official payday has not arrived yet: your bank’s early-pay timing may simply be later than usual. Early access is not the same thing as the ACH settlement date.
- If payday has arrived: check your paystub and account details, then contact payroll or HR before your bank.
- If payroll confirms the payment was sent: ask for the effective or settlement date and the ACH trace number if they can provide it. Then contact your bank or credit union.
- If only your deposit is missing: verify your routing number, account number, recent account changes, and whether the payment was returned.
- If many coworkers are missing pay: the problem is more likely upstream with payroll, the payroll provider, or the originating bank.
On This Page
- Why Is My Direct Deposit Late? First Check Whether It Is Actually Late
- What to Do When Direct Deposit Is Late: The P.A.T. Protocol™
- 7 Reasons a Direct Deposit Can Be Late
- How Late Can a Direct Deposit Hit?
- When a Late Deposit Is More Than an ACH Timing Issue
- How to Prevent Future Direct Deposit Delays
- Late Direct Deposit FAQ
- How We Verified This
Why Is My Direct Deposit Late? First Check Whether It Is Actually Late
One of the biggest changes in banking over the last few years is that many people have started treating early direct deposit as their payday. I understand why. If your paycheck has appeared every Wednesday at 6 p.m. for a year, Wednesday at 9 p.m. feels like something broke.
Sometimes it did. But sometimes your bank was simply making money available before the payment officially settled. Nacha explains that some banks and credit unions advance their own funds before settlement, which is why an early deposit can appear one pay period and arrive later the next even when the employer’s official payday has not changed. Nacha explains how early payroll availability works.
Later than usual is not always late
If your scheduled payday is Friday and your bank often gives you access on Wednesday, a missing Wednesday deposit is an early-pay timing issue. If Friday arrives and the money still is not available, you have a payday problem. Start troubleshooting sooner if payroll tells you the deposit failed, the amount is wrong, or you see an account change you did not make.
If your usual early deposit is missing, but payday has not passed
Check first: the official pay date on your paystub or payroll portal. Your bank may simply be releasing early-pay funds later than it normally does.
If your coworkers are missing deposits too
Call first: payroll or HR. A broader pattern points toward payroll timing, the payroll provider, the originating bank, or a processing issue before the payment reaches your bank.
If your coworkers were paid, but you were not
Check first: your routing number, account number, paystub, and recent direct-deposit changes. Then ask payroll whether your specific payment was originated or returned.
If payroll says your payment was sent
Do next: ask for the effective or settlement date and ACH trace number if available. Then give that information to your bank or credit union and ask whether the ACH credit is pending, posted, rejected, or returned.
What to Do When Direct Deposit Is Late: The P.A.T. Protocol™
Over my career, the most useful thing I learned about a missing payment is that panic makes people start in the wrong place. They call the bank, the bank says it sees nothing, they call payroll, payroll says it was sent, and an hour disappears.
My sequence is P.A.T.: Paystub, Administrator, Trace. Each step gives you the information needed for the next one.
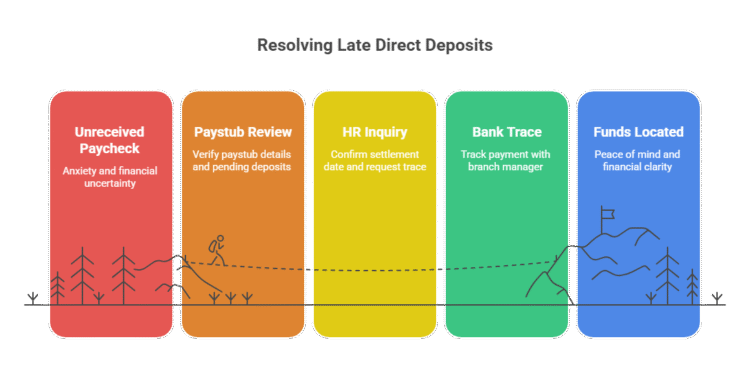
1. Paystub: Verify the Payday and the Payment
Before you call anyone, spend one minute checking the facts you can see yourself.
- Is the official pay date today, or are you waiting for an early-pay feature?
- Was a paystub generated for the expected amount?
- Is this your first paycheck or the first deposit after changing banks?
- Did you recently change your routing number, account number, split-deposit instructions, or payroll elections?
- Is the amount actually missing, or did a bonus, reimbursement, garnishment, benefit deduction, or separate payroll create a different net amount?
If you need to verify which number is the routing number versus the account number, use my guide to finding the routing and account numbers on a check. Your bank’s own app or website is the best place to confirm the numbers for your specific account.
2. Administrator: Ask Payroll the Questions That Move the Case Forward
If the deposit is truly late, your employer, payroll department, benefits administrator, or other payment originator is the best place to confirm whether your specific payment actually left their side.
What to ask payroll
Instead of only asking, “Where is my money?”, try this:
“Can you confirm that my direct deposit was originated, the effective or settlement date if you have it, whether my banking information was accepted, and the ACH trace number for my payment if it is available?”
The trace number is a 15-digit identifier assigned to an ACH entry by the originating financial institution. It gives the payment parties a much better starting point than “it should be there.” Nacha’s ACH file guide describes the trace-number field.
Also ask whether other employees are affected. That one question can save a lot of time. If everyone is missing payroll, your personal checking account is probably not the first place to investigate.
3. Trace: Call Your Bank After Payroll Confirms It Was Sent
Once payroll confirms the payment was originated, contact your bank or credit union. Give them the trace number, expected amount, sender, and settlement or effective date if you have them.
Ask a specific question: “Can you see this ACH credit as pending, posted, rejected, or returned?” If the first representative cannot research ACH entries, ask to be transferred to the team that handles ACH or deposit operations. I would not waste time hunting for a branch manager simply because the payment is electronic. The party that can see the ACH record is the party you need.
Nacha’s consumer guidance says the two parties normally in the best position to help are the organization that initiated the direct deposit and your bank or credit union. If the payment went to the wrong account or bank, contact the sender because the sender is best positioned to locate it. See Nacha’s consumer ACH guidance.
7 Reasons a Direct Deposit Can Be Late
Direct deposit is usually an ACH credit. Your employer or other sender originates the payment, its financial institution sends it into the ACH Network, an ACH Operator routes it, and your bank or credit union receives it and credits your account. Nacha lays out that payment chain here.
- Your early-pay timing changed. The official payday may be unchanged even though your bank did not advance the funds as early as it usually does.
- Payroll was submitted later than usual. A late payroll file, corrected payroll, or different effective date can move the payment even when everyone eventually gets paid correctly.
- A weekend or federal holiday changed the calendar. ACH settlement depends on banking days. Federal Reserve payment services do not follow a normal settlement schedule on weekends and Federal Reserve holidays.
- The routing or account information is wrong. A mistyped number, closed account, or recent bank change can cause the entry to reject or return instead of posting normally.
- Your bank sees the deposit but has not posted it yet. A deposit can appear as pending when the bank has notice of an incoming direct deposit but the funds are not yet available for that settlement date.
- New-account or payroll setup is still being validated. Some employers or payroll providers use account-validation methods before or around the first live payment. An ACH prenotification is one possible method, but prenotes are optional.
- The payment was returned, rejected, changed, or diverted. If payroll says the payment was sent but it never arrives, ask whether it was returned. If your direct-deposit instructions changed without your authorization, contact payroll and your bank immediately.
That sixth point is worth emphasizing because old advice often makes prenotes sound automatic. Nacha’s current developer guidance says prenotification entries are optional for all Standard Entry Class codes. They are one account-validation method, not a rule that your first paycheck must sit in “prenote purgatory.” See Nacha’s account-validation guidance.
How Late Can a Direct Deposit Hit?
There is no universal clock time for an early direct deposit. Your employer’s payroll timing, the effective date, ACH processing, and your financial institution’s early-pay policy can all matter.
New September 2026 ACH rule
As of September 18, 2026, Nacha’s rules require a receiving bank or credit union to make a non-Same Day ACH credit available for withdrawal no later than 9:00 a.m. local time on the Settlement Date, subject to a narrow exception for certain distant time zones.
That is a settlement-date rule. It does not guarantee that a bank offering early pay must make your paycheck available one or two days before the scheduled settlement date. Read the current Nacha rule.
This is also why I would not tell you that ACH simply runs at “1 a.m., 1 p.m., and 5 p.m.” and call it a day. Federal Reserve ACH processing has multiple transmission and settlement windows for Same Day and future-dated items. What matters to you is the payment’s effective or settlement date and whether your bank actually received the entry. The Federal Reserve publishes the current FedACH processing schedule.
Can a weekend or federal holiday delay direct deposit?
Yes, because ACH settlement is tied to banking days. But do not automatically assume a holiday means you will be paid late. Payroll departments often schedule around known holidays, and Nacha describes paying a payday that falls on a weekend or holiday on the preceding business day as a common industry practice. The Federal Reserve publishes its holiday calendar.
When a Late Deposit Is More Than an ACH Timing Issue
There is a big difference between “my bank did not give me my usual Wednesday early deposit” and “my employer did not pay me on the established payday.” The first can be a timing issue. The second deserves documentation and escalation.
Red flags I would not shrug off
- The regular payday has passed and payroll admits the payment was never sent.
- You received only part of the wages shown as due and payroll cannot explain the difference.
- Late payroll is becoming a repeated pattern.
- Your employer says it cannot make payroll or asks you to wait until a later pay cycle for wages already due.
- Your direct-deposit bank information was changed without your authorization.
Do not rely on a blanket statement that federal law always requires every employee to be paid on one specific recurring payday. Wage-payment timing rules vary by state and type of employment. The U.S. Department of Labor maintains a state-by-state payday requirements table. If the official payday has passed and the employer is not paying wages due, document the dates, paystubs, messages, and amounts, then contact the appropriate state labor agency or the U.S. Department of Labor Wage and Hour Division as appropriate.
If a late paycheck leaves your checking account exposed to automatic payments, my guide to bank overdraft fees and how to respond can help you manage the bank side without turning one delayed deposit into several avoidable fees.
How to Prevent Future Direct Deposit Delays
You cannot control every payroll or bank-processing problem. You can make the next one easier to diagnose.
- Use your bank’s own routing and account information. Confirm it in the app or online banking, especially after an account change.
- Turn on deposit alerts. You want a timestamp when the money actually posts, not a memory of when it usually shows up.
- Know the official payday. Treat early-pay access as helpful, not as the date every automatic bill must depend on.
- After changing banks, keep the old account open long enough to catch mistakes when practical. Confirm the first successful deposit before assuming the setup is complete.
- Keep a small timing buffer when you can. Even one or two days of essential bills in checking can turn a payroll delay from a crisis into an annoyance.
If your issue is specifically about Chime’s normal posting and early-pay timing, use my separate guide to when Chime direct deposits normally hit. This page owns the generic troubleshooting problem. The Chime page owns Chime-specific timing.
Want fewer payroll and banking surprises like this?
Financial Clarity is where I break down practical problems like a direct-deposit delay, an unexpected bank fee, or a payment that does not make sense. What matters, what to check, and what I would do next.
Late Direct Deposit FAQ
How late can a direct deposit hit?
There is no universal time for an early direct deposit. For non-Same Day ACH credits, Nacha’s rule effective September 18, 2026 requires funds to be available by 9:00 a.m. local time on the Settlement Date, subject to a narrow time-zone exception. Early-pay features can make funds available before that date, but their timing can vary.
Why am I not getting my direct deposit early?
Some banks make payroll available before the official settlement date by advancing their own funds. If your usual early deposit does not arrive, first check the official payday. A later-than-usual early deposit is not automatically a missed paycheck.
Why does my direct deposit show as pending?
Nacha notes that a bank can receive notice of an incoming direct deposit before it has actually received the funds for the future settlement date. Contact your bank or credit union to ask what the pending status means for your specific payment.
What is an ACH trace number?
An ACH trace number is a 15-digit identifier assigned by the originating financial institution to uniquely identify an ACH entry within the batch and file. If payroll confirms your deposit was sent, ask whether they can provide the trace number for your payment.
Can a first direct deposit take longer?
It can, especially if setup information is incomplete or an employer or payroll provider is validating a new account. But an ACH prenotification is optional, not a universal rule, and a first paycheck is not automatically required to be a paper check. Ask payroll how your employer handles the first payment.
Can a weekend or federal holiday delay direct deposit?
Yes, ACH settlement depends on banking days, but payroll departments commonly schedule around known weekends and holidays. Check the official pay date and ask payroll whether the holiday changed the effective or settlement date.
If Your Deposit Is Late Right Now, Do This
Check the official payday first. Then run P.A.T. in order: Paystub, Administrator, Trace. If payroll has not sent the money, your bank cannot find a payment that does not exist. If payroll confirms it was sent, the trace number and settlement information give your bank something concrete to investigate.
The goal is not to learn ACH jargon. It is to stop guessing who has your paycheck.
How We Verified This
Key timing and ACH claims were checked against current Nacha, Federal Reserve and U.S. Department of Labor guidance.
