

If your Medicare IRMAA stayed high after a divorce or the death of your spouse, you may be able to ask Social Security to use more recent income information. Both divorce or annulment and death of a spouse are recognized IRMAA life-changing events.
If you are already sorting through a death or divorce, this is exactly the kind of notice that feels backward: Medicare is pricing today from a tax return tied to a household that may no longer exist. The important question is whether SSA’s rules let you replace that old picture with a newer one.
But the event by itself is not enough. The change must actually lead to a lower IRMAA result because your modified adjusted gross income (MAGI) fell, your tax-filing status changed the threshold that applies to you, or both. That is the part many explanations skip.
One terminology point matters too: when you qualify under these rules, Social Security generally treats this as a request for a new initial determination using more recent tax information. SSA’s current POMS instructions say there is no need to appeal the prior determination if you qualify for that new initial determination, although a formal appeal and a new-initial-determination request can sometimes be filed at the same time during the appeal period.
Quick Answer
Yes, divorce and death of a spouse can qualify you to ask SSA to lower IRMAA. The practical test is not simply “Did the event happen?” It is: Did the event cause a meaningful change in MAGI or filing status that would reduce or eliminate the IRMAA Social Security calculated? If yes, gather proof of the event plus the more recent income information SSA should use.
Key Takeaways Ahead
When Divorce or a Spouse’s Death Can Lower IRMAA
Federal IRMAA rules specifically list death of a spouse and divorce or annulment as major life-changing events. SSA’s current public guidance likewise tells Medicare beneficiaries who had a qualifying life-changing event that reduced household income that they can request a lower Part B and Part D income-related adjustment.
The qualifying event opens the door. The income result decides whether walking through that door changes your premium. Under the federal rule, SSA uses a more recent tax year when the life-changing event causes a “significant” MAGI reduction—meaning the new income produces a lower or eliminated IRMAA amount.
The Two-Part Test
Part 1: Did a recognized event occur—here, divorce/annulment or death of a spouse?
Part 2: Did that event change your MAGI or filing-status threshold enough to lower the IRMAA result?
If Part 1 is yes but Part 2 is no, the life-changing-event route may not reduce the surcharge.
If you are not yet sure whether your situation fits a recognized event at all, use the IRMAA life-changing-event decision tool. This page stays focused on the two events that create the most filing-status confusion: divorce and spouse death.
Why IRMAA Can Still Reflect a Marriage That Has Ended
IRMAA normally looks backward at tax data rather than asking what your household looks like today. That is why a notice can arrive after the financial picture has changed. A tax return from the lookback year may still contain two spouses’ income even though one spouse has died or the marriage has ended.
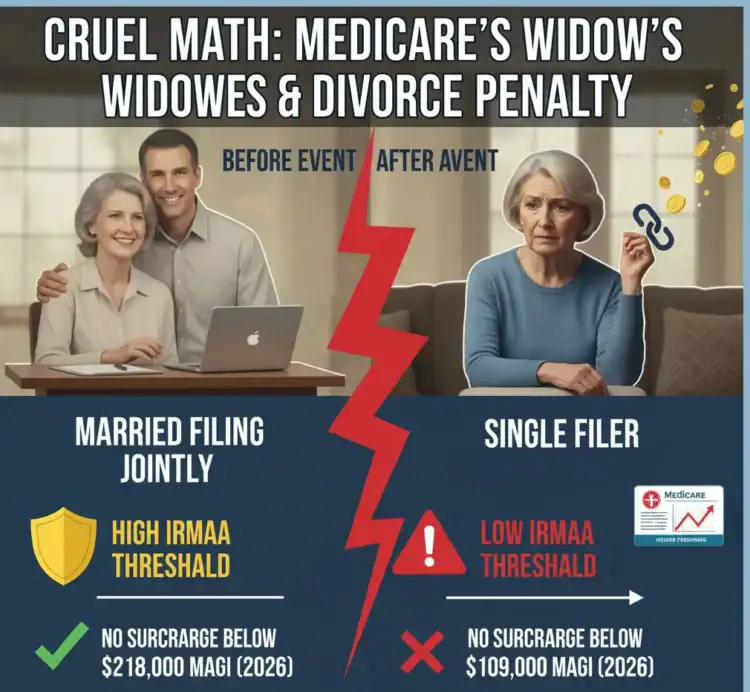
For 2026, the standard Part B premium is $202.90 per month. IRMAA begins above $109,000 of MAGI for an individual filer and above $218,000 for joint filers. Those numbers matter because a filing-status change can alter the threshold table as well as the income being measured. CMS publishes the official 2026 Part B and Part D IRMAA amounts.
Important Widow/Widower Filing-Status Nuance
Do not assume a surviving spouse automatically becomes a “Single” filer immediately. The IRS generally allows a surviving spouse to file jointly for the year of death if otherwise eligible, and some surviving spouses with a qualifying dependent child may use qualifying-surviving-spouse status for the following two years. Your actual filing status—not a rule of thumb—controls the tax return SSA is evaluating.
If you need the broader mechanics of the two-year lookback and MAGI calculation, see how Medicare calculates the IRMAA surcharge. Here, the key point is simpler: the old tax return may no longer be a fair proxy for the income and filing-status picture created by the life-changing event.
Death of a Spouse: What SSA Looks For
SSA’s operating instructions say the death of a spouse can cause both a significant MAGI reduction and a change in filing status. They also say something especially useful: the income effect can be delayed. In other words, the date of death and the tax year in which the lower-income effect fully appears do not always have to be identical.
For a spouse-death request, SSA generally needs two categories of information:
- Proof of the death if SSA does not already have acceptable evidence in its records.
- Tax information for the more recent year you want SSA to use, such as an estimate of MAGI and filing status or an eligible filed return.
SSA’s POMS instructions for death of a spouse specifically allow an estimate of MAGI and filing status for the tax year being requested. If an estimate is used before the return is filed, SSA can later reconcile it with the filed tax return.
Example: The Income Falls After the Death Year
Suppose a spouse dies late in 2025. The surviving spouse’s 2025 return may still include income and a filing status that do not yet show the full post-death financial change. In 2026, pension income, wages, or other household income may be materially lower. SSA’s own guidance recognizes that the MAGI effect of a spouse’s death can be delayed. The question is whether the later, lower-income year is one SSA may use under the life-changing-event rules—not whether the calendar flipped immediately on the date of death.
A one-time income spike after death is a different problem
This is where people understandably get tripped up. A spouse’s death can be a qualifying event, but that does not automatically make every later taxable dollar related to the death disappear from IRMAA. An inherited retirement-account distribution, asset sale, or other taxable one-time event can still be part of MAGI. The useful question is whether the spouse’s death caused a lower MAGI or filing-status result for the year you are asking SSA to use.
Divorce or Annulment: What SSA Looks For
Divorce or annulment is also an expressly recognized life-changing event because it can change both tax filing status and MAGI. SSA’s internal instructions say the effect on MAGI may be delayed here too.
The divorce request applies only to the person who files it
This is an easy operational detail to miss: SSA does not automatically extend one former spouse’s new IRMAA determination to the other ex-spouse. SSA’s POMS says reports of divorce or annulment apply only to the reporting spouse. If both former spouses are Medicare beneficiaries and both are affected, each person is responsible for contacting SSA.
For divorce or annulment, SSA needs proof that the marriage ended if it is not already established in its records, plus the MAGI and filing-status information for the tax year you are asking it to use. SSA’s divorce/annulment POMS section lays out that evidence requirement and separate-spouse treatment.
Example: The Joint Return Is No Longer the Right Picture
Suppose a 2026 IRMAA notice was based on a 2024 joint return that included substantial income from both spouses. The couple divorces, and the beneficiary’s own more recent MAGI is substantially lower. The divorce is the qualifying event; the lower individual MAGI and changed filing status are what determine whether using the more recent year actually reduces IRMAA.
The Income-Drop Test Most People Miss
The most important sentence in the federal rule is not the list of life-changing events. It is the requirement that the event produce a reduction that actually decreases or eliminates IRMAA. 20 C.F.R. §418.1201 ties the use of a more recent tax year to both a qualifying event and a significant MAGI reduction.
That creates three different outcomes:
| What changed? | What it may mean | Next question |
|---|---|---|
| Qualifying event + lower MAGI | Strong fit for a life-changing-event request if the lower MAGI reduces IRMAA. | What more recent year and evidence should SSA use? |
| Qualifying event + filing-status change | May change which IRMAA threshold table applies, but the resulting MAGI/threshold combination still has to lower IRMAA. | What is your actual tax filing status for the year at issue? |
| Qualifying event, but income remains in the same IRMAA tier | The event can be real while the requested recalculation produces little or no premium reduction. | Does the newer MAGI actually cross to a lower IRMAA tier? |
This is why I would not start with “How do I fill out SSA-44?” Start one step earlier: What number do I want SSA to use instead, and does that number actually change the surcharge? That one question prevents a lot of wasted motion.
Get IRMAA Decisions Like This Before the Deadline Matters
Once you see that a life-changing event is only half the test, the next job is checking the income year, filing status, evidence, and timing before you submit anything.
- IRMAA appeal and redetermination rules translated into plain English
- Medicare-income mistakes that can change what you pay
- Practical checks for SSA forms, thresholds, and life-changing events
Get IRMAA decision checks and Medicare-income updates in your inbox.
What to Gather Before You Ask SSA to Recalculate IRMAA
You do not need a second giant SSA-44 tutorial here. You need the small packet of facts that proves this specialist question.
- Your IRMAA notice so you know the premium year and tax information SSA used.
- Proof of the life-changing event: proof of death or proof that the marriage ended, if SSA does not already have acceptable evidence.
- The more recent MAGI information you want SSA to use, including your expected or actual filing status for that tax year.
- Support for the income estimate or return when required. SSA’s current POMS says an estimate may be used in qualifying circumstances if the most recent return has not yet been filed.
The federal evidence rules require both evidence of the event and evidence supporting the more recent MAGI. SSA’s regulation describes the event evidence, while its current operating instructions explain the tax-information side.
When you are ready for the procedural mechanics—what goes in each SSA-44 section, how to submit it, and what to do if SSA does not accept the request—use the dedicated SSA-44 IRMAA appeal and redetermination guide. That is the procedure owner. This page’s job is making sure divorce or spouse death actually fits before you get lost in form instructions.
Can you submit SSA-44 online?
Yes. SSA’s current public page says eligible beneficiaries can sign in and submit the SSA-44 process online; fax, mail, and an appointment are also available. Use SSA’s current “Request to lower IRMAA” page for the live submission options rather than relying on an old article screenshot or mailing instruction.
Before You File: One Last Reality Check
When a marriage ends or a spouse dies, it is natural to look at the old joint return and think, “That is not my financial life anymore.” Sometimes that is exactly the reason SSA should use newer information. Sometimes the newer income is still high enough to leave you in an IRMAA tier. And sometimes a one-time taxable event is the real reason the surcharge remains high even though the household changed.
So before submitting anything, run the simplest version of the case: event → new tax year → new MAGI and filing status → new IRMAA tier. If you cannot complete that chain on paper, the form will not solve the ambiguity for you.
The form is paperwork. The case is the chain.
If you need help determining what belongs in MAGI before you estimate the new number, use my guide to what income counts toward IRMAA MAGI.
IRMAA After Divorce or Death FAQs
Can the death of my spouse qualify me to lower IRMAA?
Yes, death of a spouse is a recognized IRMAA life-changing event. But SSA must also be able to use a more recent MAGI and filing-status picture that actually reduces or eliminates your IRMAA amount.
Can divorce or annulment qualify for an IRMAA reduction?
Yes. Divorce or annulment is a recognized life-changing event. SSA looks at whether the event changed your MAGI or filing status enough for a more recent tax year to produce a lower IRMAA determination.
What proof do I need after divorce or the death of a spouse?
SSA generally needs proof of the qualifying event if it is not already established in its records, plus tax information for the more recent year you want SSA to use. The exact evidence depends on the event and whether you are using an estimate or a filed return.
Is there a strict two-year limit after my spouse dies?
Do not rely on a simple ‘the death must have happened within two years’ rule. SSA’s POMS specifically says the MAGI effect of a spouse’s death can be delayed. The controlling question is whether the qualifying event caused the lower MAGI or filing-status result for the more recent tax year SSA may use under the rules.
If both ex-spouses pay IRMAA, does one divorce request cover both people?
No. SSA’s operating instructions say a divorce or annulment report applies only to the beneficiary who reports it. If both former spouses are affected Medicare beneficiaries, each person is responsible for contacting SSA.
Sources
- Social Security Administration — Request to lower an Income-Related Monthly Adjustment Amount
- SSA POMS HI 01120.001 — New Initial Determinations Using Beneficiary-Provided Information
- SSA POMS HI 01120.010 — Death of Spouse
- SSA POMS HI 01120.020 — Divorce or Annulment
- 20 C.F.R. §418.1201 — Use of a More Recent Tax Year
- 20 C.F.R. §418.1205 — Major Life-Changing Events
- 20 C.F.R. §418.1255 — Life-Changing-Event Evidence
- Centers for Medicare & Medicaid Services — 2026 Medicare Parts A & B Premiums and IRMAA Amounts
- Internal Revenue Service — Filing Status
