

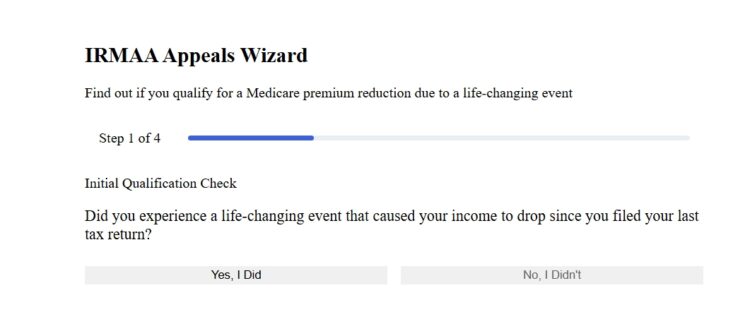
This tool helps you answer a narrower question than “Can I appeal IRMAA?” It asks whether your situation appears to fit Social Security’s life-changing-event route for using more recent income information, and then points you to the next thing to verify.
That distinction matters because not every unfair-looking IRMAA bill is an SSA-44 case. Divorce, death of a spouse, retirement and certain other events can fit the life-changing-event rules. An amended tax return, corrected IRS data or a one-time income spike may require a different path.
SSA recognizes eight specific life-changing events for this IRMAA route. A recognized event is only the first gate. The second is whether the event lowered your modified adjusted gross income (MAGI), changed your tax filing status in a way that changes the applicable IRMAA threshold, or both. The router below helps you sort those two questions without pretending it can approve an SSA request.
Use the IRMAA Life-Changing-Event Appeal Router
The router is educational decision support. It does not calculate your final premium, certify that you qualify, or replace Social Security’s determination. Its job is to identify the most plausible lane and the missing fact you should verify next.
Question 1 of 3
Do not stop at “Did something big happen to me?” Ask two questions: “Is it one of SSA’s recognized events?” and “What did it actually change about my MAGI or filing status?” If you cannot answer the second question yet, that is the next piece of work.
Which Eight Life-Changing Events Does SSA Recognize?
SSA’s current policy lists eight life-changing events for this type of IRMAA new initial determination:
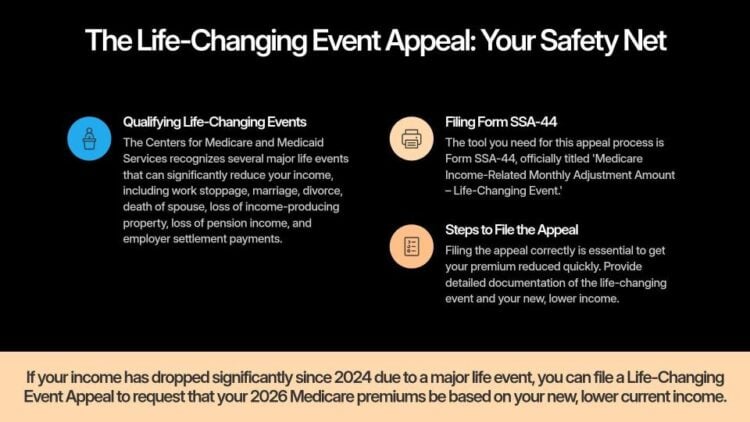
- Death of a spouse
- Marriage
- Divorce or annulment
- Work reduction
- Work stoppage
- Loss of income-producing property
- Loss or reduction of employer pension income
- Receipt of a qualifying employer settlement payment
SSA’s current IRMAA policy lists those categories. The details matter. For example, a voluntary sale of income-producing property is not automatically the “loss of income-producing property” event, and ordinary annuity income disappearing is not a separate ninth event.
“My income went down” is not itself one of the eight events. A beneficiary can have a very real drop in income without fitting SSA-44’s life-changing-event lane. That does not prove there is no IRMAA remedy; it means you should identify the correct reason SSA’s original determination should change.
If this tool helped you separate the event from the income effect, my weekly email does the same thing with Medicare and retirement-income decisions: find the one rule or timing detail that changes the answer before you act.
- IRMAA income and life-event rules worth checking early
- Medicare timing traps hidden inside otherwise sensible money moves
- Practical questions to take to SSA, your tax professional or your planner
Why a Recognized Event Is Only the First Gate
A recognized event gives SSA a reason to consider more recent information. It does not guarantee a lower premium.
Under SSA policy, the important financial change can be a significant reduction in MAGI, a tax-filing-status change that changes the threshold table, or both. If the newer income still lands in the same IRMAA tier, your event may be valid while the dollar result changes little or not at all.
The event opens the lane. The newer income and filing status determine where that lane leads.
That is why this router asks about both. A checkbox-only “eligibility quiz” would give false confidence.
What Evidence Should You Expect to Need?
Think in two buckets. SSA generally needs evidence of the life-changing event and evidence of the more recent MAGI you want it to use.
- Event evidence: documentation appropriate to the event, such as proof of death, divorce/annulment, work reduction or stoppage, a qualifying pension loss, property loss, or employer settlement.
- Income evidence: a more recent filed federal tax return when available, or other evidence supporting a reasonable MAGI estimate when the return has not yet been filed.
The current Form SSA-44 instructions say the request needs both life-event evidence and more recent income information. That is enough detail for this routing page. The line-by-line form mechanics belong in the procedural guide.
What If Your Problem Is Not a Life-Changing Event?
This is one of the most important results the tool can give you: “SSA-44 may be the wrong lane.”
SSA separately recognizes situations involving an amended tax return, corrected IRS information, or SSA using older tax data than it should have used. A voluntary capital gain, Roth conversion or other one-time income spike usually does not become a life-changing event simply because it raised IRMAA.
If a one-time income spike is the real issue, use my IRMAA one-time income spike guide. If the IRS data itself was amended or wrong, start with Social Security’s current IRMAA page rather than forcing the facts into a life-event checkbox.
Where Should the Tool Send You Next?
The tool deliberately routes instead of teaching every procedure on this page:
- Divorce or death of a spouse: use the divorce/death specialist guide for timing, MAGI and evidence detail.
- A recognized life-changing event with a likely income effect: use the SSA-44 form guide for the filing procedure.
- Not sure what counts in MAGI: use the IRMAA MAGI guide.
- No recognized event: do not assume “no appeal.” Verify whether your issue is amended/corrected tax data, older IRS information, or an income spike that requires planning rather than SSA-44.
The Bottom Line
The best IRMAA appeal tool should not tell everyone with a sad story or lower income that they “qualify.” It should narrow the problem.
Start with the event. Then test the income or filing-status consequence. Then gather the evidence. Only after those three pieces line up does the SSA-44 route become the obvious procedural next step.
IRMAA Life-Changing-Event Tool FAQ
Does selecting one of the eight events mean I qualify?
No. It means your event appears to fit a recognized category. SSA still evaluates the event evidence, the more recent MAGI or filing-status information, and the effect on your IRMAA determination.
Is SSA-44 the only way to ask SSA to change IRMAA?
No. SSA policy includes other new-initial-determination situations, including amended tax returns, corrected IRS data and cases where older tax information was used. SSA-44 is the life-changing-event route.
Can the tool calculate how much my IRMAA will fall?
No. That would require the exact premium year, filing status and MAGI used for the new determination. This page is a routing tool, not an IRMAA premium calculator.
Why does the tool ask whether my MAGI or filing status changed?
Because the recognized event by itself does not set the new premium. SSA’s current policy looks to whether the event produced a significant MAGI reduction or a filing-status change that changes the threshold table it should use.
