
Does Social Security count toward IRMAA? Yes, but not in the way many retirees assume. IRMAA uses modified adjusted gross income, and only the taxable portion of your Social Security is already inside AGI. The nontaxable portion is not separately added back for IRMAA.
The catch is that another income decision can change how much of your Social Security becomes taxable in the first place. A traditional IRA withdrawal, Roth conversion, capital gain, pension payment, or other income can increase your Social Security combined income. That can make more benefits taxable, which can increase AGI, which can then increase the MAGI Medicare uses for IRMAA.
That is the real Social Security and IRMAA tax trap. Two different calculations can react to the same dollar.
Michael’s Take
I would not ask only, “Will this withdrawal raise my tax bracket?” In retirement, I also want to know whether that same dollar makes more Social Security taxable and whether the higher AGI could later move Medicare into another IRMAA tier.
Show the quick answer
- What counts for IRMAA: IRMAA MAGI generally starts with AGI and adds tax-exempt interest. Only the taxable portion of Social Security is already included in AGI.
- What creates the tax torpedo: Extra income can make more Social Security taxable, so one additional dollar can cause more than one dollar to become subject to income tax.
- 2026 IRMAA: For 2026 Medicare premiums, the first IRMAA threshold is above $109,000 for an individual return and above $218,000 for a joint return, generally using 2024 MAGI.
- Planning year matters: Income you create in 2026 would ordinarily affect 2028 IRMAA, not your 2026 premium. The official 2028 thresholds are not available yet.
- Useful levers: QCDs, qualified Roth withdrawals, careful Roth-conversion timing, income smoothing, and eligible SSA-44 appeals can help in the right situation.
On This Page
- Does Social Security Count Toward IRMAA?
- How Social Security Taxation Works Before IRMAA Enters the Picture
- How One IRA Withdrawal Can Raise Social Security Taxes and IRMAA MAGI
- 2026 IRMAA Thresholds and the Two-Year Lookback
- The Widow’s Penalty Can Make Both Problems Worse
- 4 Ways to Manage the Social Security and IRMAA Interaction
- What to Do in Late 2026 Before You Create More Taxable Income
- Choose the Next Calculation
- Social Security and IRMAA Questions Retirees Keep Asking
- The Bottom Line
- How We Verified This
Does Social Security Count Toward IRMAA?
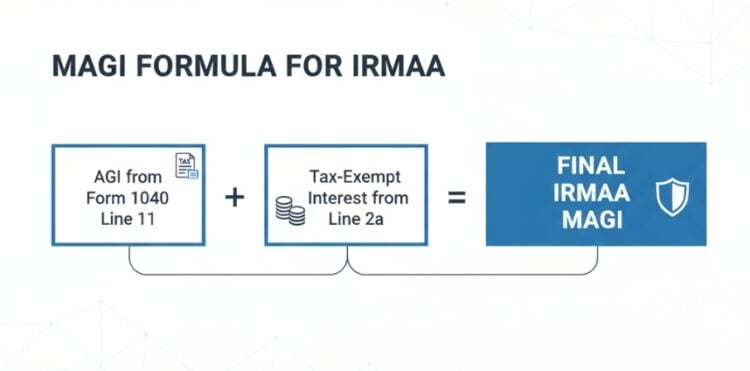
Only the taxable portion of Social Security reaches IRMAA through AGI. For Medicare’s income-related premium rules, Social Security generally defines MAGI as your adjusted gross income plus tax-exempt interest. The nontaxable part of your Social Security benefit is not added back a second time.
This is one of the most common points of confusion I see because “MAGI” does not mean the same thing in every part of the tax code. For IRMAA, start with the number on Form 1040 line 11, then add tax-exempt interest such as municipal-bond interest.
If you are unsure whether an IRA withdrawal, Roth conversion, capital gain, pension, municipal-bond interest, or Social Security benefit belongs in the calculation, use the IRMAA income checker instead of guessing from whether the cash feels taxable.
How Social Security Taxation Works Before IRMAA Enters the Picture
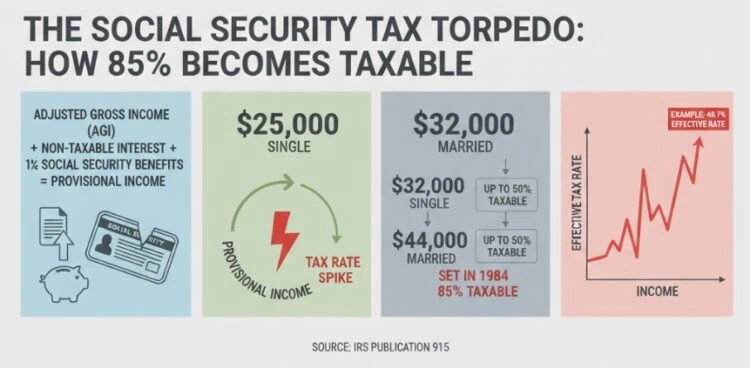
The Social Security tax calculation uses a different measure commonly called combined income. IRS Publication 915 starts with income other than Social Security, adds tax-exempt interest and certain adjustments, then adds one-half of your Social Security benefits.
The important correction is this: crossing $34,000 if single or $44,000 if married filing jointly does not instantly make 85% of your benefits taxable. Above those second thresholds, up to 85% of benefits may eventually become taxable under the formula.
| Filing status | Base amount | Second threshold |
|---|---|---|
| Single, head of household, qualifying surviving spouse | $25,000 | $34,000 |
| Married filing jointly | $32,000 | $44,000 |
Married filing separately is different. If you lived apart from your spouse for the entire year, the $25,000 base amount can apply. If you lived with your spouse at any time during the year, the base amount is generally $0. Use the IRS worksheet for that filing status rather than the simplified table above.
Between the base amount and the second threshold, up to 50% of benefits can be taxable. Above the second threshold, the formula can move toward an 85% maximum. IRS Publication 915 contains the controlling worksheets and exceptions.
Why Your Effective Marginal Tax Rate Can Jump
Inside part of the tax-torpedo range, an extra $1 of ordinary income can cause as much as another $0.85 of Social Security to become taxable. If that entire $1.85 is taxed at a 22% marginal rate, the federal tax attributable to that extra dollar can be about 40.7 cents.
That 40.7% is an example, not a universal retirement tax rate. Your actual result depends on where you are in the Social Security worksheet, your ordinary-income bracket, capital gains, deductions, filing status, and other tax items. A 12% bracket taxpayer in the same 85% inclusion zone would have a different result.
Myth: “Once I cross $44,000, 85% of Social Security is taxed.”
No. For a married couple filing jointly, $44,000 is the second combined-income threshold. Above it, the formula can make up to 85% of benefits taxable. It does not switch the full 85% on at once.
How One IRA Withdrawal Can Raise Social Security Taxes and IRMAA MAGI
This is where the two systems meet. They use different formulas, but a taxable retirement-income decision can feed both of them.
- You take a taxable distribution from a traditional IRA or another source of ordinary income.
- That income can raise your Social Security combined income.
- A higher combined-income result can make more of your Social Security taxable.
- The taxable Social Security amount is included in AGI.
- IRMAA MAGI generally starts with that AGI and then adds tax-exempt interest.
- If the resulting MAGI crosses an IRMAA tier, future Medicare Part B and Part D costs can rise.
This is why looking at a withdrawal in isolation can be misleading. The IRA distribution itself may be only the first tax effect.
Illustrative Example
Suppose a retired couple is already inside the Social Security inclusion range and is also close to an IRMAA threshold. A taxable IRA withdrawal could increase ordinary income, make additional Social Security taxable, and leave the final AGI higher than the withdrawal alone. If that higher MAGI crosses an IRMAA tier, the Medicare consequence arrives later because IRMAA generally uses tax data from two years earlier.
2026 IRMAA Thresholds and the Two-Year Lookback
For 2026 Medicare premiums, Social Security generally uses your 2024 tax return. CMS set the first 2026 IRMAA threshold above $109,000 for an individual return and above $218,000 for a joint return.
| Tax return status | No IRMAA through 2024 MAGI of |
|---|---|
| Individual return | $109,000 |
| Married filing jointly | $218,000 |
At the first higher tier, the 2026 Part B premium rises from $202.90 to $284.10 per month. Part D IRMAA adds $14.50 per month on top of the person’s regular Part D plan premium. CMS publishes the full 2026 Medicare premium and IRMAA table.
If you want all of the tiers rather than just the starting line, use the 2026 IRMAA brackets guide.
The Planning Year Is Usually More Important Than the Premium Year
As of September 2026, your 2026 Medicare premium is already tied generally to 2024 income. A Roth conversion, large capital gain, or IRA withdrawal you create in 2026 would ordinarily be relevant to 2028 IRMAA if you are subject to IRMAA then.
The official 2028 IRMAA thresholds do not exist yet. That means there is no honest exact “safe 2026 MAGI” for 2028. You can model a planning range and leave a buffer, but do not pretend a future CMS threshold has already been announced.
Late-2026 Planning Note
The official 2027 Medicare premium and IRMAA figures have not yet been released as of September 22, 2026. This page will continue using confirmed 2026 figures for current-year examples and will separate them from future-year planning assumptions.
The Widow’s Penalty Can Make Both Problems Worse
A surviving spouse can face a painful squeeze. Household income often does not fall by half when one spouse dies, but tax and Medicare thresholds can eventually be based on a single return instead of a joint return.
There is an important qualification the old version of this article missed. The year a spouse dies is generally the last year a surviving spouse can file a joint return with the deceased spouse if otherwise eligible. For the next two years, qualifying surviving spouse status is available only if the survivor meets additional requirements, including having a qualifying dependent child. It is not an automatic two-year extension of married filing jointly for every widow or widower.
The IRS explains those requirements in Publication 501. For Medicare specifically, death of a spouse can also be a qualifying life-changing event for an IRMAA reconsideration when the event reduces household income.
If this is the issue you are dealing with, use the dedicated guide to appealing IRMAA after the death of a spouse.
4 Ways to Manage the Social Security and IRMAA Interaction
1. Use QCDs When Charitable Giving Already Fits Your Plan
If you are at least 70½ and already give to charity, a qualified charitable distribution can be especially useful because an eligible QCD goes directly from the IRA to a qualifying charity and is excluded from gross income to the extent the rules are satisfied. It can also count toward an RMD.
For 2026, the annual QCD exclusion limit is $111,000. Because an excludable QCD does not enter AGI, it can help with both Social Security taxation and IRMAA in a way that an ordinary taxable IRA withdrawal followed by a charitable gift may not.
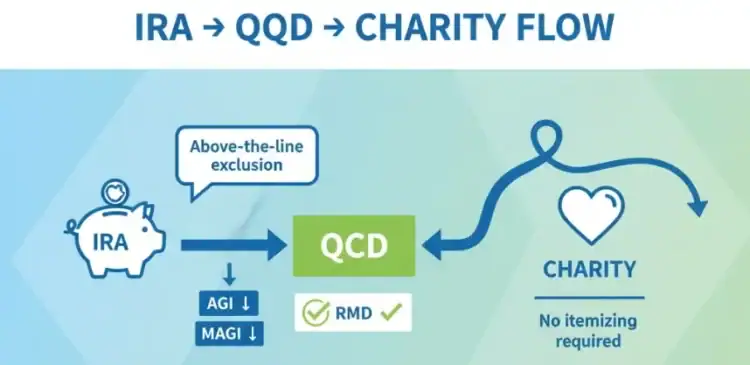
The reporting can be easy to miss. Your Form 1099-R does not necessarily identify the QCD for you, so the tax return must report the distribution correctly. See the full QCD and IRMAA guide before treating a charitable distribution as automatic tax savings.
2. Distinguish Roth Withdrawals From Roth Conversions
A qualified Roth IRA distribution generally is not included in gross income, so it generally does not increase AGI or IRMAA MAGI. That can make Roth money useful for a large purchase in retirement when the alternative is creating more taxable income.
A Roth conversion is the opposite in the year you do it. The taxable conversion amount increases income and can affect Social Security taxation and future IRMAA. The long-term benefit may still justify the short-term cost, which is why I would model the tradeoff instead of reflexively trying to avoid IRMAA at all costs. See when paying IRMAA for a Roth conversion can still make sense.
3. Avoid Stacking Every Income Event Into the Same Year
Capital gains, Roth conversions, taxable IRA withdrawals, business income, and other one-time events can pile onto the same tax return. Sometimes that is unavoidable. Sometimes the timing can be spread, delayed, accelerated, or coordinated.
The practical rule is simple. Before a large year-end transaction, model the whole return, not just the transaction’s headline tax rate. One mistake I saw repeatedly in retirement planning was treating the tax rate on a withdrawal or gain as the entire cost while missing what that income could do to Social Security taxation or a future Medicare tier.
4. Use SSA-44 When a Real Life-Changing Event Makes Old Income Misleading
If Social Security is using older income that no longer reflects your situation because of a qualifying life-changing event, you may be able to request a new IRMAA determination. Work stoppage, work reduction, death of a spouse, divorce, loss of pension income, and certain other events can qualify.
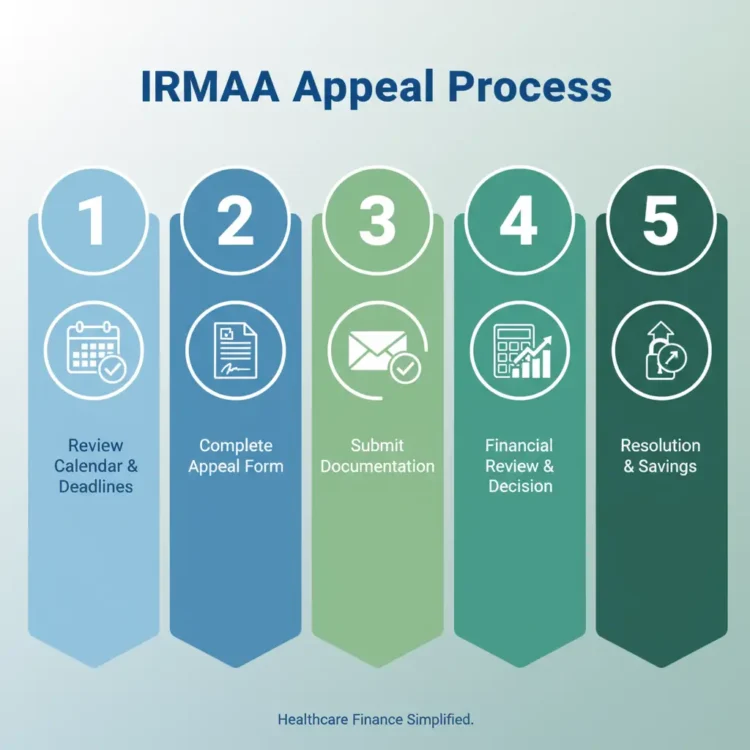
The evidence rules depend on the event. For a work stoppage, SSA’s current procedures can accept the beneficiary’s signed statement under penalty of perjury and may also document employer evidence when provided. Do not assume one specific employer document is always mandatory. Start with the current SSA IRMAA reconsideration instructions.
Don’t let a December withdrawal become a Medicare surprise two years later
One clear financial move each week for retirement tax, Social Security, and Medicare decisions.
- → New IRMAA numbers when they change
- → Roth and RMD planning traps
- → Plain-English rule updates
Get Financial Clarity before the next year-end planning window closes.
📬 No spam. Unsubscribe anytime.
What to Do in Late 2026 Before You Create More Taxable Income
If you are making a Roth conversion, realizing a gain, taking extra IRA money, or planning a large charitable gift before December 31, use this order.
- Estimate your full-year 2026 AGI. Include the taxable portion of Social Security rather than all of the benefit.
- Calculate Social Security combined income separately. Do not substitute IRMAA MAGI for the Social Security worksheet.
- Add tax-exempt interest for IRMAA. Municipal-bond interest can matter even when it is excluded from ordinary taxable income.
- Remember the two-year lag. A 2026 decision generally belongs in your 2028 IRMAA planning, not your 2026 premium calculation.
- Use a buffer for future thresholds. The official 2028 IRMAA brackets are not known yet.
- Do not let IRMAA become the only goal. Paying a temporary surcharge can sometimes be cheaper than creating a larger lifetime tax problem just to stay below a Medicare threshold.
That last point is worth remembering. IRMAA is a cost to model, not a commandment. The better question is what the transaction does to your total tax and retirement plan over time. The nuanced implications of NUA strategies and IRMAA can significantly influence how you approach your financial planning. Understanding these factors enables you to make more informed decisions about your investments and overall strategy.
