

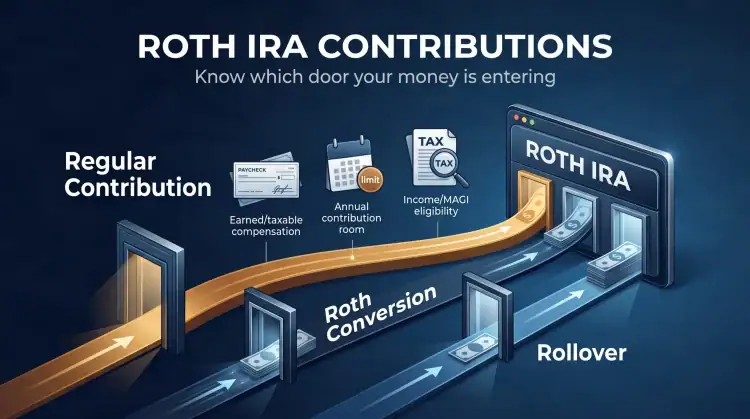
A Roth IRA contribution is new money put directly into a Roth IRA for a specific tax year. For 2026, the IRS says the combined annual limit for traditional and Roth IRA contributions is $7,500, or $8,600 if you’re age 50 or older. Your allowable Roth contribution can be reduced further by taxable-compensation rules and modified adjusted gross income (MAGI), with special rules available for qualifying spousal IRAs.
That sounds simple until three different money movements get called “putting money in a Roth”: a regular contribution, a conversion, and a rollover. They are not interchangeable. The IRS applies different rules to each, and mixing them up is where a lot of Roth confusion starts.
Quick Answer: 2026 Roth IRA Contributions
- Annual IRA limit: $7,500, or $8,600 if you’re age 50 or older.
- Compensation limit: You generally cannot contribute more than your taxable compensation for the year, subject to the spousal IRA rules.
- Roth income test: Your MAGI can reduce or eliminate your ability to make a regular direct Roth IRA contribution.
- Shared limit: The annual IRA limit is shared across your traditional and Roth IRAs; it is not a separate limit for each account.
- 401(k) participation: Having a 401(k) at work does not by itself prevent a Roth IRA contribution.
Key Takeaways Ahead
What Is a Roth IRA Contribution?
A regular Roth IRA contribution is money you contribute directly to a Roth IRA for a specific tax year. You do not receive an income-tax deduction for the contribution. In exchange, Roth IRA earnings can grow tax-free, and qualified distributions can be tax-free when the withdrawal rules are satisfied.
The contribution itself is only the funding step. Putting cash into the Roth IRA does not automatically invest it. Over nearly 30 years as a financial planner, I saw versions of this mistake more than once: the contribution reached the account, but the money sat in the settlement or cash position because nobody completed the second step and chose an investment.
Michael’s Roth Rule
Contributing and investing are two separate actions. After funding a Roth IRA, confirm where the cash actually landed and whether it is invested according to your plan. A tax-free wrapper cannot do the investing for you.
What Is a Roth Contributory IRA?
A Roth contributory IRA is not a separate federal tax category from a Roth IRA. It is a label some financial institutions use to distinguish how the Roth account is funded. For example, Schwab’s IRA application separates “Roth Contributory” from “Roth Conversion” when identifying the Roth IRA funding path.
The word contributory helps distinguish where the money came from. A regular contribution is new money you put into the account for a tax year. A conversion moves money from a traditional retirement account into Roth status. A rollover generally moves eligible retirement money from one account or plan to another. The Roth account may look similar after the money arrives, but the path the money took determines which rules apply.
So if a brokerage labels your account “Roth Contributory IRA,” don’t assume you accidentally opened a different Roth product. First ask what the institution means by the label and confirm the account’s funding history.
Can You Contribute to a Roth IRA in 2026? Use This 3-Gate Test
Before making a regular 2026 Roth IRA contribution, I would check three gates in this order: compensation, contribution room, then Roth income eligibility. Passing one gate does not automatically mean you pass the others.
Gate 1: Do You Have Enough Taxable Compensation?
The IRS contribution-limit rules say your total annual contributions to traditional and Roth IRAs generally cannot exceed the smaller of the annual IRA dollar limit or your taxable compensation for the year. A special spousal IRA rule may allow a married couple filing jointly to fund an IRA for a spouse with little or no compensation when the joint compensation requirement is met.
This is why “I have cash available” is not the same question as “I am eligible to contribute.” Savings, investment proceeds, gifts, or money already sitting in a bank account do not by themselves create IRA contribution room.
Gate 2: How Much IRA Contribution Room Do You Have?
For 2026, the IRS increased the IRA contribution limit to $7,500. If you’re age 50 or older, the catch-up contribution is $1,100, making the total $8,600. Those limits are shared across your traditional and Roth IRAs.

If you split contributions between account types, keep a running total. For example, a 45-year-old who puts $3,000 into a traditional IRA does not get another $7,500 of regular Roth IRA contribution room for 2026. The combined regular IRA contribution limit is still $7,500, assuming compensation and Roth eligibility do not reduce it further.
For the detailed annual-limit rules and catch-up amounts, use my Roth IRA contribution limits guide.
Gate 3: Does Your MAGI Allow a Direct Roth Contribution?
Even if you have enough compensation and unused IRA contribution room, your MAGI can reduce or eliminate your ability to contribute directly to a Roth IRA.
For 2026, the IRS Roth IRA phase-out ranges are $153,000 to $168,000 for single filers and heads of household, and $242,000 to $252,000 for married couples filing jointly. For a married person filing separately who lived with a spouse during the year, the range remains $0 to $10,000.
2026 Roth IRA Income Limits
Use your 2026 Roth IRA modified adjusted gross income and tax-filing status to determine whether you may make the full direct contribution, a reduced contribution, or no direct contribution.
| Tax-filing status | Full contribution | Reduced contribution | No direct contribution |
|---|---|---|---|
| Single or head of household | Less than $153,000 | $153,000 to less than $168,000 | $168,000 or more |
| Married filing jointly or qualifying surviving spouse | Less than $242,000 | $242,000 to less than $252,000 | $252,000 or more |
| Married filing separately You did not live with your spouse at any time during 2026. | Less than $153,000 | $153,000 to less than $168,000 | $168,000 or more |
| Married filing separately You lived with your spouse at any time during 2026. | $0 | More than $0 to less than $10,000 | $10,000 or more |
The contribution limit is shared
The $7,500 or $8,600 limit generally applies to your combined traditional IRA and Roth IRA contributions for 2026. It is not a separate limit for each account.
Taxable compensation can lower it
Your maximum IRA contribution is generally limited to the smaller of the annual IRA limit or your taxable compensation for the year, subject to the spousal IRA rules.
MAGI is not simply salary
Roth IRA MAGI starts with adjusted gross income and applies IRA-specific modifications. It may differ from gross income, taxable income, or the amount shown on a pay stub.
The phase-out requires a calculation
Income inside the reduced-contribution range does not automatically permit one fixed amount. Use the applicable IRS worksheet to calculate the reduced limit.
This table addresses regular direct Roth IRA contributions for the 2026 tax year. It does not determine your exact MAGI, taxable compensation, reduced contribution, eligibility for a spousal IRA, or the tax result of a Roth conversion.
Roth IRA contributions are not deductible. Eligibility to deduct a traditional IRA contribution uses different income ranges and workplace-plan rules.
This information provides general financial education, not individualized tax, legal, accounting, investment, or retirement-planning advice. Verify your calculation using current IRS instructions or a qualified tax professional.
If your income is inside a phase-out range, don’t guess at a partial amount. Use the IRS worksheet or the detailed 2026 Roth IRA income-limits guide. That page owns the MAGI calculation and phase-out details; this page is the contribution roadmap.
Before You Fund the Roth, Check the Rule That Changes the Answer
Roth mistakes usually aren’t caused by one impossible rule. They’re caused by applying the right rule to the wrong kind of transaction. I send one practical retirement-tax check each week to help you catch those distinctions before money moves.
Roth IRA Contribution vs. Conversion vs. Rollover: Three Different Doors
This is the distinction I want readers to remember. “Money went into my Roth” is not enough information to know which rule applies.
| Money movement | What it means | Uses annual IRA contribution limit? | Direct Roth income limit applies? |
|---|---|---|---|
| Regular Roth contribution | New money contributed for a specific tax year | Yes | Yes |
| Roth conversion | Pre-tax or nondeductible traditional retirement money is converted to Roth status | No | No direct-contribution MAGI limit, but taxes and other conversion rules can apply |
| Eligible rollover/transfer | Retirement assets move between eligible accounts or plans | No | Not the regular-contribution income test |
If your income is too high for a regular direct Roth contribution, that does not automatically tell you whether a Roth conversion is appropriate. Conversions have a separate tax and planning framework. Use the Roth IRA conversions guide before treating a “backdoor Roth” as a simple workaround.
Can You Contribute to a Roth IRA If You Have a 401(k)?
Yes. Participating in a 401(k) at work does not by itself block a Roth IRA contribution. The 401(k) employee-deferral limit and the IRA contribution limit are separate limits.
You still have to pass the Roth IRA’s own compensation and MAGI rules. And whether your next dollar belongs in the 401(k) or Roth IRA is a planning decision, especially when an employer match is available. For that comparison, see how a Roth IRA and 401(k) can work together.
When Is the Roth IRA Contribution Deadline?
Under IRS Publication 590-A, you can generally make a Roth IRA contribution for a tax year up to the due date of that year’s federal income-tax return, not including extensions. That means a 2026 contribution can generally be made during 2026 or by the ordinary 2027 filing deadline.
The practical trap is January through tax day, when custodians may let you choose between the prior tax year and the current one. Double-check the year before you submit the transfer. For the calendar details, see the IRA contribution deadline guide.
Four Roth IRA Contribution Mistakes I’d Check Before Funding
- Counting available cash instead of taxable compensation. Having money to transfer does not necessarily mean you have IRA contribution eligibility.
- Forgetting the traditional-and-Roth IRA limit is shared. Multiple accounts do not multiply the annual regular-contribution limit.
- Funding before you know your likely MAGI. A late-year bonus, stock compensation, business income, or filing-status change can turn a contribution that looked fine in January into an excess contribution later.
- Stopping after the deposit. Confirm the contribution was actually invested rather than sitting indefinitely in cash.
That third mistake is easy to miss because your final MAGI may not be obvious when you make the contribution. The lesson isn’t “wait until April to invest.” It’s know which inputs are uncertain and have a correction plan if your year changes.
What If You Contributed Too Much to a Roth IRA?
Act promptly. The IRS imposes a 6% excise tax on excess IRA contributions for each year an excess remains in the IRA, subject to the statutory limit on that tax.
Current IRS guidance generally allows an excess contribution to be treated as though it was not contributed when the excess and the required earnings are withdrawn by the tax-return due date, including extensions. The exact correction can depend on the tax year, whether the deadline has passed, your other IRA activity, and whether recharacterization or another correction method is available.
Don’t “Fix” an Excess With a Normal Withdrawal
If you discover an excess, contact the IRA custodian and tell them you’re correcting an excess contribution. The reporting and earnings calculation matter. A normal distribution is not automatically the same transaction.
For the controlling rules, see IRS Publication 590-A. If the amounts are material or more than one tax year is involved, this is a good place to involve a tax professional rather than improvise from an online example.
Michael’s 60-Second Roth IRA Contribution Check
- Compensation: Do I have enough taxable compensation for the contribution?
- IRA total: How much have I already contributed to all traditional and Roth IRAs for this tax year?
- MAGI: Am I clearly below the direct Roth limit, clearly above it, or close enough that I should calculate before funding?
- Tax year: Did I select the correct contribution year at the custodian?
- Investment: After the cash arrives, what is it actually invested in?
Those five checks solve most of the practical confusion on this page. Notice what isn’t on the list: whether your brokerage happens to call the account a “Roth IRA” or a “Roth Contributory IRA.” The label matters less than what kind of money movement you are making and which rulebook comes with it.
Bottom Line: Identify the Money Movement Before You Apply the Rule
A regular Roth IRA contribution is straightforward once you separate it from conversions and rollovers. For 2026, start with the $7,500 annual IRA limit ($8,600 at age 50+), then check taxable compensation and MAGI, confirm the tax year, and make sure the contribution gets invested.
If your custodian calls the account a Roth Contributory IRA, the name is describing the contribution-funded pathway, not creating a new kind of Roth IRA. That’s the distinction worth keeping. Once you know which door the money is entering through, the rest of the rules get much easier to sort out.
