
Roth conversion rules determine whether the transaction is eligible, how much is taxable, which tax year it belongs to, how it is reported, and what restrictions apply after the conversion. There is no income cap on Roth conversions, but account type, basis, RMDs, deadlines, reporting forms and five-year rules can materially change how the transaction works.
This page owns the IRS compliance and execution rules. If you are still deciding whether converting belongs in your plan, how much to convert, or whether IRMAA changes the tradeoff, start with the Roth IRA conversion guide.
A good Roth conversion idea can still become a bad implementation. Strategy answers “why and how much?” Rules answer “can this be done this way, in this year, and reported correctly?” Keep those jobs separate.
Show the short version
- Income limit: There is no income cap that prevents an otherwise eligible taxpayer from converting traditional IRA money to Roth.
- Tax: The untaxed portion converted is generally included in gross income for the conversion year; after-tax basis can make part of an IRA conversion nontaxable.
- Deadline: A conversion belongs to the tax year in which the conversion transaction occurs. It is not a prior-year IRA contribution you can designate after year-end.
- RMD: An RMD is not eligible for rollover or Roth conversion. If you are subject to an RMD, that required amount must be dealt with separately.
- Undo: Roth conversions made in 2018 or later cannot be recharacterized back to traditional.
- Reporting: Conversions commonly involve Form 1099-R, Form 5498 and Form 8606, depending on the transaction and basis.
On This Page
- Key Takeaways Ahead
- Roth Conversion Rules at a Glance
- Who Can Do a Roth Conversion?
- Which Accounts Can Be Converted?
- How Roth Conversions Are Taxed
- Roth Conversion Deadline: Which Tax Year Counts?
- Can You Undo a Roth Conversion?
- Roth Conversion Pro-Rata Rule
- Forms and Tax Reporting
- Roth Conversion Five-Year Rule
- Common Roth Conversion Rule Mistakes
- Choose your next Roth conversion question
- Bottom Line
- How We Verified This
Key Takeaways Ahead
Roth Conversion Rules at a Glance
| Rule | What it means | Why it matters |
|---|---|---|
| No conversion income cap | High income does not by itself block a Roth conversion. | Do not confuse Roth contribution income limits with conversion eligibility. |
| Untaxed money is generally taxable | Pre-tax amounts converted generally enter gross income in the conversion year. | The cash moved and taxable amount are not always identical when basis exists. |
| RMDs cannot be converted | A required minimum distribution is an ineligible rollover distribution. | You cannot label the required amount as a Roth conversion. |
| Conversions are not reversible | Conversions made in 2018 or later cannot be recharacterized back to traditional. | Do not execute first and assume you can undo it later. |
| Tax year follows the transaction | Conversion income is reported for the year the conversion occurs. | A conversion is not a prior-year IRA contribution you can elect after year-end. |
| Basis is shared across IRAs | Form 8606 generally looks across traditional, SEP and SIMPLE IRAs when allocating basis. | You generally cannot cherry-pick only after-tax IRA dollars for a tax-free conversion. |
Who Can Do a Roth Conversion?
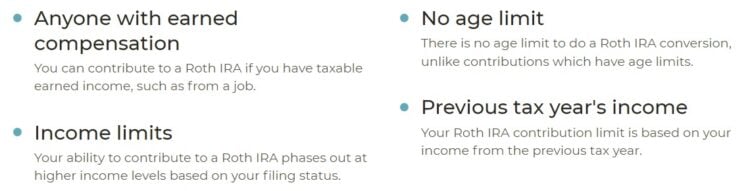
There is no income limit that prevents you from converting otherwise eligible traditional IRA money to a Roth IRA. This is different from making a regular Roth IRA contribution, which can be limited by modified adjusted gross income.
Roth contribution eligibility and Roth conversion eligibility are not the same thing. A person can earn too much to make a direct annual Roth IRA contribution and still be allowed to convert eligible pre-tax retirement money to Roth.
Which Accounts Can Be Converted?
- Traditional IRA: generally convertible to a Roth IRA, with untaxed amounts included in income.
- SEP IRA: traditional SEP IRA amounts can generally be converted, subject to the normal tax and basis rules.
- SIMPLE IRA: special timing rules matter. During the first two years of SIMPLE IRA participation, movement outside another SIMPLE IRA is restricted; after that period, conversion to Roth may be available under the applicable rollover rules.
- Eligible employer-plan money: certain distributions from 401(k), 403(b) and other eligible retirement plans can be rolled to a Roth IRA, and some plans also permit in-plan Roth rollovers. Plan terms control what is available.
Employer-plan money deserves special care because the plan document, distributable-event rules and rollover method can matter. “I have a 401(k)” is not enough information to know whether a particular conversion route is available today.
How Roth Conversions Are Taxed
The basic rule is simple: amounts that would have been taxable when distributed from the traditional account are generally included in gross income when converted to Roth. But that does not mean every dollar moved is always taxable.
If your IRA contains only deductible contributions and earnings, a conversion is generally taxable. If you have nondeductible traditional IRA basis, Form 8606 determines the taxable and nontaxable portions under the applicable rules.
The IRS specifically notes that a return of basis is not included in gross income. The complication is that basis generally cannot be isolated from the rest of your traditional, SEP and SIMPLE IRA balances just because you would prefer to convert the after-tax dollars first.
Roth Conversion Deadline: Which Tax Year Counts?
A Roth conversion is reported for the tax year in which the conversion transaction occurs. Unlike a regular IRA contribution, you do not get to make a conversion after year-end and designate it for the prior tax year.
If you want conversion income on a particular calendar-year return, the conversion needs to be completed in that calendar year. Do not confuse the April IRA contribution deadline with a Roth conversion deadline.
Do not wait until the final business day to discover that your custodian has processing cutoffs, paperwork requirements, settlement delays or a holiday schedule. The tax rule and the custodian’s practical processing deadline are two different things.
Can You Undo a Roth Conversion?
No—not by recharacterizing the conversion back to traditional. The IRS states that a traditional-to-Roth conversion, and a rollover from another eligible retirement plan to Roth, made in tax years beginning after December 31, 2017 cannot be recharacterized back to traditional.
This is different from recharacterizing certain IRA contributions. The dedicated IRA recharacterization guide explains that distinction.
Roth Conversion Pro-Rata Rule
The pro-rata rule matters when you have both after-tax basis and pre-tax money across traditional IRAs. You generally cannot point to one after-tax contribution and declare only that slice tax-free while ignoring the rest of your traditional, SEP and SIMPLE IRA money.
Community discussions repeatedly show the same problem: someone makes a nondeductible IRA contribution, converts it, and only later realizes an older rollover IRA or SIMPLE/SEP balance changes the Form 8606 calculation. The mistake is treating one account as if the tax rule sees it in isolation.
This page stops at the rule. It is not a backdoor-Roth strategy article. If basis exists, use Form 8606 and the current IRS instructions rather than relying on a “convert the after-tax account first” shortcut.
Forms and Tax Reporting
A Roth conversion can generate several tax documents that do different jobs:
- Form 1099-R: generally reports the distribution from the traditional IRA or retirement plan.
- Form 5498: the receiving IRA custodian reports Roth conversion contributions and other IRA information; you generally do not file Form 5498 with your tax return.
- Form 8606: reports traditional/SEP/SIMPLE IRA conversions to Roth and is essential when nondeductible basis is involved.
Form 8606 errors are not theoretical. Real taxpayers regularly discover that old basis, multiple IRAs or an incorrectly prepared return changes the result. Keep prior Forms 8606 and supporting records rather than trying to reconstruct basis years later.
Roth Conversion Five-Year Rule
Roth conversions can have a separate five-year period that matters for the 10% additional-tax rules on certain early distributions of converted amounts. That is not the same question as the Roth IRA five-tax-year rule used to determine whether earnings are part of a qualified distribution.
Do not try to memorize both clocks from one sentence. If you expect to use converted money before age 59½ or otherwise need the distribution rules, use the dedicated Roth IRA five-year rule guide and the Roth IRA withdrawal ordering-rules guide.
Common Roth Conversion Rule Mistakes
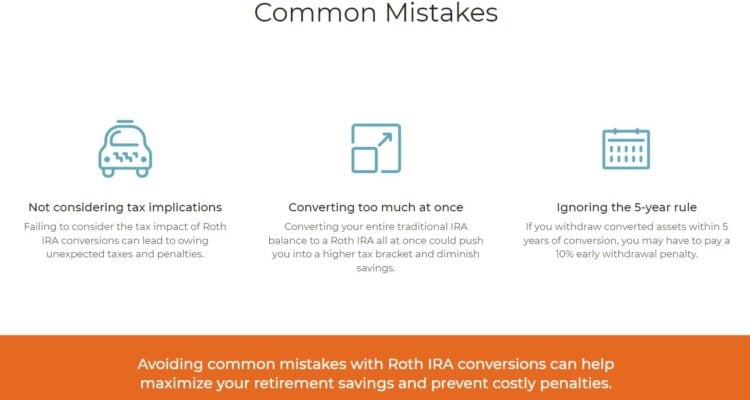
- Using Roth contribution income limits as conversion limits. They are different rules.
- Assuming every converted dollar is taxable. Nondeductible basis can make part of the conversion nontaxable.
- Trying to cherry-pick only after-tax IRA dollars. The pro-rata calculation can pull other traditional/SEP/SIMPLE IRA balances into the equation.
- Attempting to convert an RMD. Required minimum distributions are not eligible rollover distributions.
- Assuming a conversion can be undone. Modern Roth conversions cannot be recharacterized back to traditional.
- Confusing the contribution deadline with the conversion year. A conversion belongs to the year the transaction occurs.
- Losing track of basis or Form 8606 history. That can make a later tax return look much simpler than it really is.
- Ignoring a plan’s own rules. Employer plans can limit whether and how an in-plan Roth rollover or outside Roth IRA rollover is available.
Notice what is not on that list: “You picked the wrong tax bracket,” “You should have converted more,” or “IRMAA made the strategy bad.” Those are planning questions and belong on the Roth conversion roadmap and specialist planning pages—not on this compliance page.
Bottom Line
The Roth conversion rules are mostly about classification, timing and reporting. Confirm that the account and money are eligible, identify the taxable portion, keep RMDs out of the conversion, complete the transaction in the intended tax year, and preserve the forms and basis records that explain what happened.
Then keep the strategy question where it belongs. Whether the conversion was actually a good planning decision depends on tax rates, thresholds, future income and household goals—the job of the conversion hub, not the IRS rulebook.
How We Verified This
These are the authorities and references used to verify the material facts in this article.
