

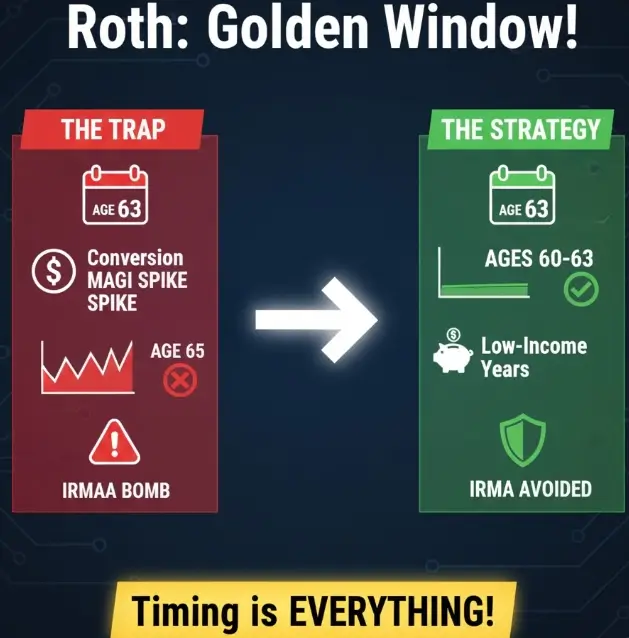
The best Roth conversion years before Medicare are not a fixed age range. The safer way to find your Roth conversion “Golden Window” is to count backward from the first calendar year you expect to pay Medicare premiums. Social Security generally uses tax information from two years before the Medicare premium year to determine IRMAA, so the tax year matters more than whether you happen to be 62 or 63 when you convert.
That distinction sounds small. It is not. A conversion done in a low-income retirement year can still raise Medicare Part B and Part D premiums two years later. And if you use Marketplace health insurance before Medicare, conversion income can affect your premium tax credit even when IRMAA is still years away.
Quick Answer
The taxable portion of a Roth conversion increases income in the conversion year. For IRMAA, Social Security generally looks at your modified adjusted gross income from two years before the Medicare premium year. If your first Medicare premium year is 2029, your 2027 tax return will generally be the starting point for that IRMAA determination. A conversion in 2026 is therefore outside the standard two-year lookback for 2029; a conversion in 2027 is not. Use calendar years first, then check your age and enrollment date.
Key Takeaways
- Count backward from Medicare, not forward from your birthday. “Convert before 63” is a shortcut, not a planning rule.
- IRMAA uses a premium-year lookback. Social Security generally requests IRS MAGI from the tax year two years before the year for which it is setting Medicare premiums.
- A Roth conversion can raise MAGI. The taxable portion of the conversion is included in income and can push you into a higher IRMAA tier.
- “IRMAA-safe” does not mean “cost-free.” Before Medicare, Marketplace premium tax credits and ordinary income-tax brackets can also change the economics of a conversion.
- Crossing an IRMAA tier is not automatically a mistake. Sometimes paying a surcharge is still rational if the long-term tax benefit of the conversion is larger. That is a separate tradeoff from choosing the timing window.
Key Takeaways Ahead
How the IRMAA 2-Year Lookback Affects Roth Conversions
IRMAA is the income-related monthly adjustment amount added to Medicare Part B and Part D premiums for beneficiaries above the applicable income thresholds. The Social Security Administration’s current MAGI policy says the agency generally uses tax information from two years before the premium year. For example, 2026 Medicare premiums are generally based on 2024 tax-return information.
For IRMAA, MAGI is generally your federal adjusted gross income plus tax-exempt interest. A Roth conversion matters because the taxable portion of a conversion is included in gross income. If you need the conversion mechanics first, my Roth IRA conversions guide owns that broader decision and execution process.
In 2026, the standard Medicare Part B premium is $202.90 per month. The first IRMAA tier begins above $109,000 of MAGI for most single filers and above $218,000 for married couples filing jointly. At that first tier, the 2026 Part B adjustment is $81.20 per month and the Part D adjustment is $14.50 per month. For someone enrolled in both for all 12 months, that is $1,148.40 of additional annual premiums before the underlying Part D plan premium. Those figures come from the CMS 2026 Medicare premium tables.
Michael’s Take
The mistake I would avoid is treating “age 63” like a magic wall. Medicare does not ask how old you felt when you clicked the conversion button. It looks at a tax year. Put the calendar years on paper first; the birthday is only one input.
The Roth Conversion Golden Window: Count Backward From Medicare
I use “Golden Window” to describe the lower-income years after work slows or stops and before a conversion starts feeding into the tax years used for Medicare IRMAA. For many retirees that window does fall in the early 60s. But the useful rule is calendar-based, not age-based.
Start with the first calendar year you expect to pay Medicare premiums. Then count back two tax years. That second-prior year is generally the income year Social Security will request first for IRMAA.
- Write down your first Medicare premium year. Suppose it is 2029.
- Count back two tax years. For 2029 premiums, Social Security will generally look first to 2027 MAGI.
- Separate “outside the lookback” from “bad year to convert.” A 2026 conversion is outside the standard 2029 IRMAA lookback. A 2027 conversion can affect 2029 IRMAA, but that does not automatically make the conversion a bad decision.
This is why two people who are both “63” can need different planning language. Birth month, retirement date, Medicare enrollment timing, filing status, and the calendar year of the conversion all matter. The cleaner question is: Which tax return will Medicare use for the premium year I care about?
Roth Conversion Timing Table: Which Tax Years Can Affect IRMAA?
| Conversion tax year | Potential Medicare premium year under the normal 2-year lookback | If first Medicare year is 2029 |
|---|---|---|
| 2026 | 2028 | Normally outside the first 2029 IRMAA lookback |
| 2027 | 2029 | Can affect first-year IRMAA |
| 2028 | 2030 | Can affect the following year’s IRMAA |
| 2029 | 2031 | Can affect IRMAA two years after conversion |
The table is a planning map, not a promise that Social Security will always use exactly that return. SSA can use older information in limited data-availability situations and has procedures for using more recent information after qualifying life-changing events. But for ordinary planning, the premium-year-minus-two relationship is the right starting point.
The Planner’s Playbook: 4 Steps for Your Golden Window
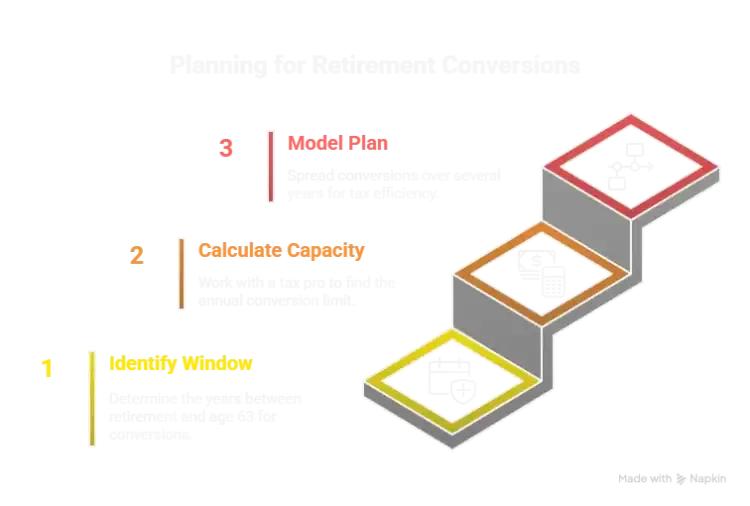
Step 1: Build the Medicare Calendar
List your expected Medicare start year, then map the two prior tax years. Do this before deciding on a conversion amount. It prevents the most common timing error: calling a year “safe” because your earned income is low without checking which future Medicare premium year will use that return.
Step 2: Estimate the Income You Already Have
Estimate pension income, taxable interest, dividends, capital gains, taxable Social Security, IRA withdrawals, business income, and other items that can affect MAGI. If you are unsure what belongs in the IRMAA calculation, use the IRMAA Income Checker before you add a conversion on top.
Step 3: Size the Conversion Separately
Timing tells you which year deserves attention. It does not tell you how much to convert. Once you pick a candidate year, calculate your tax-bracket room and your distance from the next IRMAA tier. My separate guide on how much Roth conversion before IRMAA owns that sizing calculation.
Step 4: Test the Whole-Year Cost
Do not optimize IRMAA in isolation. A conversion also creates federal income tax and may affect state tax, capital-gain interactions, and other income-sensitive benefits. If you buy Marketplace coverage before Medicare, the IRS says the premium tax credit depends on household income, so a conversion that raises adjusted gross income can also reduce the credit. That is why I would leave a buffer rather than aim at an income threshold down to the last dollar.
Want the timing logic without having to rebuild it next year?
IRMAA thresholds can change from year to year. Your retirement date can move. The two-year lookback does not care that last year’s spreadsheet looked perfect. My weekly newsletter focuses on the planning details that change the decision — Roth timing, Medicare income rules, tax thresholds, and the expensive little interactions that are easy to miss.
Use it as your reminder to recheck the calendar before a year-end conversion.
Common Roth Conversion Timing Mistakes Before Medicare
Confusing the Roth Conversion 5-Year Rule
Each conversion has a separate five-year period for purposes of the potential 10% additional tax on certain early distributions of taxable converted amounts. That is different from the five-year rule used to determine whether Roth IRA earnings are part of a qualified distribution. IRS Publication 590-B explains the separate conversion periods, and my Roth IRA five-year rule guide separates the clocks in plain English.
Ignoring IRA Basis and the Pro-Rata Calculation
If you have nondeductible basis along with pretax money across traditional, SEP, or SIMPLE IRAs, you generally cannot choose to convert only the after-tax dollars and call the conversion tax-free. Form 8606 applies the basis calculation across the relevant IRA balances. Review the IRS conversion and basis rules before assuming the full conversion is taxable or nontaxable.
Starting Other Income Without Rechecking Conversion Room
Social Security, pensions, investment income, capital gains, and IRA distributions can change the amount of conversion room you thought you had. The right sequence is not “pick a conversion target, then hope the rest fits.” Build the income stack first and put the Roth conversion on top last.
Treating IRMAA as a Cost You Must Avoid at Any Price
IRMAA is a real cost, but it is one cost. A smaller conversion that avoids a surcharge can be worse over the long run if it leaves substantially more pretax money exposed to higher future tax rates or larger required distributions. This page’s job is to help you identify the timing. Once a conversion could cross a tier, compare the surcharge with the tax benefit instead of treating the threshold as a stop sign. If you are deciding whether to pay IRMAA for a larger conversion, use that separate tradeoff analysis.
Account Access Check
If you separated from your employer during or after the year you turned 55, review the Rule of 55 before moving your entire 401(k) to an IRA. Keeping part of the balance in a qualifying employer plan may preserve an early-withdrawal option. Withdrawals can also use income room you might otherwise devote to a Roth conversion.
Frequently Asked Questions
Do Roth conversions affect Medicare premiums if I’m already on Medicare?
They can. The taxable portion of a Roth conversion can raise MAGI for that tax year, and Social Security generally uses tax information from two years before the Medicare premium year. A conversion after Medicare begins can therefore affect IRMAA two years later.
Is age 63 always too late for a Roth conversion?
No. Age 63 is not a universal cutoff. The key question is whether the conversion tax year is the tax year Social Security will generally use for the Medicare premium year you are planning around. Even when a conversion will affect IRMAA, it may still make financial sense after comparing the surcharge with the long-term tax benefit.
What if I retire at 65 and my old salary triggers IRMAA?
A work stoppage or work reduction can qualify as a life-changing event for an IRMAA redetermination when it reduces household income. Social Security may allow use of a more recent estimate through Form SSA-44. A Roth conversion itself is not one of the listed life-changing events, so include planned conversion income when estimating the newer year’s MAGI.
Can I convert money from a 401(k) to a Roth?
Potentially. Some employer plans allow in-plan Roth conversions, and an eligible distribution may be rolled to an IRA and converted. Plan terms, rollover eligibility, tax withholding, and access needs matter, so verify the plan rules before moving the account.
Your Next Step: Build the Calendar Before You Pick the Conversion Amount
The Roth conversion Golden Window is useful because retirement often creates a temporary gap between a paycheck-heavy tax return and the later years when Social Security, required distributions, and Medicare costs all compete for the same income space. But the window is not “ages 60 through 63.” It is the set of tax years in which a conversion still fits your broader plan at an acceptable total cost.
My sequence is simple: identify the first Medicare premium year, count back two tax years, estimate the income already on those returns, and only then size the conversion. If the best conversion crosses an IRMAA tier, model the tradeoff instead of assuming the tier automatically kills the strategy.
Sources
- Social Security Administration — Modified Adjusted Gross Income (MAGI) policy for IRMAA
- Social Security Administration — IRMAA determination process
- Social Security Administration — Request to lower IRMAA after a life-changing event
- Centers for Medicare & Medicaid Services — 2026 Medicare Parts B premiums and IRMAA tables
- Internal Revenue Service — Publication 590-B, IRA distributions and Roth conversion five-year periods
- Internal Revenue Service — Premium Tax Credit questions and answers
