

To max out a Roth IRA in 2026, contribute up to the amount you are legally allowed to put into IRAs for the year: $7,500 if you are under 50, or $8,600 if you are 50 or older because the 2026 catch-up contribution is $1,100. Then make sure the money is actually invested according to your plan instead of simply sitting in the account’s cash position.

The math is simple. The cash-flow system is the part that makes or breaks the goal. In nearly three decades of financial planning, I learned to separate the annual target from the funding method. A Roth IRA plan you can sustain for 12 months is better than a heroic January transfer that leaves the rest of your finances scrambling.
So this is not another page telling you what a Roth IRA is. It is the practical playbook for finding the money, choosing a contribution schedule, avoiding the mistakes that can turn “maxed out” into “not actually invested,” and knowing when maxing the Roth should not be your next dollar.
Quick Answer
For 2026, your Roth IRA max starts with the annual IRA limit of $7,500, or $8,600 if you are age 50 or older, but your personal limit can be lower because of taxable compensation or Roth IRA income eligibility. Pick a funding cadence that fits your real cash flow, automate it when possible, and verify that each deposit is invested rather than left in cash. If your employer offers a match, your emergency cash is thin, or expensive debt is squeezing the budget, forcing the Roth IRA maximum may be the wrong order of operations. High earners who cannot contribute directly may still have a backdoor Roth path, but existing pre-tax IRA money can make part of the conversion taxable.
Key Takeaways Ahead
First, Know Your 2026 Roth IRA Max
The IRS’s official 2026 retirement-plan limits set the annual IRA contribution cap at $7,500. If you are 50 or older by the end of 2026, the catch-up contribution is $1,100, bringing the total to $8,600.
If you want the full limit mechanics, including how Roth and Traditional IRA contributions share the same annual cap, use my guide to the 2026 Roth IRA contribution limit. For this page, the point is simpler: know your legal ceiling before you build the funding schedule.
2026 Roth IRA Income Limits
Use your 2026 Roth IRA modified adjusted gross income and tax-filing status to determine whether you may make the full direct contribution, a reduced contribution, or no direct contribution.
| Tax-filing status | Full contribution | Reduced contribution | No direct contribution |
|---|---|---|---|
| Single or head of household | Less than $153,000 | $153,000 to less than $168,000 | $168,000 or more |
| Married filing jointly or qualifying surviving spouse | Less than $242,000 | $242,000 to less than $252,000 | $252,000 or more |
| Married filing separately You did not live with your spouse at any time during 2026. | Less than $153,000 | $153,000 to less than $168,000 | $168,000 or more |
| Married filing separately You lived with your spouse at any time during 2026. | $0 | More than $0 to less than $10,000 | $10,000 or more |
The contribution limit is shared
The $7,500 or $8,600 limit generally applies to your combined traditional IRA and Roth IRA contributions for 2026. It is not a separate limit for each account.
Taxable compensation can lower it
Your maximum IRA contribution is generally limited to the smaller of the annual IRA limit or your taxable compensation for the year, subject to the spousal IRA rules.
MAGI is not simply salary
Roth IRA MAGI starts with adjusted gross income and applies IRA-specific modifications. It may differ from gross income, taxable income, or the amount shown on a pay stub.
The phase-out requires a calculation
Income inside the reduced-contribution range does not automatically permit one fixed amount. Use the applicable IRS worksheet to calculate the reduced limit.
This table addresses regular direct Roth IRA contributions for the 2026 tax year. It does not determine your exact MAGI, taxable compensation, reduced contribution, eligibility for a spousal IRA, or the tax result of a Roth conversion.
Roth IRA contributions are not deductible. Eligibility to deduct a traditional IRA contribution uses different income ranges and workplace-plan rules.
This information provides general financial education, not individualized tax, legal, accounting, investment, or retirement-planning advice. Verify your calculation using current IRS instructions or a qualified tax professional.
Two rules can lower your personal Roth IRA maximum
- You need enough taxable compensation. Your regular IRA contributions generally cannot exceed your taxable compensation for the year. Married couples filing jointly may be able to use the spousal IRA rules when one spouse has little or no compensation.
- Your modified adjusted gross income can reduce or eliminate a direct Roth IRA contribution. The same IRS 2026 guidance sets the Roth contribution phase-out at $153,000 to $168,000 for single and head-of-household filers and $242,000 to $252,000 for married couples filing jointly. Check the current Roth IRA income eligibility limits before assuming the full annual amount is available to you.
Those are guardrails, not the main event. Once you know how much room you actually have, the next question is how to fill it without turning the rest of your budget upside down.
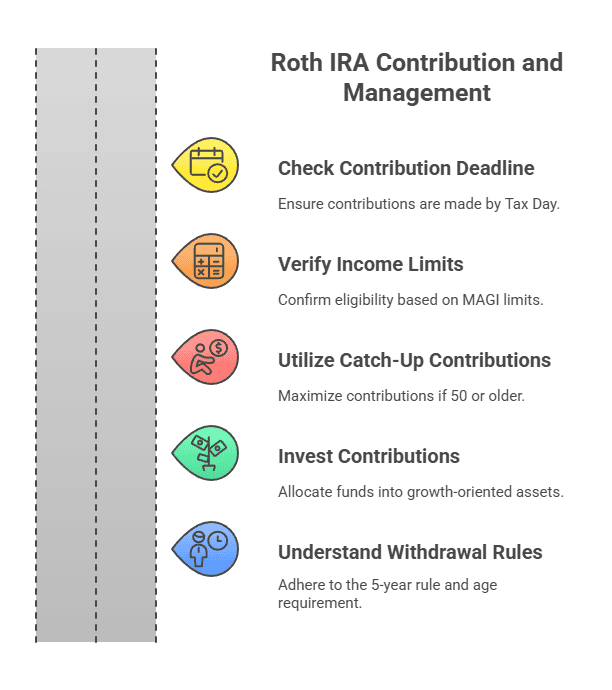
The Max-Out Blueprint: Build a Funding System That Fits Your Cash Flow
You do not get extra credit for making one dramatic contribution on January 1. If the cash is already available and the contribution is appropriate, funding early is perfectly reasonable. But if creating a January lump sum means hoarding a second year’s Roth contribution in cash while you are still funding this year’s account, you may be solving the wrong problem.
Start with the schedule your paycheck can support. For 2026, the annual targets break down like this:
| Schedule | Under age 50 | Age 50+ |
|---|---|---|
| Annual | $7,500 | $8,600 |
| Monthly | $625.00 | $716.67 |
| Twice monthly | $312.50 | $358.33 |
| Every two weeks (26 deposits) | $288.46 | $330.77 |
| Weekly | $144.23 | $165.38 |
1. Automate the amount you can sustain
For most people, automation is the cleanest answer because it turns “find $7,500” into a recurring cash-flow decision. You can automate monthly, twice-monthly, biweekly, or another cadence your custodian supports. The exact frequency matters less than whether the amount fits your budget and actually happens.
If $625 a month is too aggressive, do not pretend it isn’t. Start with the amount you can support, then use raises, paid-off debt payments, bonuses, or other freed-up cash to close the gap later in the year.
2. Use windfalls to finish the job
A bonus, commission check, tax refund, or other genuine windfall can be useful when your normal monthly cash flow cannot carry the full target. The key is to decide what portion belongs to the Roth before the money quietly becomes a bigger vacation, a nicer car payment, or twelve smaller purchases you barely remember.
For variable-income households, I prefer a percentage rule over a fixed-dollar promise. For example, you might earmark a set percentage of each commission or side-business payment for retirement until you reach your annual target. The percentage itself is personal; the system is what matters.
3. Lump sum only when the cash is already available
If you already have the cash set aside and the contribution fits your plan, a lump-sum contribution can be simple: fund it, invest it, and move on. What I would not do is strain the current budget just to say you maxed the Roth on the first business day of the year.
Michael’s rule of thumb
Do not create a cash-flow problem to solve a retirement-saving problem. Before forcing the Roth IRA maximum, make sure you are not giving up an available employer match, leaving yourself without reasonable emergency cash, or carrying expensive debt because every spare dollar went into the IRA.
4. Maxed out does not automatically mean invested
This is the quiet mistake I want you to check today. A Roth IRA is an account. Contributing money to the account does not necessarily mean you have purchased the investment you intended to own. Depending on the custodian and your setup, a contribution can land in a settlement or cash position until you place an investment order or establish an automatic investment.
Open the account and verify two separate things: Did the contribution arrive? And is that money invested according to your plan? Hitting the annual contribution number while the balance sits unintentionally in cash is only half a win.
Keep the system going
If you want more practical help turning Roth IRA contribution rules into a funding system you can actually use, get the Michael Ryan Money newsletter for retirement and tax decisions in plain English.
High Earners: Use the Backdoor Roth Carefully
If your income is too high for a direct Roth IRA contribution, that does not automatically end the conversation. A common alternative is the backdoor Roth IRA: make a nondeductible contribution to a Traditional IRA and then convert that money to a Roth IRA.

Step 1: Make a nondeductible Traditional IRA contribution
Contribute after-tax money to a Traditional IRA, staying within your remaining annual IRA contribution room. Because Traditional and Roth IRA contributions share the same annual IRA limit, you cannot contribute the full maximum to each for the same year.
Step 2: Convert the Traditional IRA to a Roth IRA
The Roth conversion itself is not limited by the Roth IRA income phase-out. But a conversion is not automatically tax-free. The IRS IRA conversion guidance explains that untaxed amounts converted from a Traditional IRA are taxable.
Watch out for existing pre-tax IRA money
If you already hold pre-tax money in Traditional, SEP, or SIMPLE IRAs, the tax calculation reported on Form 8606 can make part of a backdoor Roth conversion taxable even when the new contribution itself was nondeductible. Before doing the conversion, check your IRA balances and basis rather than assuming “after-tax contribution” means “tax-free conversion.”
That tax calculation deserves its own treatment. Use my guide to Roth conversion compliance requirements before executing the transaction if you have other IRA balances or prior nondeductible contributions.
Step 3: Report the nondeductible contribution and conversion
IRS Form 8606, Nondeductible IRAs, is used to report nondeductible Traditional IRA contributions and conversions from Traditional, SEP, or SIMPLE IRAs to Roth IRAs. Keep the tax reporting connected to the transaction; the brokerage transfer alone does not finish the job.
After Your Roth IRA Is Maxed: Where Does the Next Dollar Go?
Maxing the Roth IRA is a milestone, not the end of retirement planning. Your next dollar may belong in an employer retirement plan, an HSA if you are eligible, or a taxable brokerage account. The right order depends on your employer benefits, taxes, liquidity needs, debt, and time horizon.
If you have a 401(k), you can contribute to it and a Roth IRA in the same year because the employee 401(k) deferral limit and the IRA contribution limit are separate. An employer match is especially important because skipping available matching dollars just to say “I maxed my Roth” is usually a poor trade.
What about a Mega Backdoor Roth?
A Mega Backdoor Roth can create additional Roth space only when an employer plan supports the necessary features, typically after-tax employee contributions plus an in-plan Roth conversion or an eligible in-service rollover. This is a plan-specific strategy, not a feature every 401(k) offers.
For 2026, the IRS overall annual-additions limit for a 401(k) is generally the lesser of 100% of compensation or $72,000, before applicable catch-up contributions. That $72,000 is not an extra $72,000 on top of everything else: employee deferrals, employer contributions, and after-tax employee contributions generally count toward the same overall annual-additions limit.
Frequently Asked Questions About Maxing Out Your Roth IRA
What happens if I contribute more than my Roth IRA limit?
An excess IRA contribution can trigger a 6% excise tax for each year the excess remains in the account. The IRS excess-contribution rules explain that avoiding the 6% tax generally requires withdrawing the excess contribution and any income earned on it by the applicable tax-return due date, including extensions. A normal Roth withdrawal is not necessarily the same thing as a return-of-excess correction, so contact the custodian and follow the correction process rather than guessing.
What is the latest I can contribute for the 2026 tax year?
You can generally make a 2026 IRA contribution until the due date for your 2026 federal income tax return in 2027. IRS Publication 590-A covers the contribution timing rules. Make sure the custodian records a contribution made during that window for the correct tax year.
Can I contribute to a Roth IRA and a 401(k) at the same time?
Yes. The IRA contribution limit and the employee 401(k) deferral limit are separate, so an eligible person can contribute to both in the same year. Your Roth IRA contribution is still subject to Roth IRA income eligibility and the IRA annual contribution rules.
Your Mission: Make the System Automatic
Maxing out your Roth IRA is not one big transfer. It is a system: know your legal contribution room, choose a funding cadence your cash flow can survive, make the deposits, and verify that the money is invested.
If you cannot hit the full limit this year, that is not a reason to do nothing. Automate what you can, increase the amount when cash flow improves, and use genuine windfalls intentionally. If you can max it comfortably, make the process boring enough that you do not have to renegotiate the decision every month.
And before you celebrate the number, check the two screens that matter: your year-to-date contribution total and your actual investments. Funded and invested is the finish line.
Sources
- IRS: 2026 retirement-plan and IRA contribution limits
- IRS: Retirement Plans FAQs Regarding IRAs
- IRS Form 8606: Nondeductible IRAs
- IRS: 401(k) and profit-sharing plan contribution limits
- IRS: IRA contribution limits and excess contributions
- IRS Publication 590-A: Contributions to Individual Retirement Arrangements
