

Yes, you can roll eligible unused 529 plan money into a Roth IRA for the 529 beneficiary. But a 529 to Roth IRA rollover is not a simple $35,000 transfer. The account-age rule, five-year contribution rule, annual IRA limit, beneficiary’s compensation, and direct-transfer requirement all have to line up.
That distinction matters to me personally. My oldest son has graduated from college, my youngest is still in school, and I spent decades saving into 529 plans for my own family while helping families think through college funding. The old fear was always the same: What if we save too much? SECURE 2.0 created a useful exit ramp, but it did not turn a 529 into a second Roth contribution limit.
Quick Answer
For 2026, an eligible 529-to-Roth IRA rollover must go by direct trustee-to-trustee transfer into a Roth IRA owned by the 529 beneficiary. The 529 generally must have been maintained for at least 15 years, recently contributed amounts are restricted by a five-year rule, and the lifetime rollover ceiling is $35,000 per beneficiary. The amount you can move in one year is also limited by that beneficiary’s available IRA contribution room, which is $7,500 in 2026 for someone under age 50 and can be lower if the beneficiary has less compensation or has already made IRA contributions.
Key Takeaways Ahead
Can You Roll a 529 Into a Roth IRA?
You can, if the transfer qualifies under the special rule added by SECURE 2.0. The money moves from a long-term 529 plan into a Roth IRA maintained for the same designated beneficiary. When the requirements are met, the transfer is not treated as a taxable nonqualified 529 distribution for federal income-tax purposes.
The cleanest way to think about it is this: the 529 can fund some or all of the beneficiary’s Roth IRA contribution room for the year. It does not create extra IRA room on top of the normal annual limit.
If you need a refresher on what a 529 can pay for before deciding the money is truly “left over,” my complete 529 plan guide covers qualified uses and the broader account rules.
Michael’s Take
The $35,000 number gets all the attention. The annual limit is the number that usually controls what you can actually do next. If a beneficiary already filled their IRA for the year, the 529 rollover does not give them a second bucket.
2026 529-to-Roth IRA Rules and Limits
The IRS rules in Publication 590-A and Internal Revenue Code section 529 set out the core federal requirements. Use these as an eligibility sequence, not as five unrelated facts.
2026 529-to-Roth IRA Eligibility at a Glance
| Rule | What to check | Why it matters |
|---|---|---|
| 15-year account rule | The 529 program/account has been maintained for at least 15 years. | A younger account does not qualify for the special rollover. |
| 5-year contribution rule | The rollover cannot exceed contributions, plus attributable earnings, made before the five-year period ending on the distribution date. | Recent contributions cannot simply be moved right back out to a Roth IRA. |
| Same beneficiary | The Roth IRA is maintained for the 529 plan’s designated beneficiary. | This is not a rollover to the parent’s Roth IRA unless the parent is the qualifying 529 beneficiary. |
| Annual IRA room | For 2026, up to $7,500 under age 50 or $8,600 at age 50+, further reduced by other IRA contributions and, when lower, the beneficiary’s compensation. | The $35,000 lifetime cap cannot normally be moved in one year. |
| $35,000 lifetime cap | Total qualifying 529-to-Roth rollovers for that beneficiary across all years. | The lifetime ceiling is per beneficiary, not a new annual allowance. |
| Direct transfer | Funds move trustee-to-trustee from the 529 to the beneficiary’s Roth IRA. | Do not turn the transaction into a normal cash withdrawal to yourself. |
1. The 529 Must Meet the 15-Year Rule
The law requires the distribution to come from a qualified tuition program maintained for the 15-year period ending on the distribution date. IRS Publication 590-A describes this as a section 529 account that has been open for more than 15 years.
Here is the problem most summaries skip: the statute and current IRS guidance do not give families a clean published answer for every account-history change. If the beneficiary changed, ownership changed, or a provider transfer produced a new account number, do not assume the old history automatically carries over for this special rollover. Get the 529 administrator’s position in writing and involve a tax professional when the account history is not straightforward.
2. Contributions From the Last Five Years Are Restricted
The rollover cannot exceed the aggregate amount contributed to the 529, plus earnings attributable to those contributions, before the five-year period ending on the distribution date. That wording matters. It is not simply “the account is five years old.” A long-running account can still contain recent contributions that are not yet eligible for this rollover.
Explained Simply
If you have contributed to the 529 recently while also paying college bills from it, do not guess which dollars are seasoned. Ask the plan administrator what contribution-history records it can provide. Waiting until the recent contribution window has aged out can be cleaner than trying to force a rollover whose eligible basis is uncertain.
3. The Beneficiary Needs Available IRA Contribution Room
For 2026, the normal IRA contribution limit is $7,500, or $8,600 if the beneficiary is age 50 or older. The special 529 rollover uses that annual room. Other traditional IRA or Roth IRA contributions made for the beneficiary during the year reduce how much 529 money can be rolled over.
The beneficiary’s applicable IRA limit can also be constrained by compensation. If a 23-year-old beneficiary has $4,000 of compensation for the year and no other IRA contributions, do not assume the full $7,500 can be rolled over just because the statutory dollar limit is $7,500.
For a broader explanation of the annual cap and compensation rules, see my current guide to 2026 Roth IRA contributions.
4. The Lifetime 529-to-Roth Limit Is $35,000 Per Beneficiary
The federal lifetime maximum is $35,000 of qualifying special rollovers for an individual beneficiary. It is not $35,000 per 529 account and it is not $35,000 every year.
A simple 2026 example: suppose a 24-year-old beneficiary has at least $7,500 of compensation, has made no other IRA contribution for the year, and otherwise meets the 529 requirements. The most that can use the 2026 IRA room is $7,500. If the beneficiary later completes additional qualifying rollovers, those amounts count toward the same $35,000 lifetime ceiling.
5. High Income Does Not Automatically Block the Special Rollover
This is a real advantage, but it needs to be stated precisely. For ordinary 2026 Roth IRA contributions, the IRS phaseout range is $153,000 to $168,000 for single and head-of-household filers and $242,000 to $252,000 for married couples filing jointly. The law contains a special coordination rule for qualifying 529 rollovers, so being above the normal Roth MAGI limit does not by itself eliminate the 529-to-Roth option.
That does not mean a high earner gets extra Roth space. The rollover still competes for the same annual IRA contribution room. If you are also considering a backdoor Roth contribution, treat the 529 rollover and the traditional-IRA contribution used in the backdoor process as competing uses of that year’s IRA limit.
The $35,000 Trap
The lifetime cap is the headline; the annual limit is the brake pedal. A family that sees “$35,000 tax-free rollover” and moves $26,000 in one year can create an excess-contribution problem. Check the beneficiary’s annual IRA room before you ask either custodian to move a dollar.
How to Complete a 529-to-Roth IRA Rollover
Once the eligibility rules check out, the operational goal is boring on purpose: get the right amount from the right 529 directly to the right Roth IRA and keep enough records to explain what happened later.
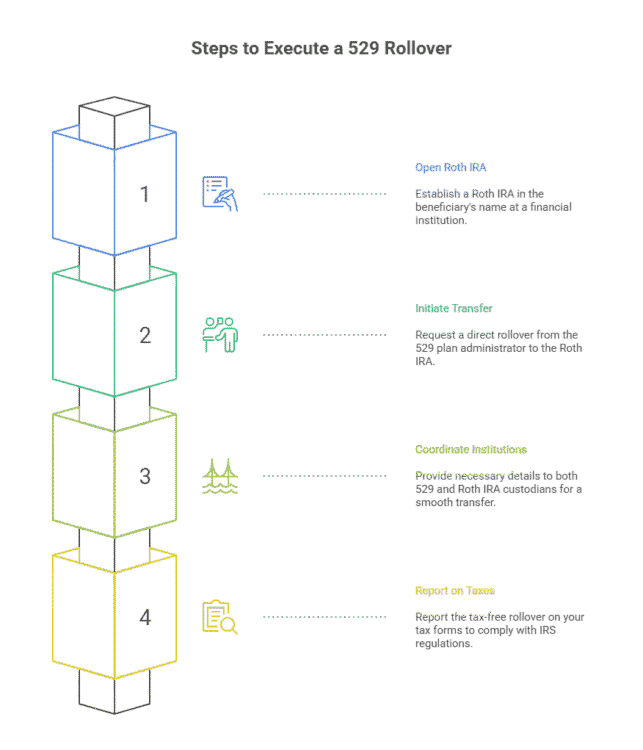
Step 1: Verify Eligibility Before Opening the Transfer
Confirm the 529’s age, the contribution history relevant to the five-year rule, the designated beneficiary, the beneficiary’s compensation, IRA contributions already made for the year, and prior 529-to-Roth rollovers that count toward the $35,000 lifetime cap.
Step 2: Make Sure the Roth IRA Belongs to the 529 Beneficiary
The receiving Roth IRA must be maintained for the benefit of the 529 plan’s designated beneficiary. If the beneficiary does not already have a Roth IRA, open one before initiating the transfer and confirm that the custodian accepts 529 special rollover contributions.
Step 3: Request a Direct Trustee-to-Trustee Transfer
Start with the 529 administrator and the Roth IRA custodian. The IRS’s qualified tuition program guidance requires the special rollover to be paid through a direct trustee-to-trustee transfer.
Do Not Turn This Into a DIY 60-Day Rollover
Do not withdraw the 529 money to your checking account and assume you can redeposit it into the Roth IRA later. The special 529 rule requires a direct trustee-to-trustee transfer. Ask both institutions for their 529-to-Roth procedure before money moves.
Step 4: Keep the Tax Forms and Contribution Records Together
The 529 plan generally reports the distribution on Form 1099-Q, while the Roth IRA custodian reports qualified 529 rollover contributions on Form 5498. The 2026 IRS instructions for Form 5498 specifically tell custodians to report qualifying section 529 rollover contributions in the Roth IRA contribution box.
Save the 529 contribution history, transfer request, custodian confirmations, 1099-Q, and 5498 together. If the five-year rule or the account’s 15-year history is ever questioned, the useful answer is a document trail, not your memory of when the account was opened.
What Can Go Wrong: Ambiguous Rules, State Taxes, and FAFSA
Beneficiary or Account Changes Can Create a 15-Year Question
This is the gray area I would take most seriously. Federal law clearly tells us that the qualifying distribution must come from a long-term 529 program for the designated beneficiary. Current IRS publications state the 15-year requirement, but they do not give a simple universal rule telling you what happens to that clock after every beneficiary change, owner change, plan-to-plan transfer, or account-number change.
So I would not write “the clock definitely resets” or “the clock definitely carries over” as a blanket rule. If the account’s history changed, ask the plan administrator how it documents the original establishment date and beneficiary history, then have a tax professional review the facts before relying on the rollover exclusion.
State Tax Treatment Can Differ From the Federal Rule
The federal rollover can qualify for tax-free treatment while your state applies its own 529 deduction, credit, conformity, or recapture rules. State rules have also changed since the federal provision took effect. Before transferring, check the current treatment in your state rather than relying on an old list of “recapture states.”
If you received a state tax deduction or credit for 529 contributions, this is worth checking with the plan and your state’s tax authority before the rollover. The question is simple: Does my state treat a federal 529-to-Roth rollover as a qualified distribution for state tax purposes, and does it recapture any prior tax benefit?
A Roth IRA Is Not Reported as a FAFSA Asset, but Timing Still Matters
Federal Student Aid’s current FAFSA guidance excludes the value of retirement plans and noneducation IRAs from reportable investments. That means a Roth IRA itself is not reported as a FAFSA asset. A 529 owned for the student can be a reportable education-savings asset, so the account type changes how the balance is classified on the FAFSA.
Do not turn that into a blanket claim that a rollover can never affect financial aid. FAFSA treatment depends on the student’s broader facts and the relevant application year. If aid eligibility still matters, review the current Federal Student Aid FAFSA asset guidance before changing accounts.
Should You Roll Over the Money or Keep It in the 529?
A Roth rollover reduces one of the biggest psychological risks of saving for college: being stuck with money you no longer need for school. But it does not make deliberate overfunding the default strategy.
Before moving money, ask a more useful question: What job does this money still need to do? If future education for the beneficiary or another family member is realistic, keeping the 529 can preserve flexibility. If education needs are done, the beneficiary has available IRA room, and the rollover rules are clean, moving eligible dollars to the Roth can be attractive.
What to Do With Leftover 529 Money
| Option | Best fit | Main tradeoff |
|---|---|---|
| 529-to-Roth IRA rollover | Beneficiary meets the rollover rules and no longer needs all of the 529 for education. | Uses annual IRA room and is capped at $35,000 lifetime. |
| Keep the 529 | Graduate school, future credential costs, or later family education use is plausible. | Money remains tied to qualified 529 uses for tax-free treatment. |
| Change the beneficiary | Another eligible family member has education needs. | A beneficiary change can complicate the unanswered 15-year question if a later Roth rollover is part of the plan. |
| Student-loan repayment | The beneficiary or eligible sibling has qualifying student debt. | Federal 529 student-loan use has a lifetime dollar limit and state treatment can differ. |
| Nonqualified withdrawal | Education and rollover options do not fit and cash access is more important. | The earnings portion is generally subject to income tax and may face the 10% additional tax unless an exception applies. |
If you are still sorting out the account’s broader choices, my 529 plan questions and answers page covers beneficiary changes, qualified uses, and other common leftover-fund questions.
The Decision Rule I Use
Do not roll money out of a 529 merely because the Roth option exists. First decide whether the money still has a credible education job. If it does not, then test the Roth eligibility rules. The order matters: purpose first, tax wrapper second.
529-to-Roth IRA Rollover Checklist
If you think the rollover fits, use this checklist before contacting the custodians.
- Confirm the 529 history. Find the original establishment date and note any beneficiary, owner, provider, or account-number changes.
- Pull the contribution records. Identify whether recent contributions could limit the amount available under the five-year rule.
- Check the beneficiary’s 2026 IRA room. Start with the $7,500 limit under age 50 or $8,600 at 50+, then subtract other IRA contributions and consider the beneficiary’s compensation.
- Check prior special rollovers. Make sure the new amount will not push the beneficiary over the $35,000 lifetime cap.
- Verify state tax treatment. Especially check for deduction or credit recapture if your state gave you a tax break for contributions.
- Confirm both institutions can process the transaction. Ask specifically for a direct 529-to-Roth IRA trustee-to-trustee transfer for the beneficiary.
- Keep the paperwork. Save contribution history, transfer instructions, confirmations, Form 1099-Q, and Form 5498.

The useful part of this rule is not that it lets you “escape” a 529. It gives families one more controlled way to repurpose genuinely unused education money. If your facts are clean, the process can be straightforward. If the beneficiary or account history changed, that is where I would slow down and document first.
