

Yes, you can have a Roth IRA and a 401(k) and contribute to both in the same year. Having a workplace 401(k) does not use up your separate IRA contribution limit, and it does not by itself disqualify you from making a direct Roth IRA contribution.
The part that trips people up is what comes next. You are dealing with two different contribution systems: your workplace 401(k) has its own employee-deferral limit and plan rules, while your Roth IRA has a separate IRA limit plus its own income-eligibility test. Then you still have to decide how much of your savings budget belongs in each.
In my years as a financial planner, I have found that the useful question is not simply, “Can I have both?” It is: What job should each account do in my plan? Once you separate eligibility, limits, and funding priority, this gets much easier.
Quick Answer
In 2026, you can contribute up to $24,500 in employee elective deferrals to a 401(k) and, if eligible, up to $7,500 across your Traditional and Roth IRAs. Those are separate limits. If you are 50 or older, catch-up contributions can increase the available room. A direct Roth IRA contribution also depends on your taxable compensation and modified adjusted gross income (MAGI), while a Roth 401(k) does not use the Roth IRA income-limit test.
Quick Links: Using a Roth IRA and 401(k) Together
Key Takeaways: Roth IRA + 401(k) in 60 Seconds
- You can use both: A 401(k) and Roth IRA can both receive contributions in the same year if you qualify for each.
- The limits are separate: Your 401(k) employee-deferral limit does not reduce your separate IRA contribution limit.
- Some limits are shared inside each system: Traditional and Roth 401(k) employee deferrals share the 401(k) limit; Traditional and Roth IRA contributions share the IRA limit.
- Roth IRA income rules still matter: Your workplace plan does not make you automatically eligible for a direct Roth IRA contribution.
- “Match → IRA → 401(k)” is a priority framework: It is not a federal rule and it is not necessarily the literal order in which money should leave each paycheck.
Can You Have a Roth IRA and a 401(k) at the Same Time?
Yes. The IRS treats a workplace 401(k) and an IRA as different retirement-saving systems. You can participate in your employer’s 401(k) and also contribute to a Roth IRA during the same tax year, provided you meet the rules for each account.
Think of this as two gates, not one. Your 401(k) contribution depends on your eligibility under the employer’s plan. Your direct Roth IRA contribution depends on having enough taxable compensation and staying within the Roth IRA MAGI rules.
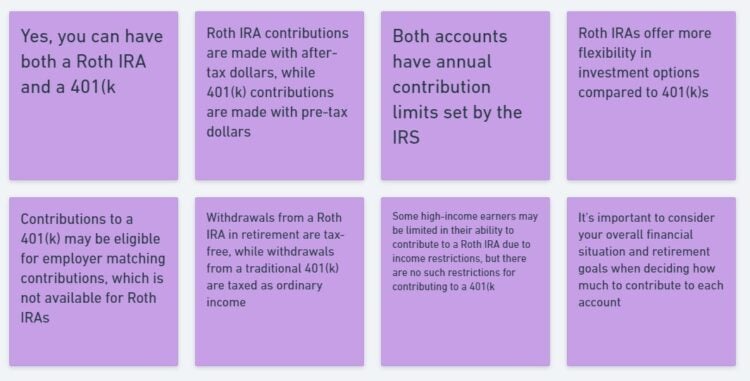
The cleanest way to remember it is this: having a 401(k) does not “take away” your Roth IRA contribution room. The Roth IRA has its own annual IRA limit and eligibility test.
2026 Roth IRA and 401(k) Limits: What Is Separate and What Is Shared?

The IRS 2026 retirement-plan limits make the separation clear: the employee elective-deferral limit for most 401(k) plans is $24,500, while the annual contribution limit across your IRAs is $7,500.
| Contribution bucket | 2026 limit | What shares this limit? |
|---|---|---|
| 401(k) employee elective deferrals | $24,500 | Your pre-tax Traditional 401(k) and Roth 401(k) employee deferrals share this employee limit. |
| IRA contributions | $7,500 | Your Traditional IRA and Roth IRA regular contributions share this IRA limit. |
| Age 50+ 401(k) catch-up | Generally $8,000 | Eligible catch-up deferrals under the workplace plan; ages 60–63 have a higher $11,250 catch-up limit in 2026. |
| Age 50+ IRA catch-up | $1,100 | Added to the combined Traditional + Roth IRA limit. |
So, if you are under 50 and eligible to use both, the two employee contribution systems can provide up to $32,000 of combined 2026 contribution room before considering any employer contribution. That does not mean everyone should—or can afford to—fill both accounts. It simply shows why a 401(k) does not crowd out the IRA limit.
For the detailed IRA rules, including catch-up treatment and how Traditional and Roth IRA contributions coordinate, use the current Roth IRA contribution limits guide.
Which Account Should Get Your Next Retirement Dollar?
This is where I would stop looking for a universal winner. A Roth IRA and a 401(k) can both be excellent accounts, but they solve different practical problems.
A common starting framework is to contribute enough to the 401(k) to receive the full employer match available under your plan, then decide whether the Roth IRA deserves the next dollars, and then use additional 401(k) room if you still want to save more. The IRS’s employer-match guidance makes the first part straightforward: the match formula and the conditions for receiving it come from your plan.
But the second step is a judgment call, not a tax-code command. A Roth IRA may deserve more of your savings when you value wider investment choice, direct control of the account, or Roth IRA withdrawal flexibility. More 401(k) contributions may deserve priority when the workplace plan is inexpensive and strong, payroll automation matters to you, or pre-tax 401(k) contributions fit your current tax plan better than additional Roth savings.
Michael’s Take
Do not confuse “best account” with “best next dollar.” Your employer match may make the first 401(k) dollars unusually valuable. Your Roth IRA may be a better home for the next slice of savings. And after that, the 401(k)’s larger contribution room may become useful again. The answer can change as you move through the year.
The Funding Order Is a Priority Rule, Not a Stop-Start Payroll Sequence
This is the implementation detail I do not want you to miss. When you see a sequence such as “get the match, fund the Roth IRA, then return to the 401(k),” that is usually an order of importance. It does not mean you must literally turn your 401(k) payroll contribution off while you fund the IRA.
The distinction matters because the employer match is plan-specific. The IRS’s 401(k) matching-contribution guidance specifically notes that a plan can calculate matching contributions on a payroll-period basis or an annual basis depending on the plan document. Before front-loading your 401(k), dropping your deferral rate to zero, or changing contributions just to follow a generic hierarchy, check the plan’s matching formula and whether it provides any year-end true-up.
Do Not Confuse Priority With Timing
A priority list tells you where the next dollar deserves to go. Your payroll settings tell the employer when the dollar actually moves. Those are related decisions, but they are not the same decision.
Hypothetical example: Assume you can save $20,000 for retirement this year and your employer matches contributions up to a stated percentage of each paycheck. You might set the 401(k) payroll percentage high enough to stay on track for the full match all year while also setting a monthly Roth IRA transfer. The “priority” can still be match first, Roth IRA next, then extra 401(k)—even though money is flowing into both accounts at the same time.
Keep the Two-Account Plan Straight
Contribution limits are only one moving piece. I send one practical retirement-money check each week to help you keep employer-match rules, Roth IRA MAGI limits, contribution deadlines, and account decisions from getting mixed together.
- Know which limit applies to which account.
- Catch the plan-rule detail before it turns into a contribution mistake.
Get the next check before your next retirement contribution change.
What If Your Income Is Too High for a Direct Roth IRA Contribution?
Your 401(k) access does not create the Roth IRA income limit. The Roth IRA has its own MAGI test.
For 2026, the IRS Roth IRA phaseout ranges are $153,000 to $168,000 for single and head-of-household filers and $242,000 to $252,000 for married couples filing jointly. For a married person filing separately who lived with a spouse during the year, the range remains $0 to $10,000.
Do not use gross salary as a shortcut for this test. Roth IRA eligibility uses modified adjusted gross income, and the calculation has its own rules. If you are near a phaseout, use the detailed Roth IRA income limits guide before making or finishing the contribution.
If you are over the direct-contribution limit, that becomes a different planning job. This page is not going to bury the answer under a full backdoor Roth walkthrough.
Roth IRA vs. Roth 401(k): They Are Not the Same Account

This naming problem causes more confusion than it should. A Roth IRA is your individual retirement account. A Roth 401(k) is the designated Roth side of an employer-sponsored 401(k). “Roth” describes the tax treatment; it does not make the two accounts the same thing.
- Roth 401(k) contributions: They are employee elective deferrals inside the workplace plan and share the 401(k) employee limit with pre-tax 401(k) deferrals.
- Roth IRA contributions: They use the separate IRA limit and are subject to Roth IRA compensation and MAGI rules.
- Investment menus: A 401(k) uses the investments and administrative structure offered by the plan; a Roth IRA generally gives the account owner direct provider and investment-selection control.
- Access rules: Roth IRA and workplace-plan distribution rules are not interchangeable. If access flexibility matters, use the dedicated withdrawal guide rather than assuming every Roth dollar can be treated the same way.
One legacy rule also deserves an update: employer matching contributions are not automatically required to be pre-tax in every plan anymore. Under SECURE 2.0 Roth-match guidance from the IRS, plans can allow certain vested matching and nonelective employer contributions to be designated Roth. Your plan has to offer that treatment, so check the plan rather than assuming the match is always pre-tax or always Roth.
If you are actually deciding between those two Roth account types, use the full Roth 401(k) vs. Roth IRA comparison. If you are deciding whether you can take Roth IRA money back out, use the separate Roth IRA withdrawal rules guide.
Questions to Check Before You Set Your Contribution Percentages
- What does my employer actually match? Read the formula, vesting rules, matching computation period, and any true-up language.
- Am I eligible for a direct Roth IRA contribution? Check taxable compensation and Roth IRA MAGI, not simply gross salary.
- How much IRA room do I still have? Traditional and Roth IRA regular contributions share the same annual IRA limit.
- How much 401(k) room do I still have? Pre-tax and Roth 401(k) employee deferrals share the employee elective-deferral limit.
- Do I want pre-tax or Roth 401(k) contributions? That is a tax-treatment decision, separate from whether you also fund a Roth IRA.
- Can my cash flow support both? A contribution plan that forces you to raid retirement savings or carry expensive debt may be solving the wrong problem.
If the IRA itself is not open yet, the operational steps—provider, application, funding, and actually investing the cash—are in my guide on how to start a Roth IRA.
Bottom Line: A Roth IRA and 401(k) Can Work Together
You do not need to choose between “being a 401(k) person” and “being a Roth IRA person.” In 2026, eligible savers can use both accounts, and the contribution limits are separate.
The better plan is to give each account a job. Protect the employer benefit you are entitled to under the 401(k) plan. Check whether you are eligible for a direct Roth IRA contribution. Then decide how the remaining savings dollars fit your taxes, plan quality, investment preferences, and cash flow.
Two accounts. Two rulebooks. One savings plan. That is the mental model I would keep.
Sources
- Internal Revenue Service: 401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500
- Internal Revenue Service: Matching contributions help you save more for retirement
- Internal Revenue Service: 401(k) matching-contribution timing and plan-document guidance
- Internal Revenue Service: SECURE 2.0 designated Roth matching and nonelective contributions
- Internal Revenue Service: Retirement plans FAQs on designated Roth accounts
