

Webull itself is not an FDIC-insured bank. But that does not mean none of your money at Webull can have FDIC insurance. Eligible settled cash enrolled in Webull Cash Management can be swept to participating banks and receive FDIC coverage there. Securities held in a Webull brokerage account are generally protected under SIPC, not FDIC insurance.
That distinction matters more than the yes-or-no answer. As a financial planner for nearly 30 years, I’ve learned that the safety question usually comes before the feature question: “Michael, if something happens to the firm, what actually happens to my money?”
Here is the rule I want you to use throughout this article: the logo on the app is not what determines the insurance. Where your money is sitting does.
Key Takeaways Ahead
Is Webull FDIC Insured? The 2026 Answer
The clean answer is: Webull Financial LLC is a brokerage firm, not a bank, so your Webull securities are not FDIC insured. However, Webull’s current SIPC and FDIC disclosure says eligible uninvested cash enrolled in Cash Management can be swept to partner banks and receive FDIC insurance of up to $5 million across the program.
| Where your money is | Primary protection | What to know |
|---|---|---|
| Stocks, ETFs, bonds and other eligible securities in a Webull brokerage account | SIPC, plus applicable excess SIPC | SIPC addresses missing customer property if a member brokerage fails. It does not insure market losses. |
| Cash still held as brokerage cash and not swept to a bank | SIPC cash protection | Standard SIPC has a $250,000 cash sublimit within its $500,000 customer-protection limit. |
| Eligible settled cash swept through Webull Cash Management to participating banks | FDIC deposit insurance at the partner bank | Webull advertises up to $5 million across participating banks, but the normal $250,000-per-bank ownership rules and pass-through requirements still matter. |
That table is the article in miniature. If you remember only one thing, remember this: same app, different assets, different safety nets.
Know Which Safety Net You’re Actually Using
If the difference between brokerage cash, a bank sweep, and SIPC-covered securities was not obvious before this page, you’re exactly the reader I write for.
- Know when FDIC coverage actually begins—and when it doesn’t.
- Understand what SIPC protects before a scary brokerage headline appears.
- Catch the fine print behind cash sweeps, large balances, and account-safety claims.
Get one practical money decision rule each week.
FDIC vs. SIPC at Webull: The Difference That Matters
FDIC protects bank deposits
The Federal Deposit Insurance Corporation protects qualifying deposits if an FDIC-insured bank fails. The standard limit is $250,000 per depositor, per insured bank, for each ownership category.
FDIC insurance does not cover your stock just because you bought it through an app that also offers an FDIC sweep program. Stocks, bonds and mutual funds are investment products, not insured bank deposits.
SIPC protects customer property at a failed brokerage
The Securities Investor Protection Corporation is different. If an SIPC-member brokerage fails and customer securities or cash are missing, SIPC works through the liquidation process to restore eligible customer property, subject to its limits.
The standard protection is up to $500,000 per customer in each separate capacity, including up to $250,000 for cash. The phrase “separate capacity” matters. Two individual taxable accounts in the same name generally do not create two separate $500,000 limits merely because the app shows two account numbers.
Different capacities, such as an individual account and certain retirement-account registrations can be treated separately under SIPC rules.
FDIC answers a bank-failure question. SIPC answers a brokerage-failure question. Neither answers whether your investment will go down.
How Webull Cash Management Gets FDIC Coverage
Webull Cash Management is the reason a flat “Webull is not FDIC insured” answer is now incomplete.
Under the program, eligible uninvested settled cash can be swept from the brokerage environment to a network of participating FDIC-insured banks. Webull says this structure can provide up to $5 million of FDIC coverage across the network.
But “up to $5 million” is a program ceiling, not a magic new FDIC limit. The underlying FDIC rule is still generally $250,000 per depositor, per insured bank, per ownership category. And the FDIC’s pass-through insurance guidance makes another point people miss: your swept deposit at a partner bank can be aggregated with other deposits you already own at that same bank in the same ownership category.
So if Webull sends $250,000 of your cash to Bank A and you already have $100,000 of single-owner deposits at Bank A, you should not assume all $350,000 is separately insured just because one piece arrived through a brokerage sweep.
Before relying on the $5 million number, check four things
- Are you actually enrolled in Cash Management? Webull says cash that is not enrolled in the program remains under SIPC protection rather than FDIC sweep coverage.
- Has the cash been swept to a participating bank? FDIC insurance attaches to the qualifying deposit at the insured bank, not merely to a cash balance displayed in an app.
- Which partner banks hold your money? Your other deposits at the same banks can affect available coverage.
- Does the ownership and recordkeeping support pass-through coverage? The FDIC requires the necessary agency/custodial relationship and records for pass-through treatment.
For a modest cash balance, this may be mostly academic. For a seven-figure cash balance, it is not. I would look at the actual sweep allocation before treating the marketing maximum as my personal insured amount.
How SIPC Protects a Webull Brokerage Account
Webull Financial LLC is a SIPC member. If the brokerage fails, the first objective in a liquidation is generally to return customer securities and cash that are properly recorded as customer property. SIPC coverage becomes especially important when eligible customer property is missing.
This is why I do not tell someone with a $600,000 stock portfolio, “You have $100,000 uninsured.” That imports a bank-deposit mental model into a brokerage problem.
If your brokerage records accurately show 2,000 shares of a stock and those shares are available in custody, the issue is normally transferring or returning the customer property—not writing you an insurance check equal to the market value of the account. SIPC limits matter when there is a shortfall in eligible customer property.
And there is no protection from an investment being a lousy investment. If a stock falls 60%, neither SIPC nor FDIC restores the loss. That is market risk.
Webull’s Excess SIPC Coverage Depends on the Clearing Arrangement
This is one of the biggest factual repairs to the older version of this page. You may still find articles repeating one Apex excess-insurance number as though every Webull securities account has the same arrangement. Webull’s current disclosures describe two different excess-SIPC structures.
| Webull clearing arrangement | Current disclosed excess-SIPC terms |
|---|---|
| Securities accounts under Webull’s omnibus clearing relationship with Apex | Webull says its Lloyd’s policy has a $100 million aggregate limit, a $1.9 million maximum for any one customer’s cash, and no per-account sublimit for securities positions. |
| Securities accounts fully disclosed to the clearing firm | Webull says Apex’s additional policy has a $150 million aggregate limit, with maximums of $37.5 million for one customer’s securities and $900,000 for one customer’s cash. |
Those are aggregate policy limits and sublimits, not promises that every loss up to those numbers will be reimbursed. Excess SIPC generally sits behind standard SIPC protection and is still about missing eligible customer property—not investment performance.
If I had a very large account and the excess coverage materially affected my comfort level, I would verify which clearing arrangement applies to my account instead of relying on an old article, an infographic, or a remembered number.
What Webull Insurance Does Not Protect You From
FDIC and SIPC are valuable protections. They are also narrower than the word insured makes them sound.
- Market losses: If your investments fall in value, SIPC does not replace the decline.
- Every cyber or fraud loss: Webull says it uses security controls and monitoring, but its own disclosures acknowledge cybersecurity risk. FDIC and SIPC are not universal identity-theft or account-takeover insurance.
- Immediate access: A financial institution can be legitimate and insured while transfers, trading, settlement, verification, or a liquidation process still takes time. Webull itself warns that system and market conditions can affect account access and execution times.
- Futures accounts: Webull states that futures accounts are not protected by SIPC.
- Every product carrying the Webull name: Webull Financial, Webull Advisors, Webull Futures and Webull Pay are not one interchangeable legal bucket. Product and entity matter.
That is why “Is Webull safe?” is a bigger question than “Is Webull FDIC insured?” Insurance is one layer of safety. It is not the whole answer.
Is Webull Safe and Legit? What Regulation Proves—and What It Doesn’t
Webull Financial LLC is a legitimate U.S. broker-dealer. It is registered with the SEC and is a member of FINRA and SIPC. That is meaningful: it places the securities business inside the U.S. broker-dealer regulatory framework.
But “registered” is a floor, not a recommendation. It does not mean the government endorses Webull, promises you will like the platform, guarantees uninterrupted access, or protects you from bad investment decisions.
Is it safe to give Webull your Social Security number and ID?
The request itself is normal for a U.S. brokerage account. FINRA’s Customer Identification Program notice explains that firms must obtain identifying information when opening accounts, including a taxpayer identification number for U.S. customers, and may ask for a driver’s license or other identifying documents.
That answers why the brokerage asks. It does not turn data security into a nonissue. Use the official Webull app or site, use a unique password, enable the available account-security controls, and treat unexpected requests for credentials or codes as suspicious.
Is Webull Safe for More Than $500,000?
There is no useful one-number answer because the right question changes with the asset.
Michael’s Large-Balance Rule
- Large securities balance? Check account registration, standard SIPC capacity, which excess-SIPC clearing arrangement applies, and whether you are comfortable with operational concentration at one brokerage.
- Large cash balance? Check whether the cash is in Cash Management, where the sweep banks are, how much is at each bank, and what other same-category deposits you already hold there.
- Large balance because you’re about to invest? Do not confuse protection from institution failure with protection from the investment you are about to make.
Spreading assets across firms can sometimes reduce operational concentration or simplify your comfort level, but I would not do it mechanically just to “stay under $500,000.” First understand what the $500,000 SIPC figure actually applies to.
My Bottom Line on Webull Account Safety
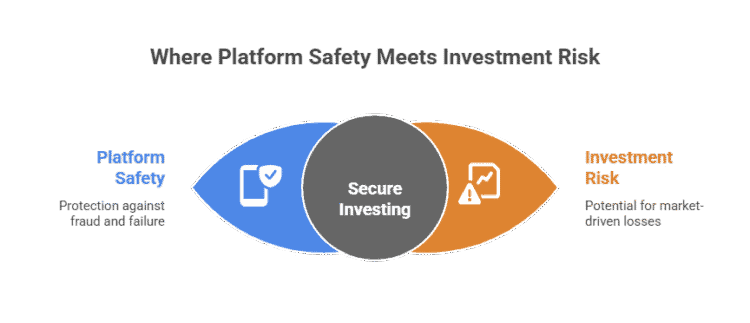
Yes, Webull Financial is a legitimate regulated brokerage with SIPC protection for eligible securities accounts. And yes, eligible cash in Webull Cash Management can receive FDIC insurance after it is swept to participating insured banks.
But I would not stop at either sentence. Before putting a meaningful amount of money anywhere, I want to know exactly what I own, who has custody of it, what legal entity I am dealing with, and which protection applies if that entity fails.
For Webull, that means:
- Use FDIC thinking for qualifying deposits actually swept to partner banks.
- Use SIPC thinking for eligible securities and brokerage cash at Webull Financial.
- Use the applicable excess-SIPC disclosure for very large securities accounts rather than assuming one Apex limit applies to everyone.
- Use security and operational controls for the separate risks of account takeover, fraud, transfer problems and access delays.
Safety gets much easier to judge once you stop asking one insurance question about four different risks.
Frequently Asked Questions About Webull FDIC and SIPC Coverage
Is money in Webull FDIC insured?
Not all of it. Securities in a Webull brokerage account are not FDIC-insured deposits. Eligible settled cash enrolled in Webull Cash Management can be swept to participating FDIC-insured banks, where Webull says the program can provide up to $5 million in FDIC coverage across the bank network, subject to normal FDIC limits and conditions.
What happens if Webull goes bankrupt?
For a Webull Financial securities account, customer property would be handled through the brokerage-failure process. SIPC protects eligible missing securities and cash up to its limits and works through the liquidation process when needed. The goal is not to insure the market value of your portfolio; it is to restore eligible customer property that should be there.
Does SIPC cover more than $500,000 at Webull?
Standard SIPC protection is generally up to $500,000 per customer in each separate capacity, including a $250,000 cash limit. Webull also discloses excess-SIPC coverage, but the terms differ according to the applicable clearing arrangement. Do not treat the excess policy as market-loss insurance.
Is Webull Cash Management the same as a bank account?
No. Cash Management is a brokerage cash-sweep program. Eligible cash is moved to participating FDIC-insured banks. The FDIC insurance comes from the deposit at those banks, not because Webull Financial becomes a bank.
Is Webull safer than Robinhood or Fidelity?
This page does not rank brokerages. SIPC membership is a baseline protection shared by many U.S. brokers, while cash-sweep programs, excess insurance, security controls and operational practices can differ. Compare the exact account and protection arrangement rather than choosing from one insurance acronym.
