

FDIC insurance protects eligible bank deposits if an FDIC-insured bank fails—but the famous $250,000 limit is not a simple “per account” cap. The standard insurance amount is $250,000 per depositor, per insured bank, for each account ownership category.

That last phrase, ownership category, is where most of the confusion lives. Splitting $600,000 among checking, savings, and CDs in your name at the same bank does not create three separate $250,000 limits.
But legitimately using different ownership categories, different insured banks, or properly structured trust accounts can increase total coverage.
And in 2026 there is another wrinkle worth understanding: when a fintech, brokerage cash account, or other nonbank app says your cash may be FDIC-insured, you still need to know which insured bank actually holds the deposit and whether the pass-through insurance requirements are met. The FDIC does not insure the nonbank company itself.
Quick Answer
FDIC insurance covers eligible deposits at an FDIC-insured bank, including checking accounts, savings accounts, money market deposit accounts, and certificates of deposit. The standard limit is $250,000 per depositor, per insured bank, per ownership category. Stocks, bonds, mutual funds, crypto assets, annuities, life insurance, and safe-deposit-box contents are not FDIC-insured. If your balances are complicated, use the FDIC’s EDIE calculator instead of guessing.
I spent years answering versions of the same question across a desk: “Is my money safe if the bank fails?” The part I would pay the most attention to is not the logo on the bank’s front door. It is whether your specific dollars are sitting in an insured deposit, at the bank you think they are, in the ownership category you think they are.
Key Takeaways Ahead
What FDIC Insurance Protects—and What It Does Not
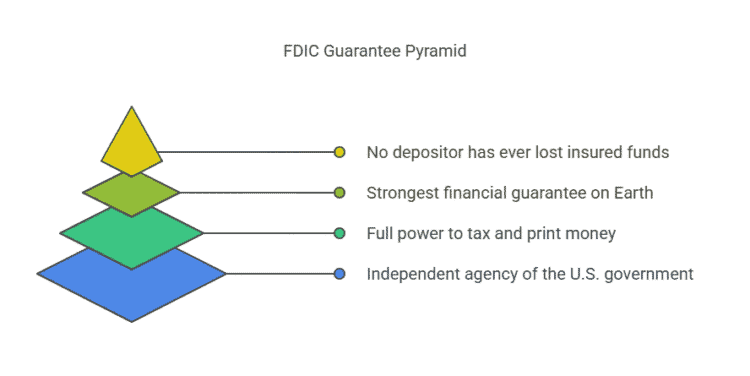
The Federal Deposit Insurance Corporation is an independent federal agency created in 1933. FDIC deposit insurance applies automatically when you place money in an eligible deposit account at an FDIC-insured bank. You do not buy a separate policy or pay the FDIC a premium.
The FDIC says no depositor has lost a penny of insured deposits since federal deposit insurance began in 1934. That guarantee applies to eligible deposits up to the applicable insurance limits—not to every financial product sold by a bank.
| Usually FDIC-insured deposits | Not FDIC-insured |
|---|---|
| Checking accounts | Stocks and bonds |
| Savings accounts | Mutual funds |
| Money market deposit accounts | Crypto assets |
| Certificates of deposit (CDs) | Annuities and life insurance |
| Certain bank-issued official items | Municipal securities and safe-deposit-box contents |
The FDIC’s current financial-products coverage guide makes the boundary explicit. Buying an investment through an FDIC-insured bank does not turn the investment itself into an insured deposit.
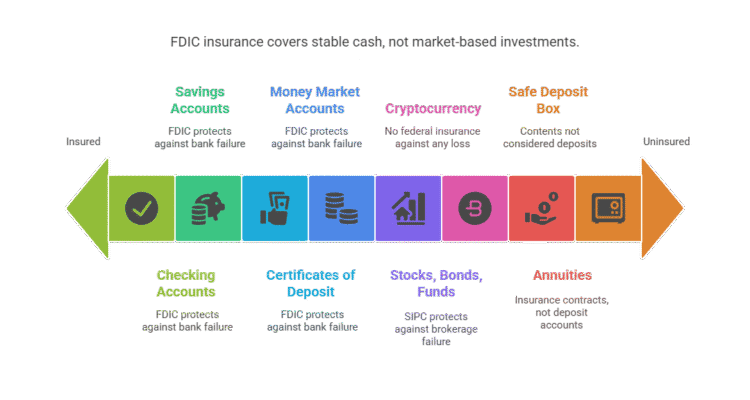
If you are comparing bank protection with brokerage protection, my guide to SIPC insurance coverage limits explains the very different job SIPC performs. Neither FDIC nor SIPC protects you from ordinary market losses.
How the $250,000 FDIC Insurance Limit Actually Works
The standard insurance amount is $250,000 per depositor, per FDIC-insured bank, per account ownership category, including principal and accrued interest through the date a bank closes.
Common Mistake
Checking, savings, and CDs are deposit products—not separate FDIC ownership categories. If you alone own $200,000 in checking, $200,000 in savings, and $200,000 in CDs at the same bank, those three balances generally aggregate in the single-account category. You do not get $750,000 of insurance simply because you used three product types.
This exact misunderstanding shows up in current consumer discussions: people often assume the FDIC limit resets when the account type changes. It does not. The legal ownership category is what controls the insurance bucket.
Example: $600,000 split among checking, savings, and CDs
Suppose Maria has $200,000 in checking, $200,000 in savings, and $200,000 in CDs, all solely in her name at one FDIC-insured bank. The three balances total $600,000 in the same single-account ownership category. Her standard coverage in that category is $250,000. The remaining amount would be uninsured unless another valid ownership category or another insured bank changes the calculation.
That is why the FDIC’s Electronic Deposit Insurance Estimator (EDIE) is more useful than trying to memorize combinations. EDIE calculates coverage from the actual owners, banks, account registrations, and beneficiaries you enter.
FDIC Ownership Categories: Where Extra Coverage Comes From
Different ownership categories can receive separate insurance at the same bank when the deposits genuinely qualify for those categories. The most common categories for individuals and families include single accounts, joint accounts, certain retirement accounts, and trust accounts.
- Single accounts: generally insured up to $250,000 per owner at the same insured bank.
- Joint accounts: each co-owner’s share of qualifying joint deposits is generally insured up to $250,000 at the same insured bank.
- Certain retirement accounts: qualifying self-directed retirement deposits, including IRAs, are generally insured up to $250,000 per owner at the same insured bank.
- Trust accounts: coverage depends on owners and eligible beneficiaries under the FDIC’s current trust-account rule.
Michael’s Take
The useful question is not “How many accounts do I have?” It is “How many insured banks and valid ownership categories are represented by those accounts?” If you cannot answer that from the account title and beneficiary records, do not assume the balance is fully insured.
Years ago, I worked with a couple after a business sale who had a large cash balance concentrated at one local bank. Their first instinct was to scatter the money across a stack of new banks. Before doing that, we mapped who actually owned each deposit and which FDIC category applied. That experience is why I still start with account registration, not the number of accounts.
A correct way a couple could reach $1 million of coverage
Assume Alex and Jordan each hold $250,000 in qualifying single accounts at the same bank and also jointly own $500,000 in qualifying joint accounts. The single-account category could cover $250,000 for Alex and $250,000 for Jordan, while the joint category could cover $250,000 for each co-owner. That is $1 million of total insured deposits at one bank across two distinct ownership categories, assuming the accounts meet the FDIC’s requirements.
Notice what did not happen: the same $500,000 was not counted once as a joint deposit and again as a trust deposit. Every insured dollar belongs to the ownership category created by the actual account registration.
Want Fewer “I Thought That Was Covered” Surprises?
The useful part of deposit insurance planning is mapping the account you actually own—not memorizing one $250,000 headline.
- Plain-English checks for bank, brokerage, and cash-account protection
- Ways to spot ownership-category and beneficiary mistakes before they matter
- Practical money-safety decisions without the financial-industry fog
Get practical account-safety checks like these in your inbox.
Trust Accounts and Beneficiaries: The Rule That Changed in 2024
Trust-account coverage is where older articles and old examples can get people into trouble. Since April 1, 2024, the FDIC has used one combined Trust Accounts category for deposits held in connection with revocable trusts and most irrevocable trusts.
Under the current FDIC trust-account rule, an owner’s trust deposits at the same bank are generally insured at $250,000 for each unique eligible beneficiary, up to a maximum of five beneficiaries—or $1.25 million per owner at one insured bank across the owner’s trust-account deposits. If a trust has multiple owners, the calculation is applied separately to each owner’s interest.
Example: Two Owners, Two Beneficiaries
A qualifying trust deposit with two owners and two unique eligible beneficiaries can have up to $1 million of coverage at one insured bank: 2 owners × 2 beneficiaries × $250,000. That trust coverage is separate from qualifying deposits the owners hold in other ownership categories, such as single or joint accounts.
For informal revocable trust deposits such as payable-on-death accounts, beneficiary designations need to be reflected in the bank’s deposit-account records. A beneficiary written only in a document the bank does not recognize for the account may not produce the coverage you expect.
If the trust itself is part of a larger estate plan, keep the estate-planning question separate from the FDIC calculation. My guide to living trust setup and costs covers the broader trust decision; EDIE is the better tool for the deposit-insurance calculation.
Fintech, Cash Sweep, and Pass-Through FDIC Insurance
A bank account opened directly at an FDIC-insured bank is relatively easy to verify. A nonbank app, brokerage cash-management account, prepaid product, or fintech arrangement can add another layer.
The FDIC’s current guidance on banking with third-party apps says nonbank companies themselves are never FDIC-insured. If a nonbank company actually places your money at an FDIC-insured bank and the required ownership records and other conditions are satisfied, the funds may qualify for pass-through deposit insurance if that insured bank fails.
Pass-through insurance is not a special extra ownership category. It is a way for the FDIC to recognize the underlying owner of funds held at a bank through a third party. The FDIC also makes an important limitation clear: deposit insurance does not protect you from the insolvency or bankruptcy of the nonbank intermediary itself.
Do Not Stop at the Words “FDIC Insured”
For a fintech or cash-sweep product, identify the actual FDIC-insured partner bank or banks, read when your funds become deposits at those banks, and understand who maintains the records connecting the pooled account back to you. Then use FDIC BankFind to verify the bank itself.
This distinction is exactly why readers get tangled up comparing brokerage cash sweeps, money-market funds, FDIC coverage, and SIPC. If you use Webull specifically, my updated guide to whether Webull is FDIC insured separates its cash-management deposits from brokerage securities and other cash.
What Happens to Your Money When a Bank Fails?
Bank failures still happen. The FDIC lists two insured-bank failures in 2026 through September 2: Metropolitan Capital Bank & Trust in January and Community Bank and Trust – West Georgia in May.
When an insured bank fails, the FDIC usually resolves insured deposits by arranging for another insured bank to assume them or by paying depositors directly. According to the FDIC’s payment-to-depositors guidance, federal law requires insured-deposit payments as soon as possible, and the FDIC’s goal is generally within two business days. Accounts requiring supplemental documentation—such as certain trust or brokered deposits—can take longer while coverage is determined.
Money above your insured limit is different. The uninsured portion becomes a claim against the receivership. You may recover some of it as the failed bank’s assets are liquidated, but the FDIC does not promise that uninsured balance dollar-for-dollar.

What This Means to You
FDIC insurance is designed to remove the bank-failure risk from your insured deposits. It does not remove every risk around your money. Fraud, investment losses, a failed nonbank intermediary, and balances above the insurance limits are different problems with different protections.
How to Check Your FDIC Coverage in 3 Steps
You can do a useful first-pass check in about 15 minutes. The goal is not to become a deposit-insurance lawyer. The goal is to stop guessing.
- Verify the bank. Use the FDIC’s BankFind Suite to confirm that the institution actually is FDIC-insured. If you use a fintech or sweep program, identify each partner bank the service says may hold your deposits.
- List owners, beneficiaries, balances, and account registrations. Do not sort only by checking, savings, and CDs. Write down the legal ownership category each account appears to use.
- Run the accounts through EDIE. Use the official FDIC EDIE calculator for the actual coverage calculation, especially when joint owners, retirement deposits, beneficiaries, trusts, or multiple banks are involved.
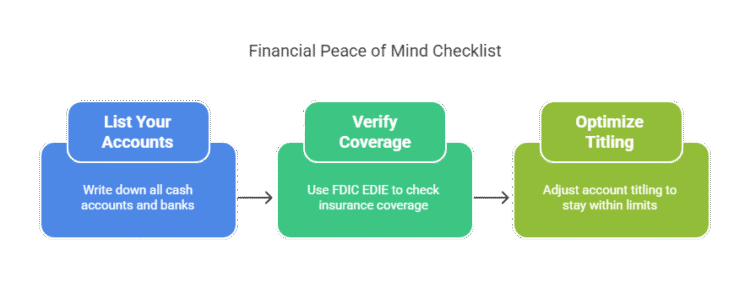
If the result shows uninsured money, you have several legitimate choices: reduce the balance, move part of it to another FDIC-insured bank, use another valid ownership category when it fits your real legal ownership, or use a bank service that places deposits across multiple insured institutions. The right move depends on liquidity, account purpose, taxes, estate planning, and how much operational complexity you want.
What I would not do is change account ownership or add beneficiaries solely to chase a larger insurance number without understanding the legal consequences. Deposit insurance should follow your ownership plan—not quietly rewrite it.
What Changed for FDIC Insurance in 2026?
The core $250,000 standard insurance amount has not changed in 2026. The biggest practical updates are about how consumers identify insured deposits and how the FDIC’s insurance system is positioned after the post-2023 rebuilding period.
- The Deposit Insurance Fund is no longer operating under its Restoration Plan. The FDIC says the reserve ratio exceeded the statutory 1.35% minimum as of June 30, 2025, and beginning in the third quarter of 2025 the agency stopped operating under that plan. The designated reserve ratio for 2026 is 2.00%.
- Digital FDIC signage rules were updated in January 2026. The FDIC revised requirements for digital deposit-taking channels and ATMs to make it clearer when consumers are dealing with an insured depository institution and when a product is not an insured deposit.
- Third-party account clarity matters more, not less. The FDIC continues to emphasize that a nonbank company’s relationship with an insured bank does not make the nonbank company itself FDIC-insured.
The practical lesson is simpler than the regulatory timeline: do not wait for a higher federal limit or assume every cash-like product carries the same protection. Verify the bank, the deposit, and the ownership category you have today.
FDIC Insurance FAQ
Does FDIC cover $500,000 in a joint account?
A qualifying joint account with two co-owners can generally be insured up to $500,000 in total in the joint-account category because each co-owner can receive up to $250,000 of coverage for that person’s share of qualifying joint deposits at the same bank. Other joint deposits held by the same owners at that bank are aggregated for the calculation.
Is it safe to keep more than $250,000 at one bank?
It can be fully insured when the deposits legitimately qualify for separate FDIC ownership categories. It can also be partly uninsured when too much money sits in one category. Use EDIE with the actual account registrations rather than assuming that more accounts mean more coverage.
Are CDs separately insured from checking and savings accounts?
Not simply because they are CDs. Deposits are combined by ownership category at the same insured bank. A CD, savings account, and checking account owned solely by the same person generally aggregate in that person’s single-account category.
Does FDIC insurance protect money in a fintech app?
A nonbank fintech company is not itself FDIC-insured. Funds may qualify for pass-through FDIC insurance after they are placed at an FDIC-insured bank and the applicable ownership-record and other requirements are satisfied. FDIC insurance does not protect against the fintech company’s own insolvency or bankruptcy.
How quickly do you get insured money back after a bank failure?
The FDIC says federal law requires payment of insured deposits as soon as possible and its goal is generally within two business days. Accounts that require additional ownership or trust documentation can take longer while the insurance determination is completed.
Bottom Line: FDIC Insurance Is About Ownership, Not the Number of Accounts
The $250,000 rule is easy to repeat and easy to misunderstand. FDIC insurance is not $250,000 for every checking account, savings account, and CD you open. It is $250,000 per depositor, per insured bank, per ownership category.
That one distinction solves most of the puzzle. From there, joint ownership, retirement deposits, trust beneficiaries, multiple banks, and pass-through arrangements can change the result—but only when the legal ownership and records actually support the coverage.
If you remember one thing, make it this: FDIC insurance is a legal-and-recordkeeping system, not a sticker. Map the dollar to the real insured bank and the real ownership category, then verify the result with EDIE. That is a much safer habit than trying to outsmart a $250,000 headline.
Sources
- Federal Deposit Insurance Corporation: Deposit Insurance
- Federal Deposit Insurance Corporation: Trust Accounts
- Federal Deposit Insurance Corporation: Banking With Third-Party Apps
- Federal Deposit Insurance Corporation: Are My Deposit Accounts Insured?
- Federal Deposit Insurance Corporation: Payment to Depositors
- Federal Deposit Insurance Corporation: 2026 Bank Failures in Brief
- Federal Deposit Insurance Corporation: Deposit Insurance Fund Assessment Regulations
- Federal Deposit Insurance Corporation: 2026 Official Signs and Advertising Rule
