

A net worth statement is your personal balance sheet: list what you own, list what you owe, then subtract your liabilities from your assets. The arithmetic is easy. The useful part is seeing everything in one place so you can spot what is actually helping or hurting your financial progress.
After nearly three decades in financial planning, this is still one of my favorite financial “X-rays.” Not because a single net worth number tells me whether someone is doing well, but because a well-built statement shows where the next money decision deserves attention.
Quick Answer
A net worth statement equals total assets minus total liabilities. Use realistic values for what you own and current outstanding balances for what you owe. Build the statement using one valuation date, then update it consistently so you can compare the trend over time. If you only want the number quickly, use my net worth calculator; this guide is for understanding what belongs on the statement and what the result actually tells you.
On This Page
- Key Takeaways Ahead
- What Is a Net Worth Statement?
- Step 1: List Your Assets — What You Own
- Step 2: List Your Liabilities — What You Owe
- Step 3: Calculate Your Net Worth
- Net Worth Reality Check
- Step 4: Choose a Net Worth Tracking Method You Will Actually Maintain
- Step 5: Read What Your Net Worth Statement Is Telling You
- Step 6: Turn Your Net Worth Statement Into a Next Action
- Your Net Worth Statement Is a Diagnostic, Not a Judgment
- Sources
Key Takeaways Ahead
What Is a Net Worth Statement?
Investor.gov describes a net worth statement the same basic way: what you own are your assets, what you owe are your liabilities, and the difference is your net worth.
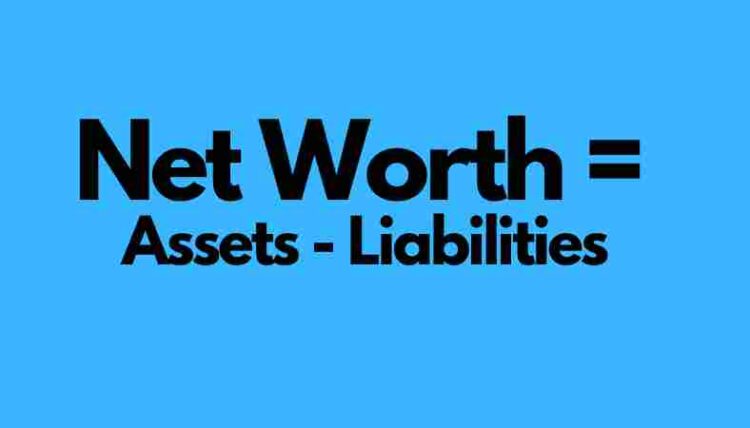
Net worth = assets − liabilities.
That makes net worth different from income. Income is a flow; net worth is a snapshot. Someone can earn a large salary and still have a weak balance sheet if debt and spending absorb everything. Someone with a more modest income can build a strong balance sheet over time by consistently saving, investing and controlling debt.
Same Statement, Different Questions
Nora, early career: “How much are student loans holding back my progress?” Mike, mid-career: “Is my wealth growing faster than my debt?” Rachel, near retirement: “How much of my net worth is actually liquid or investable?” The formula is the same. The decision the statement helps you make changes with your life.
Watch: A Quick Net Worth Statement Overview
If you prefer a visual overview first, this short slideshow walks through the basic idea. Then keep reading for the details that determine whether your statement is actually useful.
Net Worth = What You Own − What You Owe
Use one date for the entire statement. If your checking balance is from today, your mortgage balance is from last month and your home value is from two years ago, you do not really have a snapshot. You have a collage.
The goal is not false precision. It is a consistent, honest estimate you can repeat later.
Step 1: List Your Assets — What You Own
An asset belongs on your net worth statement when you own it and can assign a reasonable current value to it. Use current estimated value, not what you originally paid and not what you hope it will someday be worth.
| Asset category | Examples | Value to use |
|---|---|---|
| Cash and equivalents | Checking, savings, money market accounts, CDs | Current account balance |
| Investments | Brokerage accounts, stocks, bonds, mutual funds, ETFs | Current market value |
| Retirement accounts | 401(k), 403(b), IRA and similar accounts | Current account balance |
| Real estate | Primary home, rental property, vacation property | Reasonable current market estimate |
| Vehicles and valuable property | Cars, boats, valuable collectibles or jewelry | Realistic resale value, not purchase price |
| Business and other assets | Business ownership, money owed to you, accessible cash value of permanent life insurance | A supportable current value |
Michael’s Valuation Rule
Do not make yourself richer on paper because you are emotionally attached to an asset. If you would not reasonably receive that amount in a sale today, it is probably too high for a useful personal statement.
For personal property, I would rather see a conservative number than a fantasy garage-sale number. A car has a resale value. A box of ordinary household items usually does not deserve line-by-line treatment. Business interests, closely held stock, collectibles and other hard-to-price assets may require a real valuation if the number is material.
The Asset Mistake That Makes a Statement Look Better Than Reality
Do not confuse valuable with liquid. A paid-off house may add substantially to net worth, but you cannot use a bedroom to pay an emergency bill. Total net worth answers one question; available cash and investable assets answer another.
Step 2: List Your Liabilities — What You Owe
Liabilities are the amounts you currently owe. Use the current outstanding or payoff balance, not the original amount you borrowed and not the monthly payment.
Common Liabilities to Include
- Mortgage and home-equity debt: current mortgage, HELOC and home-equity loan balances.
- Vehicle and other secured loans: the amount still owed on cars, boats, RVs or other financed property.
- Credit-card balances: the actual outstanding balance, not the minimum payment shown on the statement.
- Student and personal loans: federal or private student loans, personal loans and lines of credit.
- Other amounts currently owed: medical debt, tax debt and other material obligations that are truly outstanding.
Common Mistake: Listing the Payment Instead of the Balance
A $300 monthly car payment is not a $300 liability. If the loan balance is $14,000, the statement needs the $14,000. The same mistake happens with credit cards and student loans. Log in and use the actual current balance.
Why the Debt Side Matters So Much
I have seen people focus almost entirely on the asset column because it feels better. That is like looking at a boat’s sails and ignoring the hole in the hull. A growing investment account does not erase an expensive debt balance. Put both on the same page and the tradeoff becomes much harder to avoid.
Step 3: Calculate Your Net Worth
Once the list is complete, the calculation takes one line:
Total Assets − Total Liabilities = Net Worth
Worked Example
Mike lists $850,000 of total assets and $300,000 of total liabilities. His net worth is $550,000. The calculation is $850,000 − $300,000 = $550,000.
The calculator below does the arithmetic and also separates the result into useful views such as liquid net worth, investable net worth, home equity and debt-to-assets. Those extra views are exactly why I do not want you to stop at the headline number.
Net Worth Reality Check
See what you own, what you owe, where your wealth actually lives, and how much is liquid or investable.
What you own
What you owe
Enter a few balances to see your financial snapshot.
What If Your Net Worth Is Negative?
A negative net worth means your liabilities currently exceed your assets. It does not tell you your worth as a person, and it does not make the statement useless. Investor.gov specifically notes that people should not be discouraged by a negative net worth and recommends updating the statement over time.
This is where tracking becomes valuable. One recent Reddit discussion I reviewed was from someone who had avoided net-worth tracking because large student loans made the number feel depressing. The useful moment came later, when the household finally crossed into positive territory. That is reader-reality evidence, not a benchmark: the value was seeing the direction change.
Your net worth is a snapshot. The trend is the story.
Step 4: Choose a Net Worth Tracking Method You Will Actually Maintain

You do not need sophisticated software. You need a method you will update consistently.
| Method | Best for | Tradeoff |
|---|---|---|
| Spreadsheet | People who want control, custom categories and a permanent history | Manual updating takes discipline |
| Financial aggregation app | People who want account balances pulled together automatically | Privacy, account-linking and pricing vary by service |
| Planner or financial software | Households already working with a professional | More detail than many people need for a simple annual statement |
If you prefer automated account aggregation, Empower Personal Dashboard is one option. The important point is not the brand. It is whether the tool makes the numbers easier to maintain without creating a privacy tradeoff you are uncomfortable with.
Privacy and Security When You Use a Tracking App
- Use a strong, unique password and multi-factor authentication when the service supports it.
- Review what accounts and data the service can access.
- Use the official website or app instead of links from unsolicited messages.
- If you do not want to link accounts, a spreadsheet remains a perfectly valid solution.
Step 5: Read What Your Net Worth Statement Is Telling You
A net worth statement becomes useful when it changes a decision. I look for a few things before I care about the total.
Five Questions to Ask About the Result
- Is the trend improving? One number can move with markets and property values. A series of statements shows whether saving, debt reduction and investment contributions are changing the balance sheet over time.
- How much is liquid? A high net worth concentrated in a home or business can coexist with a weak cash position.
- Which liability is doing the most damage? The statement makes large or persistent debt hard to hide behind income.
- Is one asset dominating the picture? Heavy concentration in a house, one company stock or a business can make the total look stronger than the household’s flexibility.
- What changed since the last statement? Separate market movement from your own behavior. Paying down debt, saving more and adding investments tell a different story than a one-time jump in an asset estimate.
Do Not Turn Net Worth Into a Scoreboard
The Federal Reserve’s Survey of Consumer Finances publishes household net-worth data, and the calculator on this page can show a historical age-group comparison. Use that only for context. The Fed’s data are family-level survey estimates grouped into broad categories, not a personalized target for your household.
I care much more about whether your statement is moving in the right direction for the right reasons. A 30-year-old paying down student debt and building retirement savings can have a lower net worth than an older homeowner with more equity, yet be making exactly the right decisions for that stage of life.
What I Have Seen in Practice
I have worked with good earners who felt as if they were spinning their wheels. Once everything was on one statement, the pattern was visible: too much money tied up in depreciating “stuff,” too much consumer debt, and not enough in the assets that gave them flexibility. The statement did not solve the problem by itself. It made the real problem impossible to miss.
Make the Next Net Worth Check Better
Once you know which line is holding your balance sheet back, the next win is making one smart adjustment before you update it again.
- See whether debt, cash reserves or saving deserves attention first.
- Learn how to read changes in net worth without overreacting to market noise.
- Get practical check-ins that keep the balance-sheet trend moving in the right direction.
Get net-worth, debt-priority and next-money-move ideas from Michael Ryan Money.
Step 6: Turn Your Net Worth Statement Into a Next Action
Do not finish the statement, admire the spreadsheet and close the tab. Circle the one line that most deserves attention.
- If cash is thin: strengthen your emergency buffer so ordinary surprises do not immediately become new debt.
- If high-cost debt is heavy: make debt reduction a priority while keeping enough liquidity to avoid a borrow-payoff-borrow cycle.
- If the balance sheet is stable but growth is slow: review savings and long-term investment contributions.
- If most of your wealth is illiquid: pay attention to cash reserves and investable assets, not just total net worth.
- If you cannot explain the change: compare the current statement with the previous one line by line before making a major adjustment.
Investor.gov recommends updating a net worth statement every year. I like at least an annual review, and I would also rebuild it after a major financial change such as buying or selling a home, taking on substantial debt, receiving a large windfall or entering retirement.
The Net Worth “Aha” Moment
The most useful reaction is not “my number is high” or “my number is low.” It is: “Now I can see what needs to change.” That is why I call the statement a financial X-ray. The picture matters because it tells you where to look next.
Your Net Worth Statement Is a Diagnostic, Not a Judgment
A good net worth statement gives you clarity without pretending one number can summarize your financial life. List the assets honestly. List every real liability. Use one valuation date. Do the subtraction. Then look past the total.
What changed? What is liquid? Which debt is dragging? Which asset is doing too much of the work? What one decision could make the next statement stronger?
That is the real payoff: not knowing where you rank, but knowing what to do next.
