Do not recycle your Medicare Annual Notice of Change without reading it.
For your Medicare ANOC 2027 review, check money, medicine and medical care against the way you actually use your plan. Verify your prescriptions, pharmacies and providers before deciding whether to keep a continuing plan or compare alternatives.
That thick Medicare envelope sitting on the counter is easy to ignore. It looks like a pile of fine print telling you that your plan changed a few dollars here and there.
Sometimes that is all it is.
Sometimes the premium barely moves while a prescription changes tiers, a specialist costs more, or a hospital you rely on is no longer in your plan’s network.
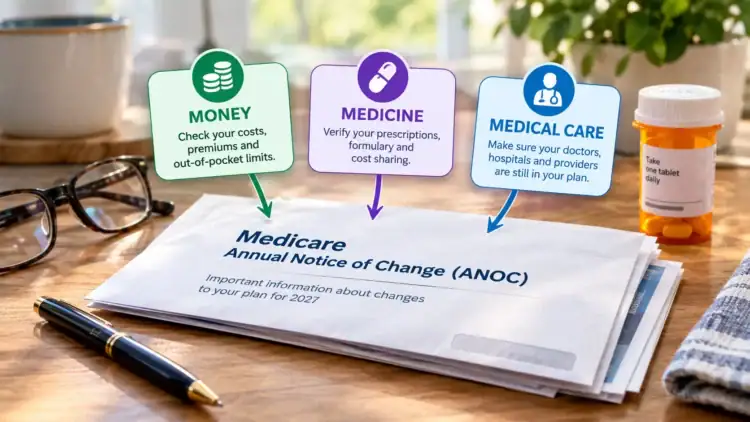
You do not need to read the whole document tonight. Start with three things: Money. Medicine. Medical care.
What will this plan actually cost you in 2027?
Check the premium, deductibles, copays, coinsurance, and Medicare Advantage out-of-pocket maximum.
Will your prescriptions still work financially?
Check the formulary, drug tier, cost sharing, restrictions, and preferred pharmacy status.
Can you still use the doctors and facilities you rely on?
Check doctors, specialists, hospitals, networks, referrals, and prior authorization rules.
Show the quick check
- Money: Compare the 2027 premium, deductibles, copays, coinsurance, and Medicare Advantage out-of-pocket maximum with 2026.
- Medicine: Check every regular prescription for coverage, tier, restrictions, and preferred pharmacy status.
- Medical care: Verify the doctors, specialists, hospitals, and facilities you rely on in your exact 2027 plan and network.
- Deadline: Medicare Open Enrollment runs October 15 through December 7.
- Decision rule: If one of the three areas changes materially, compare plans before Open Enrollment ends.
If you are in a Medicare Advantage Plan or Medicare drug plan, your plan sends an Annual Notice of Change, usually called an ANOC, each fall. It tells you about changes taking effect January 1.
If the ANOC changes something important, use the Medicare Open Enrollment + IRMAA Checklist to compare the coverage deadline with the separate year-end income decisions that can affect later surcharges.
Medicare & You 2027 says Medicare Advantage plans send a printed or electronic ANOC by September 30. Open Enrollment runs October 15 through December 7, 2026, for coverage starting January 1, 2027.
If September 30 passes and you still do not have it, contact your plan. Do not assume that no letter means no changes.
On This Page
- 1. Check what your Medicare plan will cost in 2027
- 2. Check every prescription in your Medicare ANOC
- 3. Check your doctors, hospitals, and Medicare Advantage network
- Do the five-minute Medicare ANOC check now
- What if everything in your ANOC looks fine?
- What if you never received your Medicare ANOC?
- The Medicare ANOC mistake I would avoid
- Frequently asked questions
- Official sources
- How We Verified This
1. Check what your Medicare plan will cost in 2027
Start with the boring numbers because they are easy to compare and easy to underestimate.
Look at the monthly premium, deductible, copays, coinsurance, and the plan’s maximum out-of-pocket limit if you have Medicare Advantage. Then compare them with 2026.
A premium that barely moves can still hide higher specialist copays, hospital costs, imaging costs, or other increases that matter far more to someone who actually uses the plan.
Imagine your monthly premium rises only $4. At first glance, that looks like good news.
But your specialist copay rises from $40 to $60. You see that specialist eight times a year. One regular prescription moves to a more expensive tier. Your preferred hospital is no longer in the same network position.
The premium adds $4 × 12 = $48 for the year. The specialist visits add ($60 − $40) × 8 = $160. That is $208 more before prescription or other care changes.
The $4 premium increase was never the real change.
That is why I would not judge a plan by the premium alone. In financial planning, I saw people naturally gravitate toward the easiest number on the page. The easier number was not always the one determining what the year actually cost them.
Your plan premium is not your whole Medicare bill. The separate Medicare Part B premium and IRMAA calculation deserves its own check; do not treat a low plan premium as your total monthly cost.
Write down these five numbers:
- 2027 monthly premium
- Medical deductible, if any
- Drug deductible, if any
- Specialist and hospital cost sharing
- Maximum out-of-pocket limit for Medicare Advantage
The useful question is not, “Did my premium go up?” It is, “What would this plan cost me if I use Medicare the way I actually use it?”
2. Check every prescription in your Medicare ANOC
This is where I would slow down.
A plan can look almost identical until one medication you rely on changes tiers, gets a new restriction, or costs more at the pharmacy you normally use.
For every regular prescription, check the exact drug, dose and form on the plan’s 2027 formulary, its covered-drug list. Check the tier, the drug’s cost-sharing category, plus copays, coinsurance, prior authorization, step therapy and quantity limits. Confirm preferred pricing at your actual pharmacy location, not just the chain’s name.
Do not stop after seeing the drug’s name on the formulary. Covered does not necessarily mean covered the same way.
One cash-flow option worth knowing: The Medicare Prescription Payment Plan lets you spread your out-of-pocket costs for Part D-covered prescriptions over the remaining months of the calendar year. Instead of paying those covered costs at the pharmacy, you get bills from your health or drug plan. There is no participation fee, but it does not lower your total drug costs.
It may ease the strain of a costly prescription early in the year, but monthly bills can change as more drugs are filled. Compare your actual 2027 formulary and total plan costs first; this payment option changes when you pay, not whether a plan is the right one for your medicines. If you qualify for Extra Help, check that assistance separately.
Want to use the Medicare Prescription Payment Plan? Visit your Medicare health or drug plan’s website or call the plan to enroll. You can join during the year, but starting earlier gives you more months to spread out your covered prescription costs. If you switch plans, participation in the old plan’s payment option ends; contact the new plan to enroll again. Any remaining balance with the old plan is still owed. Medicare explains enrollment and plan changes.
A replacement Medicare Advantage plan may not include drug coverage. Do not assume you can simply add a standalone Part D plan.
With a Medicare Advantage HMO or PPO, you generally cannot keep the plan and add separate Part D. Enrolling in standalone Part D can disenroll you from Medicare Advantage and return you to Original Medicare. Medical Savings Account (MSA) plans and Private Fee-for-Service (PFFS) plans without drug coverage generally permit separate Part D, as do certain Medicare Cost Plans.
Before switching: Check whether the exact replacement plan includes drug coverage; whether its type permits separate Part D; whether your prescriptions and pharmacies fit; and whether employer, union, retiree benefits, creditable coverage or a Part D late-enrollment penalty could be affected.
If you have employer or retiree benefits, ask that benefits administrator first. Verify uncertain combinations with the plan or 1-800-MEDICARE before enrolling.
- Is it still covered?
- Did the tier change?
- Did the copay or coinsurance change?
- Is prior authorization new?
- Is step therapy new?
- Is your pharmacy still preferred?
In Medicare’s Plan Compare tool, compare the annual drug-and-plan-premium estimate using your complete medication list, doses, quantities, refill frequency and pharmacies you would actually use. Check monthly costs and uncovered-drug warnings too. Do not add premiums or deductibles twice if the estimate already includes them. This estimate is not a prediction of every Medicare Advantage medical bill.
What does the $2,400 Medicare Part D number mean in 2027?
For 2027, the Medicare Part D annual out-of-pocket threshold is $2,400 for covered Part D drugs.
Under Medicare’s Part D cost guidance, qualifying spending counts toward this threshold. It is not a cap on premiums, noncovered drugs or all medical bills, and it does not necessarily mean you personally pay $2,400.
- You fill covered Part D prescriptions during the year.
- Qualifying out-of-pocket drug costs accumulate, including certain payments made on your behalf.
- When those eligible costs reach the $2,400 threshold, you enter the catastrophic phase.
- In that phase, you owe no additional cost sharing for covered Part D drugs for the remainder of the year.
But the $2,400 threshold does not guarantee that a particular medication is covered, stays on the same tier, or keeps the same plan rules.
- What you pay for this fill
- The cash leaving your wallet for that prescription today.
- What your Part D plan credits
- The qualifying drug spending recorded under your plan’s rules.
A lower cash quote alone does not tell you which route costs less for the year. A cash purchase does not automatically count toward the Part D out-of-pocket threshold. Before choosing cash, ask your plan whether the purchase qualifies, how to submit the claim and what amount would count. Keep the receipt. CMS’s cash-purchase and reimbursement rules distinguish a purchase from a qualifying claim recorded by the plan.
If a needed drug is removed, restricted or moves to a higher tier, ask the plan and your prescriber about the right request. A formulary exception asks for coverage of a nonlisted drug or waiver of a coverage rule. A tiering exception seeks lower cost sharing for an eligible higher-tier drug; not every drug or tier qualifies. Your prescriber must support the medical reasons, and approval is not guaranteed. CMS’s explanation of drug exceptions spells out the distinction.
If one medication that matters to you changes significantly, that alone can be enough reason to compare plans during Open Enrollment.
3. Check your doctors, hospitals, and Medicare Advantage network
If you have Medicare Advantage, do not stop at the premium and drug list.
Check the providers and facilities you actually rely on. That may include your primary care doctor, specialists, hospital system, rehabilitation facility, therapy provider, home health provider, or another recurring source of care.
Also look for changes to referrals, prior authorization, service areas, benefits, and other plan rules that affect access.
If you have Medicare Advantage, the more useful question is whether the doctor, hospital, or facility participates in your exact plan and network for 2027.
- Your primary care doctor
- Specialists you see regularly
- Your preferred hospital system
- Therapy or rehabilitation providers
- Home health or other recurring care
- Any new referral or prior authorization requirements
Provider networks can change during the year too. The ANOC is the place to start, not necessarily the place to stop.
For a doctor, hospital, or facility you consider essential, confirm participation with both the plan and the provider before making an enrollment decision.
Do the five-minute Medicare ANOC check now
You are not trying to become a Medicare expert. You are trying to find the changes capable of affecting your wallet, your prescriptions, or your access to care.
Check each item only after you actually verify it.
What you found / Your next step
- The plan continues, and costs, needed drugs and care access still fit.
- Keeping it may be reasonable. You can still compare alternatives; Open Enrollment does not require switching.
- A cost, needed drug or provider change matters to you.
- Compare 2027 alternatives using your actual drugs, pharmacies and providers. Verify the details before enrolling.
- A notice, drug rule or coverage answer is unclear.
- Ask the plan about its rules, involve your prescriber for an exception, or bring your questions to the State Health Insurance Assistance Program (SHIP) for free Medicare counseling.
What if everything in your ANOC looks fine?
That can be good news. If your plan will continue in 2027, you do not automatically need to switch just because Open Enrollment exists.
But make sure “looks fine” means you checked the things that matter to you, not just the monthly premium on the first page.
If your costs remain acceptable, your prescriptions still work under the plan, and the providers you depend on remain available under terms you are comfortable with, you have answered the three questions this review was designed to answer.
An ending plan is different from ordinary renewal. Read the actual letter for what happens if you do nothing. If an Extra Help notice says Medicare will reassign you to another drug plan, check that assigned plan’s drugs and pharmacies. Assignment does not prove the plan fits your needs. A letter asking you to choose a plan is different. Confirm your notice’s deadline and coverage start date with Medicare or SHIP; do not assume every deadline preserves January coverage.
What if you never received your Medicare ANOC?
Contact your plan. Medicare specifically tells beneficiaries to contact the plan if this notice does not arrive.
You can also use Medicare’s Plan Compare tools to check current 2027 options. If you compared early in October, recheck before enrolling with your current medication and pharmacy list.
Need someone to work through the choices with you? The State Health Insurance Assistance Program (SHIP) offers free, objective, one-to-one Medicare counseling. Bring your ANOC or ending-plan letter, complete medicine list with doses, pharmacies and essential providers. That gives the counselor your actual coverage problem to work on.
The Medicare ANOC mistake I would avoid
After nearly three decades around financial planning, this is exactly the sort of paperwork I saw people put aside because nothing felt urgent yet.
That is what makes the ANOC easy to ignore. The consequence is usually sitting several months away.
Then January arrives and the change is no longer theoretical.
The ANOC is not junk mail. It is your plan telling you, in advance, what it intends to change.
You do not need to memorize it.
Check what you will pay. Check every prescription that matters. Check the doctors and facilities you depend on.
The obvious change is not always the real change.
Hospital and rehab coverage has its own traps. If a hospital stay or rehab is part of your planning, see how Medicare’s three-day SNF rule works. That is a separate coverage check, not something your ANOC alone settles.
Frequently asked questions
When should I receive my Medicare ANOC?
The ANOC arrives in September. Medicare & You 2027 says Medicare Advantage plans send a printed or electronic ANOC by September 30. If you do not receive yours, contact your plan.
When is Medicare Open Enrollment for 2027 coverage?
Medicare Open Enrollment runs October 15 through December 7, 2026. Coverage starts January 1, 2027, provided the plan receives your enrollment request by December 7.
What is the Medicare Part D out-of-pocket threshold for 2027?
The Medicare Part D annual out-of-pocket threshold is $2,400 for 2027. When qualifying costs, including certain payments on your behalf, reach that threshold, you owe no additional cost sharing for covered Part D drugs for the rest of the year.
Does the $2,400 threshold mean all of my prescriptions are covered?
No. The threshold is a Part D cost-protection feature. It does not require every plan to cover every drug or keep a drug on the same tier with the same utilization rules. That is one reason to check the formulary and plan rules in your ANOC.
Does my ANOC show every provider that could leave my network?
The ANOC can alert you to plan and coverage changes, but provider networks can also change during the year. If continued access to a particular doctor, hospital, or facility is important to you, verify participation directly before making an enrollment decision.
Official sources
- Medicare.gov: Plan Annual Notice of Change
- Medicare.gov: Open Enrollment
- CMS: 2027 Medicare Advantage and Part D Rate Announcement
- CMS: Contract Year 2027 Medicare Advantage and Part D Final Rule
How We Verified This
Checked against CMS, Medicare.gov and SHIP sources on October 23, 2026. Verify your own drugs, pharmacy and providers with the exact 2027 plan.
