

If personal finance still feels like a class everybody else somehow took, Cary Siegel’s Why Didn’t They Teach Me This in School? is still one of the easiest places to start. It is short, plain-English, and built around 99 practical money principles instead of one giant financial system.
But there is an important 2026 catch: the habits aged better than some of the instructions.
That distinction is the whole point of this review. I would still hand this book to a true beginner. I just would not tell them to treat every percentage, product choice, or tactical rule from a 2013 book as current financial law.
Show the 30-second version
Quick verdict: Read it if you need a financial starter kit. Skip it if you already budget, save automatically, understand credit, and have a diversified investing plan. The best parts are the simple behaviors; the parts most likely to age are the implementation details.
Check Why Didn’t They Teach Me This in School? on Amazon →
Is "Why Didn't They Teach Me This in School?" Right For You?
Answer a few quick questions to see if this straightforward book by Cary Siegel is the best starting point for your financial journey.
The Tool Gave You Answers. The Newsletter Gives You Moves.
This quiz provides a general guideline. "Why Didn't They Teach Me This in School?" is widely praised for its beginner-friendly approach.
Key Takeaways Ahead
Why Didn’t They Teach Me This in School? Summary
Cary Siegel originally developed the material for his five children as they moved into adulthood. On his official book site, he describes the book as eight lessons built around 99 personal money-management principles, deliberately written as a quick, easy-to-digest guide rather than a technical textbook.
That structure is the book’s biggest strength. You can read a principle in a couple of minutes, understand the point, and decide whether it applies to you.
The book covers the everyday money issues people often encounter before they feel ready for them: budgeting, saving, debt, credit, insurance, investing, employee benefits, major purchases, and basic financial decision-making.
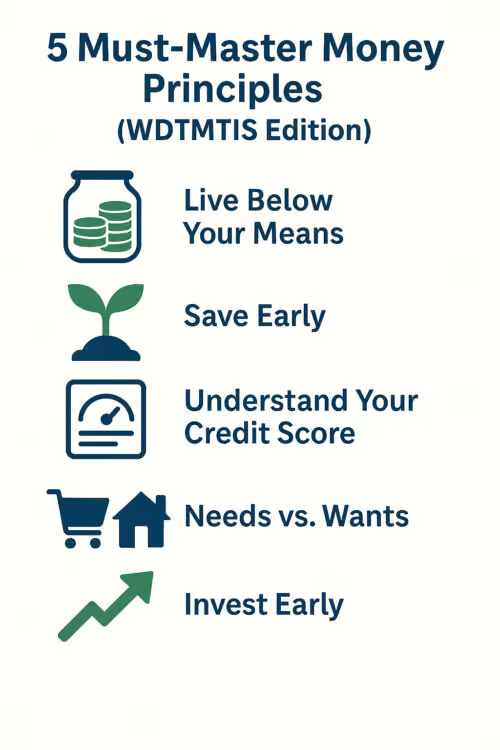
My one-sentence summary would be:
Learn the boring money basics early enough that they never get the chance to become expensive money problems.
If you want broader recommendations instead of one-book analysis, use my best personal finance books for beginners. This page has a narrower job: deciding whether Siegel’s book is still a good starting point and which of its lessons deserve a modern filter.
The 8 Money Lessons That Matter Most
The book contains 99 separate principles, but memorizing 99 rules is not the best way to use it. I would compress the useful material into eight jobs.
1. Spend less than you earn
This is the foundation. It sounds almost too obvious to include, but most downstream money problems are some version of this rule breaking down. Lifestyle creep, revolving credit-card balances, and nonexistent savings all get much harder to fix when spending absorbs every dollar of income.
2. Know where your money goes
A budget is not punishment. It is simply a way to decide where money should go before random spending makes the decision for you. If budgeting is your sticking point, start with my guide to building a spending plan.
3. Build a cash cushion before life tests you
Emergency savings are not exciting, which is probably why they matter. A cash reserve turns a car repair, medical bill, job interruption, or last-minute trip from a financing decision into a cash-flow decision.
If this is the piece you are missing, my emergency-fund guide goes deeper than a book summary should.
4. Understand credit before you need it
The best time to understand your credit report is not the night before a mortgage application. Siegel is right that credit is part of everyday financial life, but current access and monitoring rules matter more than memorizing an old procedure.
5. Avoid turning borrowing into a lifestyle
Debt can be useful, expensive, or both. The durable lesson is not “all debt is bad.” It is that borrowing should solve a deliberate problem rather than quietly fund a standard of living your income cannot support.
6. Protect the plan
Insurance is one of those topics people tend to ignore until the stakes are suddenly real. A beginner does not need to become an insurance expert, but they should understand deductibles, liability, income protection, and which risks would actually damage the household.
7. Start investing without making investing your personality
The book’s instinct toward simple investing is still useful. Most beginners need diversification, reasonable costs, and a process they can stick with—not a hobby built around watching financial television and checking prices six times a day.
8. Learn the terms attached to your paycheck
Employee benefits, taxes, retirement plans, insurance elections, and payroll deductions are where “adult money” becomes real. A first paycheck can teach more finance in five minutes than a semester of vague theory if you know what you are looking at.
What Still Holds Up in 2026
The strongest principles in this book are the ones that describe behavior rather than one specific financial product.
- Live below your means. No financial product fixes a permanently negative gap between income and spending.
- Pay attention to cash flow. Money you do not track is easy to assign twice.
- Save consistently. Waiting until you “have extra” often means waiting forever.
- Understand before you buy. Financial complexity can hide cost and risk.
- Keep investing simple enough to continue. A plan you understand and stick with is more useful than one you constantly abandon.
- Do not chase quick wealth. Urgency and greed are expensive teachers.
- Know your financial position. Net worth, debt, cash reserves, and benefits matter more than how financially successful you look.
Those are not flashy insights. They are useful because personal finance usually breaks in ordinary ways.
Michael take: In financial planning, the hard part is often not discovering the rule. It is building a life where the good decision happens often enough to matter.
What Needs a 2026 Filter
This is where a good beginner book can become dangerous if a reader treats “clear” as “permanently correct.”
The 20% down-payment rule is a target, not a universal gate
The book recommends at least 20% down on a home purchase. Twenty percent can absolutely reduce borrowing costs and often avoids mortgage insurance on a conventional loan. But the current Consumer Financial Protection Bureau guidance says many mortgages allow substantially less, and the right down payment depends on the loan, closing costs, emergency reserves, and other goals.
The CFPB currently notes that many loans require at least 3% to 5% down, that borrowers often save more at 10%, and that 20% generally produces the greatest cost savings. It also emphasizes keeping an emergency cushion instead of putting every available dollar into the house.
So I would translate the old rule into a better question:
How much should I put down after comparing the total loan cost with the cash I still need after closing?
Credit-report access has changed
The old “one free report from each bureau per year” language is incomplete now. Federal law still provides that annual entitlement, but the Federal Trade Commission says Equifax, Experian, and TransUnion have permanently extended free weekly online credit reports through AnnualCreditReport.com.
Same principle—check your credit. Different implementation.
“Index fund” does not automatically mean cheap or diversified
Siegel’s simple-indexing instinct still points beginners in a sensible direction, but today’s implementation deserves more nuance. Investor.gov notes that index funds can be mutual funds or ETFs, that not every index fund is low cost, and that the fund still carries the risks of the securities and index it tracks.
Likewise, owning “an ETF” does not automatically make a portfolio diversified. Some ETFs are broad; others are concentrated in one industry, strategy, or even one stock.
Keep the principle. Recheck the implementation. That is the right way to read almost every practical finance book more than a decade after publication.
Is the Book Too Basic?
For some readers, yes. That is not automatically a criticism.
If you already automate savings, understand how credit works, carry appropriate insurance, use a diversified portfolio, and know your employee benefits, you are going to read many of these principles and think, “Well… obviously.”
A true beginner may have the opposite reaction: “Why did nobody explain it that simply before?”
That is the real fit test. This is not a book for finding clever financial edges. It is a book for reducing the distance between not knowing where to start and making the first few competent decisions.

Who Should Read It — and Who Should Skip It
Read it if:
- financial jargon still makes you hesitate;
- you have never built a consistent saving or budgeting system;
- credit, insurance, investing, and benefits still feel like separate mysteries;
- you want a finance book you can read in short bursts;
- you are buying for a high-school student, college student, recent graduate, or young adult starting from scratch;
- you need a starting point more than you need optimization.
Skip it if:
- you already automate saving and investing;
- you understand borrowing costs, insurance, and basic tax/account concepts;
- you want detailed portfolio construction or retirement strategy;
- you need current step-by-step instructions for a specific financial decision;
- you are looking for advanced tax, estate, or income-planning guidance.
If you are currently in college, compare it with my best personal finance books for college students. If you are already earning adult income and dealing with benefits, housing, investing, and lifestyle creep, my young-adult finance-book guide is a better next stop.
How I’d Use the 99 Principles in 2026
Do not try to turn all 99 principles into 99 new financial chores.
Read the book quickly once. Then sort what you marked into three buckets:
- KEEP: timeless behavior or decision rules. Turn one into a repeatable habit.
- CHECK: sensible principle, but implementation depends on current products, laws, costs, or technology. Verify before acting.
- SKIP FOR NOW: useful topic, wrong stage of life. Come back when the decision becomes real.
Then choose one action for the next seven days.
- Track spending for a week.
- Pull all three credit reports.
- Move the first $100 into an emergency fund.
- Read your workplace retirement-plan summary.
- Increase an automatic savings transfer.
- List every debt with balance, rate, and minimum payment.
That is how a beginner book becomes useful. Not by agreeing with 99 rules. By turning one good idea into one behavior that keeps happening.
Final Verdict: Is It Worth Reading?
Yes—for the right reader.
Why Didn’t They Teach Me This in School? is still good at the job it was designed to do: make everyday personal finance feel manageable enough to begin. Cary Siegel’s official description says the book was built as a quick, practical set of principles for his own children, and that simplicity remains its advantage.
I would not use a 2013 book as my only source for mortgage choices, credit access, investment products, insurance, or other date-sensitive decisions. But I would still use it to teach the habits underneath those decisions.
The useful core is surprisingly durable:
Spend intentionally. Build margin. Save before lifestyle absorbs the money. Understand what you are buying. Avoid expensive mistakes. Start investing without making investing unnecessarily complicated.
If those ideas are already your normal routine, choose a more advanced book.
If they sound like the class you somehow missed, this book is still a very reasonable place to start.
See Why Didn’t They Teach Me This in School? on Amazon →
Frequently Asked Questions
What is Why Didn’t They Teach Me This in School? about?
It is a beginner personal-finance book by Cary Siegel organized around 99 short money-management principles across eight lessons. It covers everyday topics such as budgeting, saving, credit, debt, insurance, investing, benefits, and major financial decisions.
What are the main lessons from Why Didn’t They Teach Me This in School?
The most durable lessons are to live below your means, know where your money goes, save consistently, maintain emergency reserves, understand credit and borrowing, protect yourself with appropriate insurance, keep investing simple, and learn the financial terms attached to adult life.
Is Why Didn’t They Teach Me This in School? still relevant in 2026?
Yes as a beginner behavior guide. Some tactical recommendations should be rechecked because mortgage options, credit-report access, financial products, fees, and other implementation details change over time.
Is the book good for teenagers or college students?
Yes, especially for older teens, college students, and recent graduates who want a quick introduction to everyday money management. Readers who already understand the basics may find it too elementary.
Should I read the book or the workbook?
The original book is better if you want the 99 principles in a quick-read format. The companion workbook is designed around reinforcement exercises, so it may fit teachers, parents, classes, or readers who learn better by doing exercises rather than only reading.
What should I read after Why Didn’t They Teach Me This in School?
That depends on the next problem. If you still need a broad foundation, compare the books in my beginner-finance guide. If you need investing depth, move to the best investing books. If debt is the immediate problem, use my best books for getting out of debt.
