

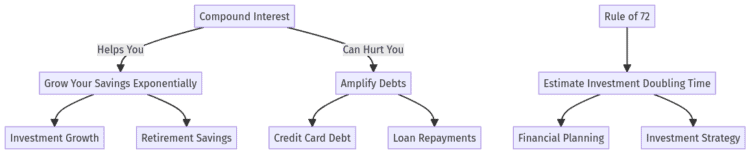
The straight answer: Compound interest is the interest you earn on both your original principal and the accumulated interest from previous periods. The Rule of 72 is a simple formula to estimate how many years it will take for an investment to double.
While often called the “eighth wonder of the world,” compounding is a double-edged sword: it can build immense wealth over time or create an inescapable cycle of debt.
This guide moves beyond the definition. You’ll see the formula, the Rule of 72, calculator examples, and the places where compounding can help or hurt depending on whether you are earning interest or paying it.
Whether you’re a recent graduate starting with small savings or a homeowner battling credit card debt, you will leave this page with the financial literacy to make your money work for you, not against you.
On This Page
- Key Takeaways Ahead
- Compound Interest Calculators
- Compound Interest Time Machine
- Understanding Compound Interest: A Key to Financial Growth
- The Three Levers of Your Compounding Machine
- The Dark Side: When Compound Interest is Your Enemy
- The Hidden Enemies of Compounding
- Final Thoughts: Your Keys to Compounding Financial Freedom
Key Takeaways Ahead
Compound Interest Calculators
Below is the Michael Ryan Money compound interest calculator for you to choose from below. Just click on each tab, then enter your information and watch the math happen!
Compounding rewards time because each period can build on the value accumulated before it. The same mechanism can also make debt more expensive when interest is added to the balance.
Compound Interest Time Machine
Compare two saving and investing paths side by side. Change the starting amount, monthly contribution, return assumption, and years to see which factor matters most.
What the assumptions produce
Each result separates what you put in from the growth generated by the return assumption.
Scenario A
—- Total contributed
- —
- Assumed growth
- —
Scenario B
—- Total contributed
- —
- Assumed growth
- —
What the comparison shows
Understanding Compound Interest: A Key to Financial Growth
Compound interest works by earning interest on both your principal (the initial amount) and the interest that accumulates. It’s the engine of long-term wealth building.
First, the formula for compound interest is: A = P(1 + r/n)^(nt)
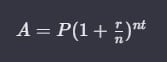
- A is the future value of your investment
- P is the principal amount you invested
- r is the annual interest rate
- n is the number of times interest is compounded per year
- t is the number of years you invest
The Rule of 72: Your Mental Shortcut
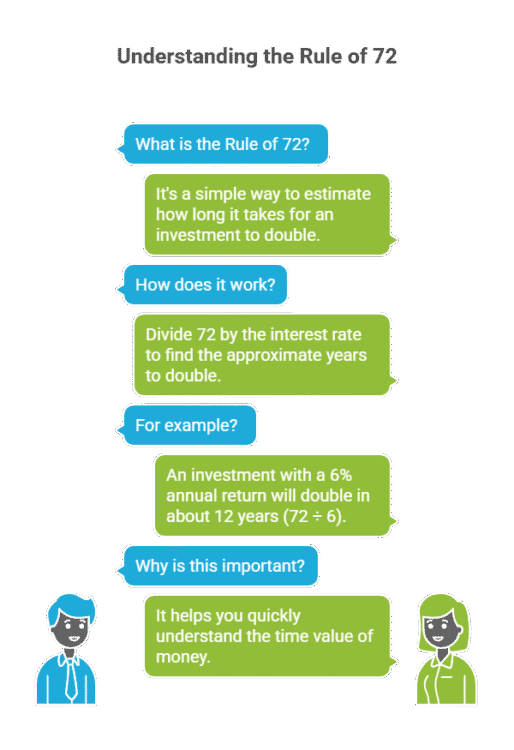
The Rule of 72 is a simple way to estimate how long it will take for an investment to double.
Formula: 72 ÷ Interest Rate = Years to Double
For example, an investment with a 6% annual return will double in approximately 12 years (72 ÷ 6). This powerful shortcut helps you quickly grasp the time value of money without complex formulas.
An Example of Compounding in Action
You invest $1,000 at a 5% annual compound interest rate.
- Year 1: You earn $50 in interest. Total = $1,050.
- Year 2: You earn 5% on $1,050, which is $52.50. Total = $1,102.50.
- Year 10: Your investment grows to $1,628.89.
This exponential growth in finance is what makes compounding a powerful ally, and the separate guide shows why the curve accelerates and why real investment returns are not perfectly smooth.
The Three Levers of Your Compounding Machine
Think of your wealth as a machine with three critical levers. How you pull them determines your financial outcome.
Lever 1: Time
Time is one of the biggest levers because it gives more compounding periods a chance to occur. But the result also depends on how much you contribute, the return or interest rate, fees, taxes, withdrawals, and whether the return is actually earned.
The key insight?
Starting earlier can reduce how much later contribution money is needed to reach the same hypothetical ending value, because the earlier dollars have more time to compound. Treat any example on this page as math under stated assumptions, not as a promised investment outcome.
Lever 2: Compounding Frequency (The Engine’s Speed)
Holding the stated nominal interest rate constant, more frequent compounding produces a slightly higher effective annual yield. The difference can be much smaller than the difference created by the rate itself, fees, contributions, or time.
- Daily compounding or daily interest accrual: Common in many deposit and lending products, although the institution may credit interest on a different schedule.
- Monthly compounding: Used in some savings, loan, and other interest-bearing calculations. Dividend reinvestment is different because dividends are distributions from an investment, not a fixed interest rate.
- Annual compounding: With the same nominal rate, produces a lower effective yield than more frequent compounding.
With a $1,000 investment at 5% interest over 10 years:
- Daily compounding grows to $1,648.66.
- Monthly compounding grows to $1,647.01.
- Annually it grows to $1,628.89.
| Year | Principal | Interest Earned | Ending Balance |
|---|---|---|---|
| 1 | $1,000.00 | $50.00 | $1,050.00 |
| 2 | $1,050.00 | $52.50 | $1,102.50 |
| 3 | $1,102.50 | $55.13 | $1,157.63 |
| 4 | $1,157.63 | $57.88 | $1,215.51 |
| 5 | $1,215.51 | $60.78 | $1,276.29 |
| 6 | $1,276.29 | $63.81 | $1,340.10 |
| 7 | $1,340.10 | $67.00 | $1,407.10 |
| 8 | $1,407.10 | $70.36 | $1,477.46 |
| 9 | $1,477.46 | $73.87 | $1,551.33 |
| 10 | $1,551.33 | $77.57 | $1,628.90 |
Lever 3: Rate of Return (The Fuel’s Quality)
A higher rate of return dramatically accelerates growth. This is where moving from a simple savings account to diversified investments in a Roth IRA or 401(k) becomes critical.
The Dark Side: When Compound Interest is Your Enemy
Compounding is equally powerful when it works against you in the form of debt.
- Credit Card Debt:
A $5,000 balance at a 20% Annual Percentage Rate (APR) can take over a decade and cost thousands in interest if you only make minimum payments. - Student loans:
Interest can continue to accrue on loans such as Direct Unsubsidized Loans during certain nonpayment periods. Unpaid interest may then be capitalized in specific situations, which adds it to principal so future interest is charged on a larger balance. Federal Student Aid explains how capitalization can increase principal. - Mortgages:
A standard amortizing mortgage charges interest on the outstanding loan balance. Over a long term, total interest can be substantial, but that is not the same thing as saying a mortgage balance simply compounds like a savings account.
The Hidden Enemies of Compounding

Beyond debt, three silent forces can erode your compound growth.
- Inflation:
Inflation reduces purchasing power. Subtracting inflation from a nominal return gives a quick approximation of real return, but the exact relationship is multiplicative. For example, a 7% nominal return with 3% inflation is about a 3.9% real return before taxes and fees. For current inflation data, see the Bureau of Labor Statistics CPI. - Fees:
Recurring fees reduce the amount left to compound. The dollar effect depends on the starting balance, contributions, gross return, fee structure, and time horizon, so compare long-term outcomes using the same assumptions rather than relying on one universal dollar figure. - Taxes:
Taxes can reduce the amount left to compound. Roth IRA earnings can ultimately be distributed tax-free when the distribution is qualified; nonqualified Roth distributions can have different tax treatment. See the IRS Roth IRA rules.
- Start Early: Even small, consistent contributions can grow into a substantial nest egg.
- Be Consistent: Automate your contributions to savings and investment accounts.
- Reinvest Dividends: This is a key accelerator for compound growth.
- Minimize Debt: Aggressively pay down high-interest debt.
The journey of a thousand miles begins with a single step. By harnessing the power of compounding, you are taking control of your financial future.
We are audience supported - when you make a purchase through our site, we may earn an affiliate commission.
