
An annuity rider is an optional contract feature that changes what an annuity promises, how much it costs, or both. A rider can add lifetime income guarantees, enhanced death benefits, long-term care style benefits, or other protections. The catch is that the biggest number in the illustration is often not your cash value. And the rider fee may be charged against a benefit base that is different from the money you can actually walk away with.
That distinction is the whole game. Before deciding whether an annuity rider is worth paying for, you need to know four things:
- what is guaranteed
- what number the guarantee is based on
- what can reduce it
- and what the annuity rider actually costs in dollars.
Show the quick answer
- What a rider is: An annuity rider is an optional contract provision that adds or changes a benefit, usually in exchange for a charge or a trade-off elsewhere in the contract.
- The number people confuse: An income benefit base is usually a calculation value used to determine guaranteed income. It is not automatically the amount you can surrender or withdraw as a lump sum.
- What to compare: Compare the guaranteed annual income, rider charge, fee base, liquidity restrictions, investment restrictions, death benefit and what happens after an excess withdrawal—not just the bonus or roll-up rate.
- Fees vary: There is no universal annuity-rider fee. Current contract filings show charges and fee bases vary materially by insurer, product, option and issue date.
- Michael's rule: Buy the promise, not the headline number. If you cannot explain what the rider pays, when it pays and what can break the guarantee, you do not understand the rider yet.
On This Page
- What Is an Annuity Rider?
- The Most Important Distinction: Benefit Base vs. Account Value
- Common Types of Annuity Riders
- How Annuity Rider Fees Actually Work
- Guaranteed Lifetime Withdrawal Benefit (GLWB): What the Guarantee Really Says
- Long-Term-Care and Death-Benefit Riders: Read the Trigger, Not the Label
- What to Compare Next
- Are Annuity Riders Worth It?
- Annuity Rider Red Flags Before You Sign
- Annuity Rider FAQ
- Bottom Line: Buy the Promise, Not the Headline Number
- How We Verified This
What Is an Annuity Rider?

Think of the base annuity as the contract and the rider as an added rule attached to it. The rider might promise lifetime withdrawals, a minimum income amount, an enhanced death benefit, or another insurance feature.
In return, you may pay an explicit rider charge, accept limits on investment choices or withdrawals, or give up flexibility in another part of the contract.
The SEC’s Investor.gov variable-annuity guidance describes these optional insurance features as benefits that may come with additional fees, complexity and restrictions. Some living-benefit riders can guarantee lifetime withdrawals even if the contract value later falls to zero, but the exact conditions are contract-specific.
Michael’s rule: A rider should solve one specific risk you actually care about. If you cannot name the risk, the guarantee and the price in one sentence each, the rider is probably doing more selling than planning.
The Most Important Distinction: Benefit Base vs. Account Value
This is where many annuity presentations go off the rails.
An income rider may create a benefit base, income base, protected payment base or similarly named value. That number is typically used in a formula to calculate a future guaranteed withdrawal or income amount. It is not necessarily your contract’s cash value, surrender value or death benefit.
Current SEC-filed 2026 annuity disclosures make this distinction explicit. One filing states that the benefit base cannot be taken as a lump sum and does not establish or guarantee the account value. Another explains that the annual guaranteed payment is calculated by multiplying the benefit base by a withdrawal rate.
| Number on the statement | What it usually means | Can you cash it out? |
|---|---|---|
| Account / contract value | Current value of the annuity’s underlying contract account before any applicable surrender adjustment. | Potentially, subject to contract rules, surrender charges, taxes and penalties. |
| Surrender value | What the contract says is available if you fully surrender at that point. | Generally this is the relevant contract amount for a full surrender, subject to tax consequences and contract terms. |
| Benefit / income base | A bookkeeping value used to calculate a guaranteed rider benefit. | Usually no. It is commonly not a lump-sum value. |
A recent retirement forum question captured the confusion perfectly. An owner saw a roughly $10,740 surrender value and a much larger $20,650 GMWB value and wanted to know which amount was actually withdrawable. The discussion correctly centered on the contract language because the larger rider value was being used to calculate income. Not presented as cash available on demand.
That is the mental model I want you to keep.
The benefit base is often the ruler used to measure the guarantee, not a pile of money sitting in a second account.
Common Types of Annuity Riders
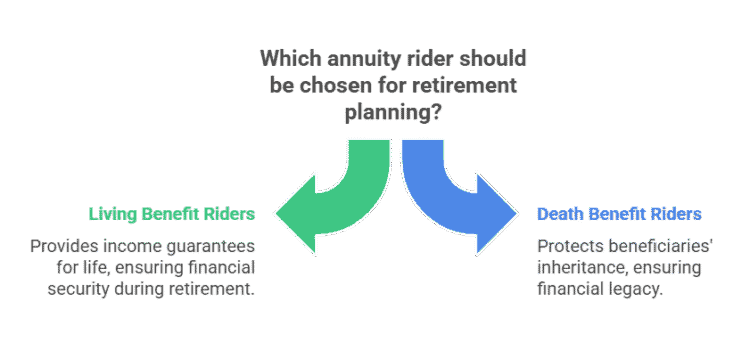
Names vary by company and contract, but the rider jobs usually fall into a few recognizable groups.
| Rider type | Main job | The question to ask |
|---|---|---|
| Guaranteed Lifetime Withdrawal Benefit (GLWB) | Provides a contractually defined lifetime withdrawal amount if conditions are met. | What annual dollar income does the current benefit base and payout rate actually produce? |
| Guaranteed Minimum Income Benefit (GMIB) | Provides a minimum value or formula for converting the contract into income under specified conditions. | Do I have to annuitize, and what income option/rate is used? |
| Guaranteed Minimum Withdrawal Benefit (GMWB) | Provides a defined withdrawal benefit, sometimes for life and sometimes until a guaranteed amount is exhausted. | What happens after an excess withdrawal or full surrender? |
| Enhanced death benefit | Changes the minimum amount beneficiaries may receive at death. | How is the death benefit calculated and reduced by withdrawals? |
| Long-term-care / enhanced-benefit feature | May increase available benefits when specified health or care conditions are met. | What exact trigger, benefit period and care definition applies? |
Do not assume the marketing name tells you the legal mechanics. Two riders that both say “lifetime income” can have different ages, payout percentages, step-ups, investment restrictions, withdrawal rules and fees.
How Annuity Rider Fees Actually Work
There is no single 2026 “annuity rider fee.” That is one of the biggest corrections from the old version of this page.
Current SEC filings show why universal fee ranges are dangerous. One contract lists current guaranteed-withdrawal rider charges around 0.40% to 0.70% with contractual maximums up to 1.20%.
Other 2026 filings show current GLWB charges around 1.30% to 1.45%, while some rider structures disclose maximum annual charges of 2.00%, 2.50% or more.
The percentage is only half the story because the charge may be applied to the benefit base or protected payment base, not simply the account value.
That creates a very practical question:
“1% of what?” is more useful than asking whether a 1% rider fee sounds high or low.
- Ask for the annual percentage.
- Ask what value the percentage is applied to.
- Ask whether that base can step up even if account value falls.
- Ask whether the charge can change after a reset, election or excess withdrawal.
- Ask for the current annual dollar cost using today’s actual values.
- Then ask for the same contract without the rider.
If a $500,000 rider base is charged 1.20%, that’s $6,000 for that year. But do not assume the next year’s fee is the same just because the account value went down. The fee formula depends on the contract.
Guaranteed Lifetime Withdrawal Benefit (GLWB): What the Guarantee Really Says
A GLWB is one of the most searched rider types for a reason: it is trying to solve a problem people genuinely care about. Turning part of retirement savings into a lifetime income floor without necessarily annuitizing the entire contract.
Investor.gov describes guaranteed lifetime withdrawal benefits as optional features that can allow specified withdrawals for life even if contract value later falls to zero. Current contract filings add the part marketing slides sometimes minimize: the guarantee is subject to rider conditions.
- Starting income may depend on your age when withdrawals begin.
- Joint-life coverage may use a different payout rate or fee.
- Investment allocations may be restricted while the rider is in force.
- Withdrawals above the permitted amount can reduce the benefit base, future income, or even terminate the rider.
- The benefit base generally is not the contract’s lump-sum cash value.
This is also why a “9.5% guaranteed roll-up” should not be read as “my annuity earns 9.5%.”
A recent buyer on Reddit made exactly that leap, subtracting a 1.1% rider charge and assuming the result was an 8.4% annual investment return. Other commenters correctly pointed out that the 9.5% figure applied to an income benefit base, not necessarily the cash account value.
Buy the income, not the roll-up rate. If Product A has a smaller benefit base but a higher payout percentage, it can produce more annual guaranteed income than Product B with the flashier bonus or roll-up. The number that matters is the contractual income you can actually receive under the conditions you expect to use.
Long-Term-Care and Death-Benefit Riders: Read the Trigger, Not the Label
Some annuity contracts offer enhanced benefits tied to long-term-care needs, serious illness or specified activities-of-daily-living conditions. Others offer enhanced death benefits designed to change what beneficiaries receive.
The old article treated these riders as though the labels described a standardized benefit. They do not. Investor.gov specifically warns that optional insurance features vary by contract and can involve extra fees, risks and limitations.
For a care-related rider, ask: What event activates it? Who certifies that event? How long does the enhancement last? Does it accelerate your own contract value, provide additional insurance value, or both? That is far more useful than assuming “LTC rider” means the same thing as standalone long-term-care insurance.
For a death-benefit rider, ask what happens after withdrawals, whether the guarantee is a return of premium, a stepped-up base, an anniversary value, or another formula, and how long the feature remains in force.
Are Annuity Riders Worth It?
Sometimes. But “worth it” has to be answered against a specific risk and a specific contract.
A lifetime-income rider can be valuable when the job is to create a contractual income floor and the owner intends to use the lifetime-income feature. A death-benefit rider can be useful when leaving a defined minimum benefit matters enough to justify its cost. A care-related rider can fill a planning gap when the trigger and benefit genuinely match the household’s concern.
The same rider can be poor value for someone who wants maximum liquidity, expects to surrender the contract, does not need the insured benefit, or could solve the problem more efficiently another way.
| Rider may deserve a closer look when… | Slow down when… |
|---|---|
| You can clearly name the financial risk the rider transfers. | The sales pitch centers on a bonus or roll-up rate but not the actual guaranteed income. |
| You expect to use the guaranteed benefit for its intended purpose. | You may need the money back as a lump sum or before surrender restrictions expire. |
| You understand the fee base and dollar cost. | The fee is quoted only as a percentage with no explanation of what it is charged against. |
| The guarantee fits alongside the rest of your retirement-income plan. | The rider is being presented as a substitute for understanding the whole annuity contract. |
One thing I’ve learned over a long career in financial planning is that annuity riders are easiest to understand when you stop asking, “Is this a good rider?” and ask, “What risk am I paying this insurance company to take off my hands?” That question makes the sales language much less impressive—and the useful guarantees much easier to spot.
Annuity Rider Red Flags Before You Sign
Not every annuity recommendation is a scam, and complexity by itself is not proof of a bad product. But complexity creates room for misunderstanding. The NAIC annuity best-interest framework is specifically designed around consumer needs, disclosure, conflicts of interest and documentation, with state adoption controlling the exact rule that applies where you live.
- “Guaranteed 8%, 9% or 10%” with no noun after it. Guaranteed growth of what—cash value, benefit base, income payment, or something else?
- A bonus is presented like free cash. Ask whether the bonus increases surrender value, account value, income base, death benefit, or only one specific calculation.
- The rider fee is quoted without the fee base. Ask “percentage of what?”
- Excess-withdrawal rules are rushed. Current GLWB filings often state that excess or nonguaranteed withdrawals can reduce future benefits and in some contracts can terminate the rider.
- No side-by-side version without the rider. You should be able to see what the rider changes and what you pay for it.
- No discussion of insurer strength. An annuity guarantee is an obligation of the issuing insurance company and depends on its claims-paying ability.
- The sales conversation never reaches your real retirement plan. A good contractual guarantee can still be the wrong tool for the job.
Annuity Rider FAQ
What is a rider fee on an annuity?
A rider fee is the charge for an optional contract feature such as a living-benefit or death-benefit guarantee. The percentage and the value it is applied to vary by contract. Some current filings calculate charges from a benefit base rather than directly from account value, so always ask for the annual dollar cost as well as the percentage.
What is a Guaranteed Lifetime Withdrawal Benefit?
A GLWB is an optional rider that can guarantee a defined amount of withdrawals for life if its conditions are met. It typically uses a separate benefit base and withdrawal percentage to calculate the guaranteed annual amount. The benefit base is generally not your lump-sum cash value.
Can I withdraw the annuity benefit base as cash?
Usually not. Many rider contracts explicitly state that the benefit base is only a calculation value for determining guaranteed benefits and is not available as a lump sum. Check your own contract because terminology and mechanics vary.
Can I cancel an annuity rider later?
It depends on the contract. Some riders can be terminated under specified conditions; others have restrictions, waiting periods or consequences when terminated. Do not assume a rider can simply be removed later to stop the fee. Check the actual rider provision before purchase.
Does an income rider’s roll-up rate mean my annuity earns that return?
Not necessarily. A roll-up rate often increases the income benefit base used to calculate future guaranteed withdrawals. It may have no direct relationship to the investment return or surrender value of the contract. This is one of the most important distinctions to verify.
Bottom Line: Buy the Promise, Not the Headline Number
Annuity riders are not automatically good, bad, cheap or expensive. They are contractual tools for transferring a particular risk to an insurance company.
The mistake is judging them by the biggest percentage on the page. A 20% bonus, 9.5% roll-up or $800,000 benefit base can sound impressive while telling you surprisingly little about the cash you own or the income you’ll actually receive.
Before you buy, write down four numbers: your actual contract value, the rider benefit base, the guaranteed annual income available when you plan to start it, and the rider’s annual dollar cost. Then write down what happens after an excess withdrawal. If you can explain those five things in plain English, you’re finally comparing the rider instead of the brochure.
Strategic selection, not collection. One rider that solves a real retirement risk can be useful. Five impressive-sounding guarantees you do not understand are just expensive decoration.
How We Verified This
Contract mechanics and consumer-protection statements were checked against current regulator guidance and 2026 SEC-filed annuity disclosures.
