


A fixed annuity can be a good fit if you want a contractually guaranteed interest rate and can leave that money alone through the surrender period. It is a poor fit if you need easy access, want this same money to provide long-term market growth, or are uncomfortable relying on an insurance company’s claims-paying ability.
That is the useful way to weigh the fixed annuities pros and cons. Don’t start with, “Are annuities good?” Start with, “What job does this money need to do?” A fixed annuity changes the risks you carry. You give up some liquidity and upside in exchange for contractual guarantees.
A fixed annuity is an insurance contract, not a bank deposit. During the guaranteed period, the insurer promises the interest crediting described in the contract and protects the contract value from stock-market losses, subject to the insurer’s ability to pay.
The biggest advantages are predictability, tax deferral in a nonqualified contract, and protection from direct market losses. The biggest drawbacks are surrender restrictions, insurer credit risk, inflation and interest-rate opportunity cost, and tax rules that can make early withdrawals less attractive.
My decision rule: a fixed annuity belongs only in money whose job is more important than its flexibility.
Key Takeaways Ahead
What a Fixed Annuity Actually Guarantees
A fixed annuity is a contract with an insurance company. You pay a premium, and the insurer credits interest under the contract’s fixed-rate terms. The contract value is not directly invested in the stock market, so a market drop does not reduce it the way a stock fund can.
But “principal protected” does not mean “risk free.” Investor.gov’s annuity guidance makes the controlling point: an insurer’s promises depend on its financial strength and claims-paying ability. Withdrawals can also be reduced by surrender charges or contract adjustments.
That gives you a better mental model:
A fixed annuity does not eliminate risk. It swaps some risks for others.
- You reduce direct stock-market risk on the annuity bucket.
- You accept insurer credit risk.
- You accept liquidity and surrender restrictions.
- You accept inflation and interest-rate opportunity cost.
If that trade sounds better for the job this money must do, the annuity may fit. If not, the guarantee is solving the wrong problem.
If you need the broader taxonomy first, my annuity types overview explains the larger category. This page stays on the fixed-annuity decision.
Which Fixed Annuity Are You Actually Considering?
This matters because people use “fixed annuity” to describe contracts doing different jobs.
- Fixed deferred annuity: designed primarily to accumulate value at an insurer-declared or guaranteed fixed rate before you take money out later.
- Multi-Year Guaranteed Annuity (MYGA): a fixed deferred annuity that guarantees a stated rate for a specified multi-year period. This is the version most directly compared with CDs.
- Immediate annuity: primarily an income contract. You exchange a lump sum for payments that begin soon. That is a different decision, so my immediate annuity guide owns the payout mechanics.
Also keep fixed annuities separate from variable annuities, where contract value can depend on underlying investment choices. If that is the product in front of you, use the separate variable annuity pros and cons analysis instead.
For the rest of this article, “fixed annuity” mainly means a fixed deferred annuity or MYGA used for protected accumulation—not a variable annuity and not a full immediate-income analysis.
When a Fixed Annuity Can Be a Good Fit
A fixed annuity earns its place when the guarantee solves a specific problem better than the alternatives.
1. You want a known return on money you do not need soon
With a MYGA, the rate is guaranteed for the contract’s stated term. That can be useful for a retirement bucket whose job is stability rather than maximum growth. The key phrase is money you do not need soon. A higher quoted rate is not a benefit if you may have to surrender the contract early.
2. Tax deferral in a taxable account is useful to you
A nonqualified annuity generally defers federal income tax on its earnings until money is distributed. That can be useful when you are deliberately postponing taxable interest. It is not the same tax treatment as a CD, where taxable interest is generally reported as it is earned.
However, don’t buy an annuity inside an IRA just to get tax deferral. Investor.gov notes that a traditional IRA or other tax-deferred retirement plan already supplies that feature, so the annuity provides no additional tax deferral there. An IRA annuity would need to earn its keep through some other contract feature.
3. You are deliberately building a protected retirement bucket
Some retirees do not want every dollar exposed to market volatility. A fixed annuity can be one ingredient in the protected side of a retirement plan, alongside cash, CDs or high-quality bonds. It does not need to be “the retirement plan.” It can simply have one job.
When I was working with clients, the useful conversation was rarely “Do you like annuities?” It was “Which dollars can never be forced into a bad sale at a bad time?” Once that bucket had a job, comparing the contract became much easier.
I would rather see a smaller annuity doing one clear job than a large annuity bought because “guaranteed” sounded comforting.
When a Fixed Annuity Is a Bad Fit
The disadvantages of a fixed annuity are not side notes. They are the price of the guarantee.
1. You may need the money during the surrender period
FINRA’s annuity guidance flags liquidity risk as a core issue: many annuities have holding periods and surrender charges for early withdrawals. Contract terms vary. Some permit limited penalty-free withdrawals; some also use a market value adjustment or another contract adjustment that can increase or reduce surrender value.
A safe return is not the same thing as safe access. If this is also your emergency fund, home-repair money or near-term medical reserve, the contract is probably being asked to do two incompatible jobs.
2. You need strong long-term inflation protection
A nominal guarantee can still lose purchasing power. FINRA notes that fixed annuity payments typically do not include cost-of-living adjustments unless you purchase a form of inflation protection, which generally costs more. Even during the accumulation phase, a fixed rate can lag future inflation.
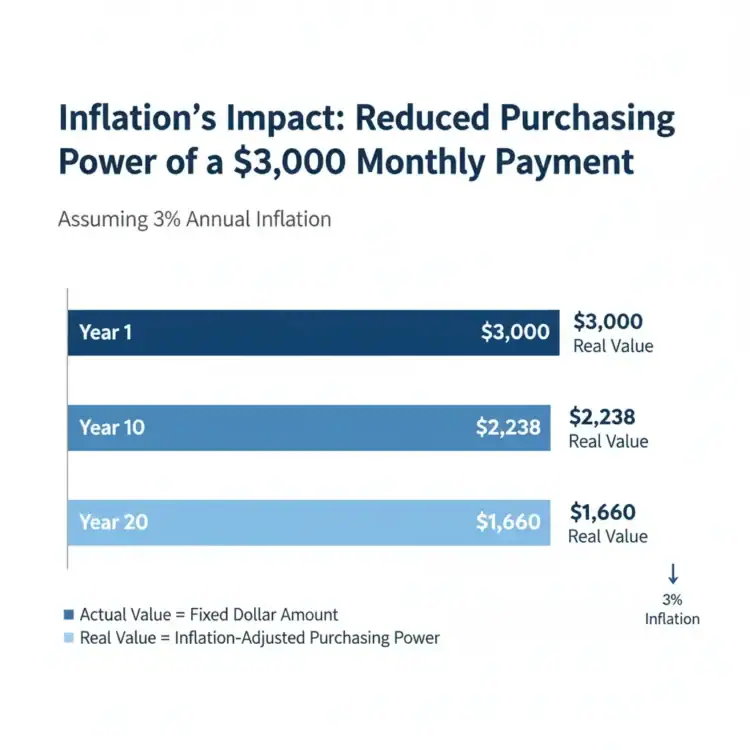
For illustration, if inflation averaged 3%, $3,000 of purchasing power today would be equivalent to about $2,232 after 10 years, $1,661 after 20 years and $1,433 after 25 years. That does not make a fixed annuity “bad.” It means the rest of the retirement plan still needs a way to address rising costs.
3. You are buying it mainly because today’s rate looks attractive
Interest rates move. FINRA points out that locking a rate creates opportunity cost if market rates later rise, and some fixed annuity contracts can change their credited rate after an initial guarantee period. Read exactly which rate is guaranteed, for how long, and what happens afterward.
4. You expect stock-like growth from a no-market-loss contract
The point of a fixed annuity is not to capture the stock market’s upside. If the money’s job is long-horizon growth and you can tolerate volatility, a diversified investment portfolio may be a better match. The guarantee has value precisely because you are giving something up for it.
Fixed Annuity vs. CD vs. Treasury: Which Guarantee Matters?
This is the comparison I would make before chasing a rate quote. The products can all hold conservative money, but they protect you in different ways.
| Decision factor | Fixed annuity / MYGA | Bank CD | U.S. Treasury held to maturity |
|---|---|---|---|
| Who stands behind it? | Insurance company; state guaranty-association protection may apply within state limits | FDIC-insured bank; eligible deposits insured within FDIC limits | U.S. government obligation |
| Tax timing in a taxable account | Earnings generally tax-deferred until distributed | Interest generally taxable as earned | Interest generally taxable federally; special state/local treatment applies |
| Early access | Contract surrender charges and adjustments may apply | Bank early-withdrawal penalty may apply | Can generally be sold before maturity, but market price can be higher or lower |
| Best fit | Longer-term money where insurer-backed guarantee and tax deferral are useful | Deposits where FDIC protection and simpler bank structure matter | Investors prioritizing direct U.S. government credit and marketable securities |
The FDIC covers eligible bank deposits such as CDs up to the applicable insurance limits; it explicitly does not insure annuities. IRS Publication 550 explains that CD interest generally enters taxable income as it is received, credited, or otherwise becomes available under the applicable interest-reporting rules. TreasuryDirect says marketable Treasury securities are backed by the full faith and credit of the U.S. government, and they can generally be sold before maturity. TreasuryDirect tax guidance says interest on marketable Treasury securities is subject to federal tax but exempt from state and local income tax.
So “Which one has the highest rate?” is incomplete. Ask, “Which guarantee, liquidity structure and tax treatment fit this bucket of money?”
What the Headline Rate Can Hide
A fixed annuity can be fairly simple, but the sales conversation can make it sound simpler than the contract really is. Before you compare rates, compare the rules around the rate.
- Guaranteed for how long? A rate guaranteed for the full MYGA term is different from an initial rate that can reset later.
- What is the surrender schedule? Know the dollar consequence of leaving in year 1, year 3 and the final surrender year.
- Is there a market value adjustment? A contract adjustment can change the amount you receive on an early exit, separate from a surrender charge.
- What withdrawal flexibility exists? Do not assume a universal “10% free withdrawal” rule. Contract provisions vary.
- What optional benefits are attached? Riders and benefits can change cost and value. My annuity riders guide covers those features separately.
Investor.gov also notes that many fixed annuities do not charge explicit ongoing fees, but a product can still have implicit economic costs in the crediting terms. “No annual fee” does not mean “no tradeoff.”
And ask how the person recommending the contract is compensated. The point is not to assume a commission makes the recommendation wrong. It is to know whether compensation or a limited product shelf creates a conflict you should factor into the decision. NAIC’s annuity best-interest framework requires recommendations under adopted state rules to address the consumer’s needs and financial objectives and to disclose material conflicts.
Fixed Annuity Fit Checklist
You do not need a personality test to decide this. You need five answers.
- Job test: Is this money’s job protected accumulation rather than maximum long-term growth?
- Liquidity test: Can you leave this money alone for the entire surrender period even after accounting for emergencies and large planned expenses?
- Tax test: Is tax deferral actually useful in this account, or is the money already inside an IRA or other tax-deferred plan?
- Guarantee test: Are you comfortable relying on this insurer’s claims-paying ability and your state’s guaranty-association framework rather than FDIC deposit insurance?
- Inflation test: Do you have other assets or income sources positioned to deal with rising costs and long-term growth?
If you cannot answer all five, you are not ready to compare annuity rates. You are still deciding whether the contract belongs in the plan at all.
The tax test deserves one more sentence. In a nonqualified annuity, earnings generally grow tax-deferred, but distributions can have less favorable timing than people expect. IRS Publication 575 explains that taxable amounts from nonqualified annuities are generally ordinary income, and a 10% additional federal tax can apply to the taxable part of many distributions before age 59½ unless an exception applies.
Make the Guarantee Earn Its Place
The annuity decision gets easier when you stop comparing products and start assigning jobs to dollars. I send readers plain-English notes on retirement-income tradeoffs like this—where the “safer” choice can quietly introduce a different risk.
- How to separate protected money from growth money
- When tax deferral is useful—and when it is just marketing wallpaper
- What contract language deserves a second look before you lock up cash
Two Fixed-Annuity Fit Tests
These are hypothetical examples. The point is not the rate; it is whether the same contract solves or creates the reader’s real problem.
A 66-year-old retiree has a separate emergency reserve, Social Security covering part of monthly expenses, and a diversified portfolio for long-term growth. She wants one portion of cash to mature in five years without stock-market exposure and does not expect to touch it sooner.
A five-year MYGA can be a reasonable candidate because the money has one clear job, the surrender period matches the time horizon, and she is not asking the annuity to provide emergency liquidity or all of her inflation protection.
A 59-year-old puts most of his accessible savings into a seven-year fixed annuity because the quoted rate beats his bank CD. Two years later he expects a major home renovation and may need to help a parent with care costs.
The annuity may still earn exactly what the contract promised—and still be the wrong purchase. The problem is not investment performance. The problem is that he used illiquid money for a liquid job.
That second scenario is why I put liquidity ahead of rate shopping. A contract can work perfectly and still fail the plan.
What If the Insurance Company Fails?
Fixed annuities are not FDIC-insured bank deposits. The insurer is the first line of protection, so financial strength matters.
If a licensed insurer becomes insolvent, state guaranty associations may provide protection subject to state law, coverage limits and exclusions. NOLHGA’s state coverage guide shows why a universal “$250,000 guarantee” is too simplistic: annuity protection levels and special rules vary by state and contract status.
Do not stop at “the principal is guaranteed.” Ask three separate questions:
- What exactly does the contract guarantee?
- How strong is the insurer making that promise?
- What protection would your state guaranty association provide if the insurer failed?
Those are different layers of protection. None should be substituted for FDIC insurance language.
What to Check Before You Sign a Fixed Annuity Contract
I would not choose a “best fixed annuity company” from a static internet list. Rates change, product shelves change, and the highest rate does not tell you whether the contract fits your cash needs.
- Write down the job for this money. One sentence. If the answer is “because the rate is high,” keep working.
- Confirm the exact guaranteed-rate period. Know whether the quoted rate is guaranteed for the full term and what happens afterward.
- Read the surrender schedule in dollars, not percentages. Calculate what an exit would cost on the amount you plan to deposit.
- Check every adjustment and withdrawal rule. Look for market value adjustments, free-withdrawal provisions, waivers and any conditions.
- Check insurer financial strength. The guarantee is an insurance-company obligation.
- Check your state’s guaranty-association rules. Do not assume another state’s limit applies to you.
- Ask how the seller is compensated and what alternatives were considered. You want to know whether you are seeing the best fit or simply the available product.
- Use the free-look period. State rules and contract terms vary, but when a free-look period applies, use it to read the actual policy and unwind the purchase if it is not what you thought you bought.
Investor.gov’s most useful final question is also the simplest: How does the annuity fit into your overall financial plan? That is more important than whether another insurer is advertising an extra fraction of a percent this week.
Bottom Line: Is a Fixed Annuity a Good Fit for You?
A fixed annuity can be a very good tool for a narrow job: protecting a portion of retirement money from direct market losses while earning a contractual fixed rate for a period you can live with.
It becomes a bad tool when the word “guaranteed” causes you to ignore what was traded away—liquidity, potential upside, federal deposit insurance, or purchasing-power flexibility.
My rule is simple: never buy the guarantee until you can name the flexibility you are giving up. If you understand both sides and the money has a clearly defined job, then you are comparing a contract. Before that, you are comparing sales pitches.
Sources
- Investor.gov, Annuities.
- FINRA, Annuities.
- Internal Revenue Service, Publication 575: Pension and Annuity Income.
- FDIC, Deposit Insurance at a Glance.
- National Organization of Life & Health Insurance Guaranty Associations, How You’re Protected.
- National Association of Insurance Commissioners, Annuity Suitability & Best Interest Standard.
- U.S. Treasury, TreasuryDirect: About Treasury Marketable Securities.
- U.S. Treasury, TreasuryDirect: Tax Forms and Tax Withholding.
- Internal Revenue Service, Publication 550: Investment Income and Expenses.
