


An immediate annuity, often called a single premium immediate annuity (SPIA), is an insurance contract that turns one lump sum into scheduled income that typically begins within a year. It can pay for a set period or for life, depending on the contract you choose.
The easy question is, “How much will $100,000 pay me?” The harder question, and usually the more important one, is how much income do you actually need to guarantee?
I’ll never forget the Flemings, a couple who came to my office in 2009 after the market crash had decimated their 401(k)s. They were 67, retired, and terrified. Their number one question wasn’t about growth or returns. It was, “How can we make sure we never run out of money?”
For them, an immediate annuity was part of the answer. But the useful lesson was not “retirees should buy annuities.” It was that we first had to identify the problem they were trying to insure.
That is the decision process I want to give you here. We’ll cover the standard questions the search results answer well, including how a SPIA works, current 2026 payout examples, payout options, taxes, inflation, and insurer risk. Then we’ll deal with the questions that matter once real money is on the table: How much should you annuitize? Which expenses are you trying to cover? How much liquidity can you afford to give up? And is the highest payout actually buying the promises you need?
Quick Answer
An immediate annuity, or SPIA, converts a lump sum into scheduled income that generally begins within a year. It can cover a retirement-income gap for life or for a chosen period, but the tradeoff is usually reduced access to the premium. The right starting question is not what percentage of your portfolio should go into one. Start with the essential expenses that Social Security, pensions, and other reliable income do not already cover, keep enough liquid money outside the contract, and then compare quotes using the same payout option.
Key Takeaways Ahead
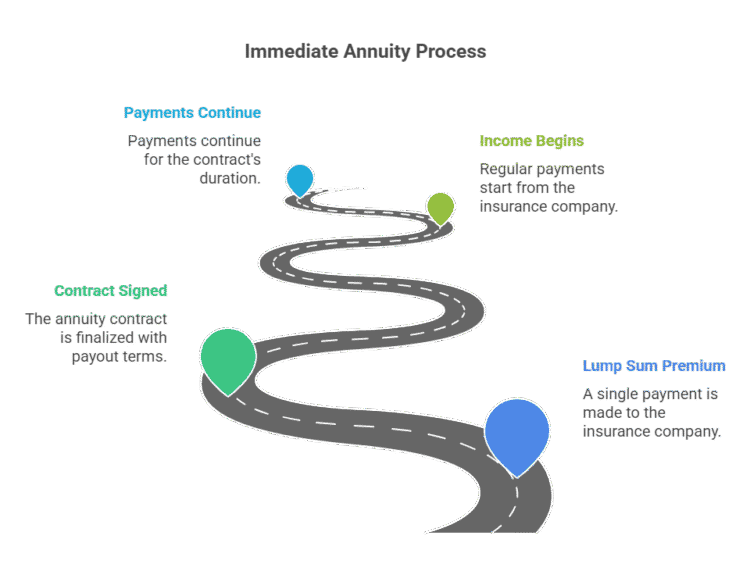
How an Immediate Annuity (SPIA) Works: The 4-Step Process

The basic mechanism is simple. Investor.gov’s annuity guidance describes an annuity as a contract with an insurance company. With an immediate annuity, you generally make one payment and begin receiving income within one year.
- You choose the amount of the lump-sum premium. The money can come from taxable savings or, when the transaction and plan rules allow it, retirement money. Where the money comes from matters later because the tax treatment can be different.
- You choose the payout terms. Life only, joint and survivor, period certain, refund provisions, and inflation adjustments do not provide the same promise. Read the actual contract. I saw people sign some terrible annuity contracts over the years because the sales explanation sounded simpler than the pages they were signing.
- The insurer begins the income. Depending on the contract, payments may begin quickly and are commonly monthly. The analogy I used with clients was this: while your money remains in an investment account, you still own the account value. When you annuitize a lump sum, the experience is closer to creating a private pension with contract-defined income.
- Payments continue under the option you selected. A lifetime option can continue as long as the covered life or lives remain alive. A period-certain option follows the period stated in the contract. Beneficiary protections depend on the option you buy.
That is different from a deferred annuity, which has an accumulation period before income begins. If you want the wider taxonomy, my guide to how other annuity types work covers the broader family without turning this page into an annuity encyclopedia.
For a video slideshow summary of the concept, you can also use the presentation below.
How Much Does a $100,000 Immediate Annuity Pay in 2026?
The payout is usually the first number people want. But the quote depends on age, sex where permitted and used in pricing, premium amount, market pricing, insurer, state, and especially the payout option.
For a concrete benchmark, ImmediateAnnuities.com’s August 5, 2026 rate survey published these illustrative monthly payments for a $100,000 premium at age 65:
| Age 65 payout option | Male best | Male average | Female best | Female average |
|---|---|---|---|---|
| Single life only | $679/mo. | $630/mo. | $649/mo. | $602/mo. |
| Life with 10 years certain | $665/mo. | $618/mo. | $640/mo. | $595/mo. |
| Life with cash refund | $647/mo. | $604/mo. | $626/mo. | $587/mo. |
These are illustrations, not quotes. The survey says rates change often and without notice, and the examples exclude state-specific premium taxes. Your actual quote can differ materially.
Why the Payout Rate Is Not the Same as an Investment Return
This is where a lot of otherwise smart comparisons go sideways. If $100,000 produces $650 a month, that is $7,800 a year of cash flow, or 7.8% of the premium. That does not mean the annuity is earning a 7.8% investment return.
Part of the payment can be your own premium coming back to you. A Society of Actuaries retirement-income primer explains that lifetime annuity income also uses mortality credits: the pooled economics of people who die earlier help support income for people who live longer. The product is built around insurance against longevity, not a brokerage account trying to post the highest return.
So use the payout as a cash-flow number. Do not use it as a shortcut for comparing the annuity with a stock, bond fund, CD, or Treasury yield.
How Much of Your Portfolio Should You Put in an Immediate Annuity?
This is the question I think most annuity articles answer backward. They start with a portfolio percentage, or with what $100,000 pays, and then try to justify the product.
I would start with the guaranteed-income gap:
Example: Size the Income Gap First
Suppose a retired household needs $5,000 a month for essential, non-negotiable expenses. Social Security and a pension already cover $3,800. The uncovered essential-income gap is $1,200 a month.
That does not automatically mean “buy an annuity that pays $1,200.” It tells you what problem you are considering insuring. You can then decide how much of that gap you want guaranteed, how much portfolio risk you are comfortable carrying, and how much liquid capital must stay outside the contract.
This is why I would not tell someone to put 20%, 30%, or 50% of a portfolio into an annuity as a universal rule. Two retirees can have the same $1 million portfolio and completely different needs. One may already have a pension covering housing, food, utilities, and healthcare. The other may have only Social Security and a much larger essential-expense gap.
Before deciding on a premium, also decide how much cash and liquid investment capital you need for emergencies, large purchases, healthcare surprises, family help, and simply changing your mind. If the annuity premium would make the rest of the plan uncomfortably tight, the income guarantee may be solving one problem by creating another.
If you are worried about whether the remaining portfolio can support the rest of your spending, model how long your retirement money may last before treating annuitization as the answer.
And if you have not yet claimed Social Security, compare that decision too. The Social Security Administration’s delayed-retirement-credit table shows an 8% annual credit after full retirement age for people born in 1943 or later, until age 70. That does not automatically make delaying Social Security better, but it means your private-annuity decision should not ignore another source of lifetime income sitting in the same retirement plan.
Make the Income Decision Before the Annuity Decision
If this “income gap first, product second” approach is useful, my newsletter does the same thing with retirement-income choices: identify the constraint, compare the real tradeoff, then ignore the sales noise.
- Know which retirement-income problem you are actually solving.
- Compare guarantees, liquidity, taxes, and flexibility without product jargon.
- See when a simple rule needs to bend for your real numbers.
Get the next practical retirement-income breakdown:
Compare Payout Options Before You Compare Immediate Annuity Quotes

A quote is the price of a particular promise. Change the promise and the payout changes.
| Payout option | What it protects | Typical effect on starting income | Main tradeoff |
|---|---|---|---|
| Life only | Income for one lifetime | Usually highest among comparable lifetime choices | Payments generally stop at the annuitant’s death |
| Joint and survivor | Income while either covered spouse remains alive | Lower than comparable single-life income | You give up some starting income to extend lifetime protection to two people |
| Life with period certain | Lifetime income plus a minimum payment period | Usually lower than comparable life-only income | Beneficiary protection costs some starting payout |
| Cash refund | A remaining premium value for beneficiaries under contract terms | Usually lower than comparable life-only income | More legacy protection, less initial income |
| Inflation/COLA feature | Some future purchasing power | Lower initial payment | You accept less income now in exchange for scheduled increases later |
That is why “Who pays the most?” is not yet a useful comparison. First make the contracts comparable: same premium, same age and lives covered, same payment start date, same survivor terms, same refund or guarantee period, and the same inflation feature.
A higher payout can be a worse deal if it buys the wrong promise. Life only may produce more monthly income than a joint-and-survivor contract, but that does not help if the surviving spouse is the person you most need to protect.
If you want to go deeper on optional guarantees beyond the basic payout structure, see my guide to annuity riders and optional guarantees. Keep that separate from the first decision here: what income promise are you actually buying?
How Are Immediate Annuity Payments Taxed?
The answer depends heavily on where the premium came from.
If You Buy the Annuity With After-Tax Money
For a nonqualified commercial annuity bought with after-tax money, IRS Publication 939 explains the General Rule used for certain periodic annuity payments. In plain English, part of a payment can be treated as a tax-free return of your net cost in the contract, while the rest is taxable income. The exact tax-free portion depends on the contract and the applicable IRS calculation.
If the Premium Comes From a Traditional IRA or Other Pretax Retirement Money
The tax picture changes. IRS Publication 575 notes that traditional IRA distributions follow IRA tax rules. If the IRA consists entirely of deductible or pretax money, distributions are generally taxable as ordinary income when received. If you have after-tax basis in the IRA, the result can be different.
That is why I would not use a single “exclusion ratio” sentence for every immediate annuity. The account source matters. These are federal rules, and your state tax treatment can differ, so this is one of the places where a tax professional who can see the actual funding source and contract can earn the fee.
Immediate Annuity Risks: What You Give Up for Guaranteed Income
The word guaranteed can make an annuity sound like the risk disappeared. It didn’t. You changed the risk.
Liquidity: You Are Trading Access for Income
Most immediate income annuities are designed to exchange liquidity for contractual income. Depending on the contract, you may have limited or no access to the premium after annuitization. Refund or guarantee features can protect beneficiaries in specific ways, but they are not the same thing as keeping a brokerage account you can tap whenever you want.
This is why I want the liquidity budget decided before the annuity budget. Keep enough accessible money outside the contract for the things retirement can throw at you that do not arrive on a neat monthly schedule.
Inflation: A Fixed Check Buys Less Over Time

A fixed $1,500 monthly payment still says $1,500 on the statement years from now, but rising prices reduce what that money can buy. Some contracts offer scheduled increases or cost-of-living features, but those protections usually start with a lower initial payment.
Legacy: More Beneficiary Protection Usually Means Less Starting Income
A life-only payout is built to maximize income for the covered life, not to maximize what heirs receive. Period-certain and refund options can change that, but they also change the payout. This is the same quote-comparison problem from the last section showing up again: you cannot compare the income without comparing the promise attached to it.
Insurer Strength: The Guarantee Comes From the Insurance Company
Investor.gov is explicit that an insurer’s annuity obligations depend on its financial strength and claims-paying ability. In my own practice, I never recommended an insurer with a financial-strength rating below “A.” That was my screening preference, not a regulatory safe-harbor and not a guarantee that an A-rated company cannot fail.
I would still check ratings from organizations such as AM Best, understand the issuer, and avoid concentrating more guaranteed-income exposure with one company than you are comfortable having there.
Watch Out
State life and health insurance guaranty associations can provide protection if an insurer fails, but the limits and contract treatment are controlled by state law. NOLHGA’s state-by-state protection information shows why you should check your own state rather than assume one national annuity limit. Guaranty-association coverage should not be treated as a substitute for choosing a financially strong insurer.
Who Should Consider an Immediate Annuity and Who Probably Shouldn’t?
An immediate annuity tends to be more useful when the problem is income certainty, not when the real goal is maximizing liquidity, market growth, or inheritance.
You may have a stronger reason to investigate a SPIA when:
- Social Security and pensions do not fully cover essential monthly expenses.
- You value a predictable paycheck-like stream more than retaining control of every dollar used to create it.
- You have enough liquid assets outside the proposed annuity for emergencies and irregular spending.
- Longevity risk, including the possibility of living well into your 90s, matters more to you than maximizing what remains for heirs.
- You understand the payout option, insurer, tax treatment, and what happens at death before signing.
You have a stronger reason to slow down when:
- Your reliable income already covers essential spending and another guarantee does not solve a clear problem.
- The proposed premium would leave you short on liquid money.
- A large bequest is a top priority and the payout option does not protect that goal.
- You are choosing primarily because the headline payout looks higher than an investment yield.
- You cannot explain exactly what happens to the income if you die early, your spouse outlives you, or inflation stays high.
None of those bullets is a suitability test by itself. They are the questions I would want answered before someone exchanges a meaningful amount of liquid retirement savings for a lifetime contract.
My Golden Rule for Immediate Annuities: Solve for Needs, Not Greed
After nearly 30 years of advising clients, my golden rule is still the same: Solve for needs, not for greed.
An immediate annuity is not a magic investment that turns retirement into a risk-free spreadsheet. It is an insurance contract designed to transfer a specific risk, usually the risk that your need for income outlasts the assets you are comfortable spending.
So bring the decision back to three questions:
- What essential monthly spending is not already covered by Social Security, pensions, and other reliable income? That is the income gap worth considering.
- How much liquid money must remain outside the annuity? Set that boundary before anyone tells you how large the premium should be.
- Are you comparing the same promise? Put life-only, joint, refund, period-certain, and inflation features on equal terms before comparing payouts.
If those three answers point toward a SPIA, use it surgically. Create the income floor you actually need and let the rest of your broader retirement plan handle the jobs that require liquidity, growth, flexibility, and legacy.
If you remember one thing, make it this: The biggest annuity mistake is not getting a slightly lower payout. It is solving the wrong problem with a lifetime contract.
Sources
- Investor.gov: Annuities
- ImmediateAnnuities.com: 2026 payout rate tables by age
- IRS Publication 939: General Rule for Pensions and Annuities
- IRS Publication 575: Pension and Annuity Income
- Social Security Administration: Delayed Retirement Credits
- NOLHGA: State Guaranty Association Protection
- Society of Actuaries Research Institute: Retirement Income Strategy Design and Evaluation
