

If you are working past 65 and still contributing to a Health Savings Account, Medicare can reach backward and erase months you thought were HSA-eligible. The answer is not to automatically stop contributions seven months before retirement.
The controlling date is the month your Medicare coverage actually begins. For premium-free Part A, Medicare.gov says delayed enrollment can make Part A start up to six months earlier. It cannot start before your first month of Medicare eligibility. IRS Publication 969 says your HSA contribution limit is zero for every month you are enrolled in Medicare.
The problem isn’t Medicare itself; it’s the timeline.
If Medicare starts around age 65, make your last HSA contribution for the last month before Medicare begins.
If you delay premium-free Part A until at least six months after 65, the 2026 Medicare & You handbook says to stop HSA contributions six months before the month you apply. Medicare.gov gives the same six-month warning for retirement or a Social Security/RRB benefit application. Your employer’s HSA contributions count too.
Key Takeaways Ahead
When does Medicare make you ineligible to contribute to an HSA?
Medicare coverage, not your 65th birthday by itself, is what ends your ability to make new HSA contributions.
IRS Publication 969 says your HSA contribution limit becomes zero beginning with the first month you are enrolled in Medicare. That includes months covered retroactively. You can keep the money already in your HSA and use it for qualified medical expenses after Medicare begins. The restriction is on new contributions once Medicare coverage begins; Medicare does not force you to close or spend down the HSA.
That distinction matters if you keep working past 65 with an HSA-eligible high-deductible health plan. Medicare.gov says some people with current job-based coverage can delay Medicare.
Do not assume that rule fits every employer plan. My working-past-65 Medicare guide covers the employer-size and Part B enrollment questions.
For this HSA decision, use a month-by-month test:
- Were you enrolled in Medicare for the month? If yes, your HSA contribution limit for that month is zero.
- If not, were you otherwise HSA-eligible under the IRS rules?
- If yes, that month can add contribution room based on your coverage type and any applicable age-55 catch-up amount. The IRS Form 8889 instructions use this month-by-month method.
This is why a blanket rule like “everyone over 65 must stop contributing” is wrong. It is also why “just stop seven months early” gives up precision the IRS rules actually let you keep.
Does Medicare Part B also stop HSA contributions?
Yes. The IRS rule is based on being enrolled in Medicare, not only Part A. Once you are enrolled in Medicare, your HSA contribution limit is zero for those months.
The six-month lookback discussed on this page is a premium-free Part A timing issue. Part B does not create that same six-month retroactive Part A lookback. That is why this article keeps the timing discussion centered on Part A.
How the Medicare Part A 6-month lookback changes your HSA stop date
The six-month rule comes from premium-free Medicare Part A retroactivity. If you sign up after 65, Part A can reach back as far as six months. It cannot start before your first month of Medicare eligibility.
If you are already receiving Social Security before 65, SSA Medicare guidance says you are generally automatically enrolled in Part A when you reach Medicare eligibility. In that situation, do not plan around a delayed six-month Part A lookback. Use the actual Medicare start month and make your last HSA contribution for the month before coverage begins.
That creates three common timing patterns:
| Your situation | Medicare timing | HSA planning rule |
|---|---|---|
| You enroll during your Initial Enrollment Period | Part A generally starts around your Medicare eligibility month | Make your last HSA contribution for the month before Part A begins. |
| You delay Medicare, but apply less than six months after turning 65 | Retroactivity cannot reach earlier than your first Medicare-eligible month | The age-65 eligibility floor limits the lookback. Check the exact Part A effective month. |
| You apply six or more months after turning 65 | Premium-free Part A can generally reach back six months | Stop HSA contributions six months before the month you apply. |
There is one birthday wrinkle worth checking. Medicare says if your birthday is on the first day of a month, your Medicare eligibility can begin the month before the month you turn 65. The 2026 Medicare & You handbook reflects that in its HSA timing chart.
What does not belong in this calculation is an automatic seventh “safety month.” The HSA last-month rule is a separate IRS provision that can let certain eligible people use a full-year contribution limit based on December 1 coverage, subject to a testing period. It does not create a universal extra month that everyone approaching Medicare must subtract.
For a delayed premium-free Part A application, the lookback can reach up to six months. The age-65 eligibility floor can make it shorter. There is no universal seventh month to add.
How much can you contribute to your HSA in the year Medicare starts?
For 2026, IRS Revenue Procedure 2025-19 sets the federal HSA contribution limits at $4,400 for self-only coverage and $8,750 for family coverage. An HSA-eligible person age 55 or older can generally add the $1,000 catch-up contribution, but contribution room still depends on eligible months.
The clean way to think about a transition year is monthly. If your HDHP coverage type and other eligibility facts stay the same during your eligible months, this shortcut illustrates the basic math:
Annual HSA limit for your coverage and age × eligible months ÷ 12
Three things can change the math:
- your coverage type changes mid-year
- you’re married with family-coverage allocation rules
- another eligibility fact changes.
If any of those apply, use the Form 8889 Line 3 worksheet instead of the shortcut above.
Medicare enrollment is individual. If one spouse enrolls in Medicare first, that spouse loses HSA contribution room for Medicare-covered months. The other spouse can still have contribution room if they remain HSA-eligible.
Family-coverage allocation rules can change the calculation, so do not automatically zero out the household’s HSA limit. Use the Form 8889 worksheet for the affected year.
Then account for contributions already made by you, your employer, or anyone else on your behalf. Employer contributions do not sit outside the limit. IRS Publication 969 specifically says they reduce what remains available for you to contribute.
Assume you are 68, have self-only HSA-eligible coverage, and your premium-free Part A effective date becomes April 1, 2026.
You were HSA-eligible for January, February, and March. For illustration, your 2026 self-only limit including the age-55 catch-up is $5,400. Three eligible months would produce a $1,350 contribution limit before any other adjustments:
$5,400 × 3 ÷ 12 = $1,350
Now suppose $3,000 had already gone into your HSA for 2026 between your payroll deductions and employer contributions. The rough excess would be $1,650 before considering any other facts that affect your Form 8889 calculation.
That is the number to reconcile, not “whatever I contributed during the last six paychecks.” HSA eligibility is monthly, while payroll contributions can arrive on a completely different schedule.
What if you do not know when you will retire?
This is where the tidy six-month advice collides with real life.
If your retirement date is fixed, the planning is simple: work backward from the application and Part A effective dates, then stop both employee and employer HSA contributions on time.
If your job could end next month or eighteen months from now, no single date gives you both perfect certainty and maximum HSA contribution room.
Stop too early and you may give up legitimate HSA tax benefits. Keep contributing and an unexpected retirement can create an excess that must be corrected.
My planning bias is not to invent certainty that does not exist. If the retirement date is unknown, keep a month-by-month HSA ledger. Know what your employer is contributing. Understand the excess-contribution process before you need it.
You may value simplicity more than squeezing out every last dollar of HSA contribution room. In that case, stopping earlier can be a reasonable administrative choice.
That is a tradeoff, not a hidden IRS rule.
One more coordination point: SSA Medicare guidance confirms that applying after 65 can trigger premium-free Part A retroactivity. If you are deciding when to take Social Security benefits, make that decision with the HSA timeline in view rather than treating them as separate paperwork events.
Keep Medicare and HSA Dates From Colliding
The expensive part of this rule is rarely the six-month concept itself. It is coordinating the Part A effective date, payroll HSA deposits, employer contributions, and the tax-year correction window. I send readers plain-English retirement and Medicare notes built around exactly those timing collisions.
- Medicare enrollment dates that change HSA eligibility
- HSA contribution and correction rules before they become tax problems
- Social Security and Medicare timing decisions that interact behind the scenes
How to fix excess HSA contributions after Medicare is backdated
If you discover that Medicare Part A was backdated into months when HSA contributions were made, start with the tax math, not a normal HSA withdrawal.
1. Confirm the Part A effective date
Use your Medicare record or award notice to identify the actual month Part A began. Do not assume the application month is the coverage month.
2. Recalculate your allowed HSA contribution
Use the IRS Form 8889 contribution-limit method to determine how many months you remained HSA-eligible and the contribution room for those months. Include employee payroll contributions and employer HSA contributions in the reconciliation.
3. Calculate the excess
Compare total contributions for the tax year with your allowed contribution limit. IRS Form 5329 instructions show that an excess can include amounts contributed by you or on your behalf, plus excess employer contributions.
4. Ask the HSA custodian for a return of excess contribution
Do not treat the correction as an ordinary HSA distribution. Tell the custodian you are correcting an excess contribution.
The IRS allows a timely correction when the excess and the income earned on it are withdrawn by the tax-return due date, including extensions.
Custodian procedures differ, so use the provider’s excess-contribution correction process rather than guessing at the earnings calculation yourself.
5. Report the correction on the right tax forms
Form 8889 is used to report HSA contributions and calculate the HSA deduction and contribution limit. Form 5329 Part VII is the IRS section for the additional tax on excess HSA contributions.
That corrects an important paperwork trap: there is no “Part VII of Form 8889” for the 6% excess-contribution excise tax.
6. Do not ignore an excess that remains in the HSA
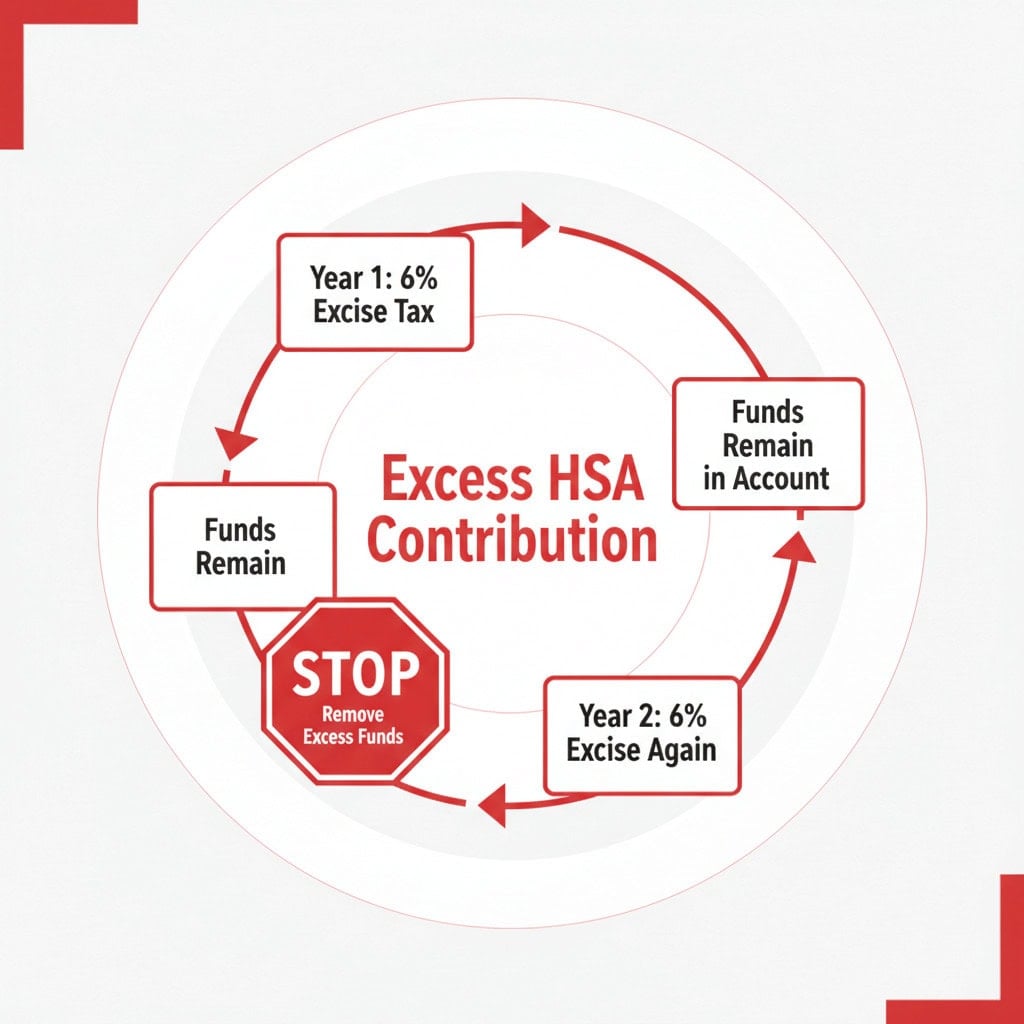
IRS Publication 969 says excess HSA contributions are generally subject to a 6% excise tax for each tax year the excess remains in the account. The tax is not automatically a one-time admission fee.
If you already filed the return, or the excess crosses tax years, the correction gets more complicated. Current Form 5329 instructions say that if you timely filed the return without withdrawing the excess, you can still make the corrective withdrawal no later than six months after the original tax-return due date, excluding extensions. That route requires an amended return marked “Filed pursuant to section 301.9100-2” and the related earnings and form changes the instructions require.
Use the Form 8889 and Form 5329 instructions for the affected tax year. Do not rely on a generic April 15 rule.
Your Medicare-HSA transition checklist
Before the Medicare application or retirement paperwork goes in, run this list:
- Find your expected Medicare Part A effective month. If you are well past 65, account for up to six months of retroactivity. If you are still working, confirm how your employer coverage coordinates with Medicare before assuming you can delay enrollment. This matters especially with employers under 20 employees. See my working-past-65 Medicare guide.
- Check the age-65 floor. Retroactive Part A cannot start before your first Medicare-eligible month.
- Coordinate Social Security timing. A Social Security or RRB benefit application after 65 can affect the Part A start date.
- Tell payroll and HR. Stop both your payroll HSA contributions and employer HSA contributions by the required month.
- Recalculate the transition-year HSA limit. Use eligible months, your coverage type, and any applicable age-55 catch-up.
- If contributions overshot the limit, use the custodian’s excess-contribution correction process. Do not make a normal withdrawal and hope the tax forms sort themselves out.
- Verify Form 8889 and Form 5329 for the affected tax year. Forms and line numbers can change, so use the current version when you file.
The best question is not “How many months before retirement should I stop?” It is: What month will Part A actually begin, and how many HSA-eligible months does that leave me?
Once you answer that, the rest is arithmetic and paperwork.
Sources
- Medicare.gov, Working past 65.
- Medicare.gov, When does Medicare coverage start?.
- Centers for Medicare & Medicaid Services, Medicare & You 2026.
- Internal Revenue Service, Publication 969 (2025), Health Savings Accounts and Other Tax-Favored Health Plans.
- Internal Revenue Service, Revenue Procedure 2025-19, 2026 HSA inflation-adjusted limits.
- Internal Revenue Service, Instructions for Form 5329 (2025), Part VII, excess HSA contributions.
- Social Security Administration, When to sign up for Medicare.
- Internal Revenue Service, Instructions for Form 8889 (2025).
- Centers for Medicare & Medicaid Services, Medicare’s Coordination of Benefits: Getting Started, employer-size rules for who pays first.
