

If you want to know how to stop spending money, do not start by demanding more willpower from yourself. Start by identifying what happens before the purchase: the trigger, the story you tell yourself, and how easy it is to buy.
After nearly three decades as a financial planner, here is the confession I wish more money professionals made: most people who overspend already know they should spend less. The purchase makes sense in the moment; the consequence arrives later. A budget can expose that gap, but it cannot close it by itself.
Overspending often follows a loop: trigger → story → easy transaction → short-term reward → delayed consequence. To interrupt it, make spending visible, automate the money that matters first, add friction to impulse purchases, and deliberately fund the spending you actually value.
I think of Pat and John from South Florida. From the outside, they looked successful: a beautiful home, newer cars, vacations, the whole picture. Underneath it, they were carrying six figures of debt with almost nothing saved. They looked rich. They were financially fragile.
Key Takeaways Ahead
Why Overspending Feels Reasonable in the Moment
Overspending is easiest to understand when you stop treating every purchase as a miniature math test. A lot of spending is an attempt to solve a different problem: boredom, stress, comparison, convenience, celebration, loneliness, identity, or the feeling that you have earned a reward.
Research on problematic and compulsive buying consistently finds that buying can be used to regulate internal states and provide short-term relief, even when the longer-term consequences are negative. That does not mean everyone who impulse-buys has a disorder. It means the emotional payoff from buying is real enough that “just stop” is weak advice. A clinical expert-consensus paper on compulsive buying-shopping disorder specifically identifies using buying to regulate internal states as one of the recurring features in the severe end of the behavior.
The other problem is timing. The reward is now. The bill, regret, or lost savings opportunity is later. That gap is where present bias thrives. NBER research on present bias and credit-card paydown found that short-run impatience helps explain why people fail to stick to self-set debt-paydown plans.
The purchase is usually not the whole decision. It is the final click in a chain of decisions that started earlier—when you were tired, stressed, scrolling, comparing, or telling yourself a story about why this one purchase did not really count.
The Spending Loop: Trigger, Story, Purchase, Relief
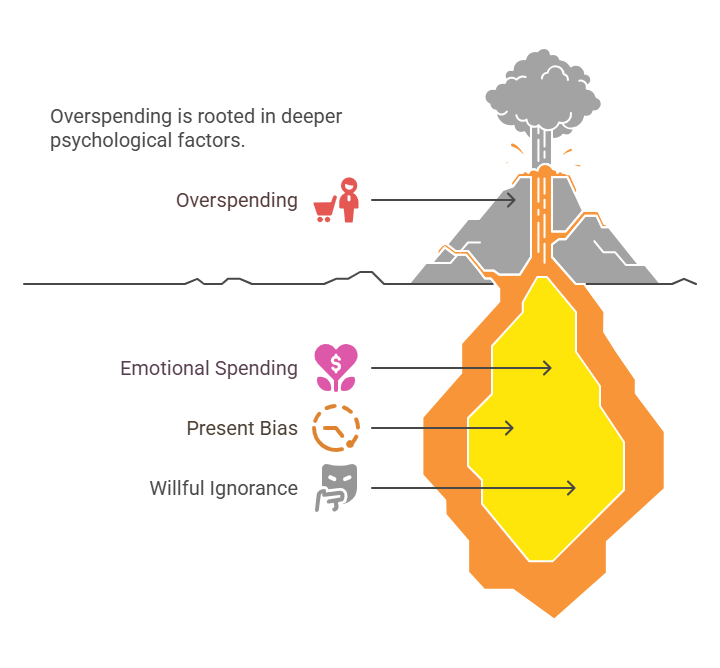
Here is the model I would put a box around:
- Trigger: Something changes your state. You are stressed, bored, celebrating, scrolling social media, or staring at an email that says “last chance.”
- Story: Your brain gives the purchase a reason: “I deserve it,” “It is on sale,” “I will pay it off next month,” “Everyone else has one,” or “This will make life easier.”
- Easy transaction: Stored cards, one-click checkout, buy-now-pay-later, delivery apps, and saved passwords remove the pause that used to exist between wanting and buying.
- Short reward: You get relief, excitement, convenience, status, novelty, or a sense of control.
- Delayed consequence: The card balance, lower savings, clutter, guilt, or cash-flow squeeze shows up later—when the emotional reward is already gone.
The Consumer Financial Protection Bureau has found a similar practical disconnect: people often want to manage spending and may even have a budget, but the budget is not necessarily present in the decision at the moment they spend. Its consumer research found strong interest in real-time feedback because people believed it could help curb impulse spending and reduce uncertainty. CFPB’s research on managing spending is a useful reminder that the problem is often execution, not ignorance.
A Planner’s Confession: A Budget Is Not Enough
Early in my career, I thought the answer to overspending was mostly a better budget. Give people the right categories, show them the numbers, and the behavior should follow.
That is necessary. It is not sufficient.
A budget tells you what you intended to do. Your spending environment decides how hard it is to follow through.
The CFPB’s spending tracker advice is deliberately simple: look at checking and credit-card history, track spending for at least a couple of weeks, and identify expenses that surprise you or no longer feel necessary. That “financial mirror” is still the right first move because you cannot redesign a pattern you refuse to look at. CFPB’s spending-tracker guidance supports that basic sequence.
But after the mirror comes the machinery.
How to Stop Spending Money Without Relying on Willpower
The goal is to make good decisions easier and impulsive decisions slightly more annoying. You are not trying to turn yourself into a monk. You are changing the defaults.
1. Make the spending visible before you try to cut it
Review the last 30 days of checking and credit-card activity. Do not begin by judging every line item. Label purchases by what caused them: convenience, boredom, stress, social pressure, genuine value, recurring bill, or forgotten subscription.
That is more useful than simply labeling everything “good” or “bad.” It tells you which trigger deserves a system change.
2. Pay Future You before the spending environment gets a vote
Automate the important transfers soon after income arrives: emergency savings, retirement contributions, debt payments, sinking funds, or other priorities you have already chosen.
Behavioral research on defaults shows why this matters. Automatic enrollment and default choices can meaningfully change saving behavior because they reduce the need to make the same good decision over and over. The exact effect varies by setting, and defaults are not magic, but the larger lesson is useful: environment beats repeated intention surprisingly often. NBER research on default effects and saving behavior is one of the classic demonstrations.
3. Put friction in front of your weak spots
- Delete shopping apps you open reflexively.
- Remove stored card numbers from your browser and favorite stores.
- Turn off promotional push notifications and marketing texts.
- Unsubscribe from sale emails that reliably trigger browsing.
- Use a separate debit card or checking account for discretionary spending if that makes the boundary more visible.
- For nonessential purchases above your chosen threshold, impose a 24- or 48-hour waiting period.
None of those steps is profound. That is the point. A good spending system should not require a motivational speech every Tuesday.
4. Stop pretending all discretionary spending is equally bad
The wealthiest client I ever worked with was a man named Frank. What stood out was not that he refused to spend. He spent generously on the things he cared about and was almost indifferent to the things he did not.
That is a healthier model than trying to squeeze every pleasure out of your budget. I want a spending plan to tell you, “Yes, spend here,” just as clearly as it tells you where to cut.
Do not ask, “Can I afford this?” only. Ask two questions: “What problem am I trying to solve with this purchase?” and “Would I still choose it if I had to pay for it from this month’s available cash?”
If you need a short reset while you rebuild those boundaries, use my no-spend challenge guide. The purpose is not punishment. It is to make automatic spending visible again.
Use the 50/30/20 Calculator as a Reality Check
Once you understand the behavioral loop, the numbers become much more useful. The 50/30/20 framework is not a moral law and it will not fit every household, but it can show whether your current spending is crowding out savings or essential expenses.
50/30/20 Budget Rule Calculator
Compare your monthly spending with the 50/30/20 budgeting guideline. The percentages are flexible reference points, not requirements.
Your Budget Snapshot
This comparison shows how your entered amounts line up with the guideline.
| Category | Guideline target | Your amount | Comparison |
|---|---|---|---|
| Needs | $0 50% | $0 0% of income | — |
| Wants | $0 30% | $0 0% of income | — |
| Savings and additional debt repayment | $0 20% | $0 0% of income | — |
Needs
Actual percentage of monthly income
Wants
Actual percentage of monthly income
Savings and debt repayment
Actual percentage of monthly income
What your numbers suggest
About the guideline: The 50/30/20 approach is a general budgeting framework, not a required allocation. Housing costs, healthcare, caregiving, debt, taxes, location, income level, and retirement circumstances can make different percentages more appropriate.
This calculator provides educational estimates based only on the amounts entered. It does not provide personalized financial, investment, tax, legal, insurance, or debt advice.
See a problem or have a suggestion? Contact Michael Ryan Money .
If the calculator shows a large gap, do not immediately cut ten categories by 5%. Go back to the loop. Find the two or three spending patterns producing most of the drift and redesign those first.
For a more detailed household plan, use my guide to building a spending plan or budget.
When Overspending Is More Than a Budgeting Problem
There is an important line between ordinary overspending and buying behavior that feels uncontrollable, repetitive, secretive, or seriously damaging.
If shopping is causing major debt, relationship conflict, hiding packages or purchases, repeated failed attempts to stop, or a feeling that buying is the main way you regulate distress, a better spreadsheet may not be the next tool you need. Research on compulsive buying describes patterns of diminished control, persistent urges, buying to regulate internal states, and continued behavior despite harm. That expert-consensus research is not a self-diagnosis checklist, but it is a good reason to take severe patterns seriously.
In that situation, consider talking with an appropriate mental-health professional and, if debt has become part of the problem, a reputable nonprofit credit counselor. The financial plan and the behavioral support can work together.
Your 7-Day Spending Reset
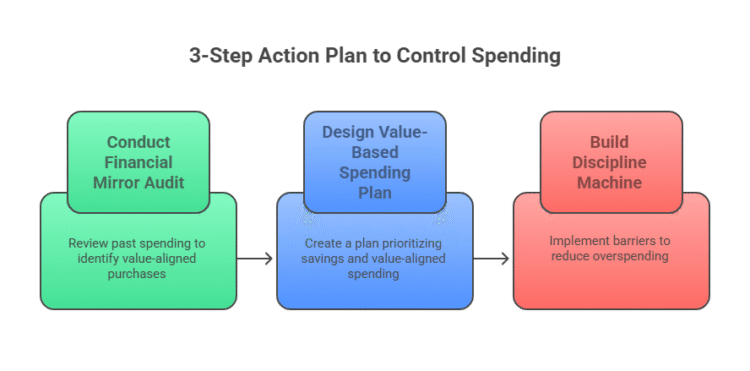
- Day 1 — Audit: Review the last 30 days. Circle the five purchases you regret most and the five you value most.
- Day 2 — Find the triggers: For each regret purchase, write what happened immediately before it: stress, boredom, scrolling, sale email, convenience, social comparison, or something else.
- Day 3 — Remove one-click spending: Delete saved cards, apps, notifications, or email triggers tied to your biggest weak spot.
- Day 4 — Automate one priority: Move one savings, debt, or investing transfer closer to payday so it happens before discretionary spending.
- Day 5 — Create a waiting rule: Choose a dollar threshold and a waiting period for nonessential purchases.
- Day 6 — Protect what you love: Pick the one or two categories you genuinely value and fund them intentionally. This prevents a spending plan from feeling like permanent deprivation.
- Day 7 — Review the system: Ask what became easier, what still triggered you, and which one environmental change would remove the most temptation next week.
The Goal Is Not to Become Cheap
The point of controlling spending is not to prove how little you can live on. It is to stop spending money by accident so you can spend it on purpose.
That is the distinction I wish I had understood earlier as a planner. A budget is a map. It cannot drive the car for you. The real work is building a system where the route you say you want is also the easiest route to follow.
When your spending reflects your priorities instead of your triggers, saving stops feeling like the thing that happens only if there is money left over.
Sources
- Consumer Financial Protection Bureau: Consumer insights on managing spending
- Consumer Financial Protection Bureau: Track your spending with this easy tool
- Proposed diagnostic criteria for compulsive buying-shopping disorder: expert consensus study
- NBER: Present bias and credit-card paydown
- NBER: Default effects and 401(k) savings behavior
