
Wondering how to max out your Roth IRA in 2026? First confirm how much you are legally allowed to contribute, then turn that annual number into a funding pace your cash flow can actually support. The 2026 IRA limit is $7,500 if you are under 50 and $8,600 if you are 50 or older. Your personal Roth IRA limit can be lower because of taxable compensation or income eligibility.
The number is the easy part. The system is what makes or breaks the goal. In nearly three decades of financial planning, I learned to separate the annual target from the funding method. A plan you can keep for 12 months beats a dramatic January transfer that leaves the rest of your finances scrambling.
The practical answer
Know your legal contribution room. Pick a monthly, paycheck, or variable-income pace. Automate what you can. Use extra cash to close the gap. Then check the account twice: once to confirm the contribution arrived, and again to confirm the money was actually invested.
On This Page
- How Much Do You Need to Max Out a Roth IRA in 2026?
- How to Max Out a Roth IRA: Pick a Funding Pace
- Should You Max Out a Roth IRA Before Everything Else?
- The Step People Miss: Make Sure the Roth IRA Money Is Invested
- What If Your Income Is Too High for a Direct Roth IRA?
- After You Max Out the Roth IRA, Where Does the Next Dollar Go?
- Questions About Maxing Out a Roth IRA
- Make the Roth IRA System Automatic
- How We Verified This
How Much Do You Need to Max Out a Roth IRA in 2026?
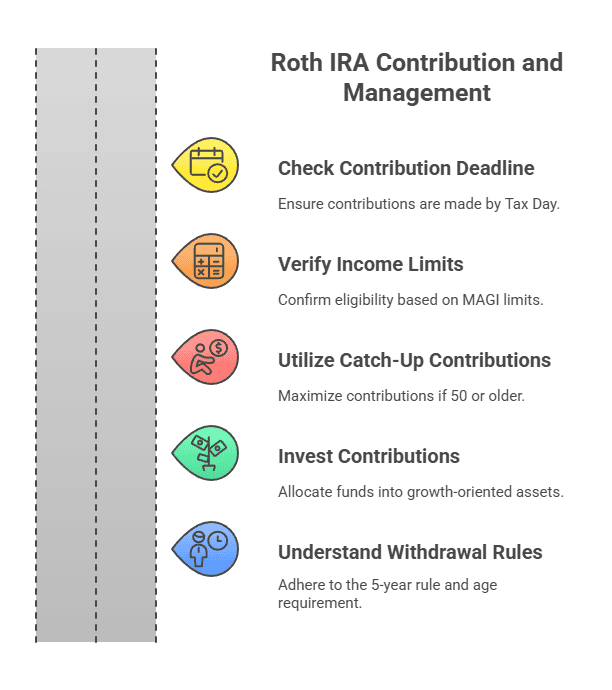
The IRS set the 2026 IRA contribution limit 1 at $7,500. If you are age 50 or older by the end of 2026, the catch-up contribution is $1,100, for a total of $8,600.
That is the ceiling, not automatically your personal number. Your regular IRA contributions generally cannot exceed your taxable compensation for the year, and the amount you can contribute directly to a Roth IRA can be reduced or eliminated at higher modified adjusted gross income levels. If you need the rule details, use the 2026 Roth IRA contribution limit guide and the Roth IRA income limit guide. This page picks up after you know your available contribution room.
How to Max Out a Roth IRA: Pick a Funding Pace
You do not get extra credit for contributing on January 1. If the money is already available and using it will not weaken the rest of your plan, funding early is reasonable. If you have to spend months piling up cash just so you can make one big contribution, a steady schedule is usually the cleaner system.
For 2026, these are the contribution targets if you want to spread the annual maximum across the year:
| Schedule | Under age 50 | Age 50+ |
|---|---|---|
| Annual | $7,500 | $8,600 |
| Monthly | $625.00 | $716.67 |
| Twice monthly | $312.50 | $358.33 |
| Every two weeks | $288.46 | $330.77 |
| Weekly | $144.23 | $165.38 |
Automate the amount you can actually sustain
For most people, automation is the simplest starting point because it turns “find $7,500” into a recurring cash-flow decision. Monthly is easy to remember. A paycheck schedule can feel even more natural because the retirement contribution happens when the income arrives.
If $625 a month is too aggressive, do not pretend it is not. Start with an amount your budget can carry. You can increase it after a raise, after a debt payment disappears, or when other cash flow opens up.
If you fall behind, use the remaining-contribution formula
You do not have to guess what it takes to catch up. Use this simple formula:
Catch-up math
Remaining Roth IRA contribution room ÷ remaining planned deposits = new deposit target.
If you have $3,600 of contribution room left and six monthly deposits remaining, the catch-up target is $600 per month. If that number does not fit, keep contributing what you can instead of creating a new cash-flow problem.
Use windfalls to close a gap, not to rescue a bad plan
A bonus, commission check, tax refund, or other genuine windfall can help when normal monthly cash flow cannot carry the full target. For variable-income households, I prefer a percentage rule over a fixed-dollar promise. Earmark a reasonable percentage of irregular income for retirement until you reach the annual target, while keeping enough cash for taxes and near-term obligations.
Use a lump sum when the cash is already available
If the money is already set aside and the contribution fits your plan, a lump sum can be simple. Fund it, invest it, and move on. What I would not do is strain the current budget just to say you maxed the Roth on the first business day of the year.
Enter three numbers you already know. The tool shows your remaining target, per-deposit pace, whether you’re on track, and what changes if you add a windfall or adjust the contribution.
Try your numbers, then move the slider. The result updates instantly.
Your 2026 Roth mission
$833 per deposit
Six equal deposits would finish your remaining 2026 contribution target.
What if I change the pace?
Move the slider to see your projected finish and shortfall immediately.
At $500 per deposit, you would contribute another $3,000 and finish $2,000 short of the annual target.
What if I get a bonus, refund, or commission?
Test how one extra contribution changes the pace you need afterward.
Using $500 of that windfall would reduce the remaining pace to about $750 per deposit.
Should maxing the Roth be the next cash-flow target?
This is a quick guardrail, not individualized advice. Check anything that is also competing for the same dollars.
One last check: did “contributed” actually become “invested”?
Funded and invested are two different checkpoints. Hitting the contribution limit while the money sits unintentionally in cash is only half the job.
Should You Max Out a Roth IRA Before Everything Else?
Not automatically. “Max the Roth” is a savings target, not a universal order of operations. If you are passing up an available employer match, running with almost no emergency cash, or carrying expensive debt because every spare dollar is going to the IRA, the maximum can become the wrong short-term goal.
Michael’s rule of thumb
Do not create a cash-flow problem to solve a retirement-saving problem. Protect the parts of the plan that keep one surprise from forcing you into new debt. Then push the Roth contribution higher as your cash flow allows.
If your employer offers matching contributions, make sure you understand what you must contribute to receive the full match. If you are deciding how the Roth IRA fits beside a workplace plan, see how a Roth IRA and 401(k) can work together.
The Step People Miss: Make Sure the Roth IRA Money Is Invested
This is the quiet mistake worth checking today. A Roth IRA is an account. Contributing money to the account does not necessarily mean you bought the investment you intended to own. Depending on the custodian and your setup, a contribution can land in a settlement or cash position until you place an investment order or establish automatic investing.
Open the account and verify two separate things. Did the contribution arrive? Then ask, is that money invested according to my plan? Hitting the annual contribution number while the balance sits unintentionally in cash is only half a win.
What If Your Income Is Too High for a Direct Roth IRA?
If your modified adjusted gross income reduces or eliminates a direct Roth IRA contribution, stop before automating the full annual amount. Check the current Roth IRA income limits first.
A backdoor Roth IRA may be available to some higher-income households, but that is a conversion strategy with separate tax-reporting and pro-rata issues. This page does not try to turn that into a three-step shortcut. If that is your situation, use the Roth conversion rules guide before executing the transaction.
After You Max Out the Roth IRA, Where Does the Next Dollar Go?
Maxing the Roth IRA is a milestone, not the end of the plan. The next dollar might belong in a workplace retirement plan, an HSA if you are eligible, or a taxable brokerage account. The right choice depends on benefits, taxes, liquidity needs, debt, and when you expect to use the money.
The important distinction is that the IRA contribution limit and the employee 401(k) deferral limit are separate. You can contribute to both in the same year if you are otherwise eligible. That is why “I maxed my Roth” should trigger a next-question check, not an automatic stop sign for retirement saving.
Questions About Maxing Out a Roth IRA
What if I cannot max out my Roth IRA this year?
Contribute what your cash flow can support. There is no rule saying a partial Roth IRA contribution is a failure. Automate a sustainable amount, increase it when cash flow improves, and use the catch-up formula if you want to close the gap later.
What happens if I contribute more than my Roth IRA limit?
An excess IRA contribution can trigger a 6% excise tax for each year the excess remains in the account. Do not assume a normal withdrawal fixes the reporting. Contact the custodian and follow the return-of-excess process that applies to your situation.
What is the latest I can contribute for the 2026 tax year?
You can generally make a 2026 IRA contribution until the due date for your 2026 federal income tax return in 2027, not including extensions for purposes of making the contribution. Make sure the custodian records the deposit for the correct tax year.
Make the Roth IRA System Automatic
Maxing out a Roth IRA is not one heroic transfer. It is a repeatable system. Know your legal contribution room, choose a funding pace your cash flow can survive, make the deposits, and verify that the money is invested.
If you cannot reach the full limit this year, automate what you can. If you can max it comfortably, make the process boring enough that you do not have to renegotiate the decision every month.
Before you celebrate the number, check the two screens that matter: your year-to-date contribution total and your actual investments. Funded and invested is the finish line.
How We Verified This
These are the authorities and references used to verify the material facts in this article.
