


Yes, you can use a Roth IRA to pay for college. Regular Roth IRA contributions can generally be withdrawn at any time without federal income tax or the 10% early-distribution tax. But that does not automatically make your Roth IRA a good college account.
The part families tend to miss is what happens after the withdrawal. You can lose years of tax-free retirement growth, Roth earnings can still be taxable depending on the distribution, and a Roth withdrawal can enter the FAFSA income calculation even though the Roth IRA itself is excluded as an asset.
As a former financial planner and a father of two college-aged sons, this is one of those decisions where I would slow the conversation down. The question is not simply, “Can I get the money out?” The more useful question is: What problem am I solving with the Roth—and what am I giving up to solve it?
Quick Answer
You can use a Roth IRA for college, but college does not magically make every Roth withdrawal tax-free. Your regular contributions come out first and are generally tax- and penalty-free. If a distribution reaches taxable Roth earnings, qualified higher-education expenses can waive the 10% additional tax, but ordinary income tax may still apply unless the distribution independently qualifies as a tax-free Roth distribution.
Key Takeaways: When a Roth IRA for College Makes Sense—and When It Doesn’t
- Roth contributions are the easy part. IRS ordering rules treat regular contributions as coming out before conversions and earnings.
- The education exception is a penalty exception, not a blanket tax exemption. Qualified college expenses can eliminate the 10% additional tax on certain taxable early IRA distributions. They do not by themselves make Roth earnings tax-free.
- Your Roth balance is excluded from FAFSA assets. But taking money out can change the income used in a later FAFSA calculation.
- A 529 is usually the cleaner education account. It was designed for education, qualified withdrawals are generally federally tax-free, and recent law changes have made unused 529 money more flexible.
- The real cost is opportunity cost. Roth contribution space is limited. Once money leaves the Roth for tuition, you generally cannot simply put those old contributions back years later.
Key Takeaways Ahead
How Roth IRA Withdrawals for College Actually Work
The cleanest way to understand a Roth IRA withdrawal is to stop thinking of the account as one pile of money. The IRS applies an ordering rule to nonqualified Roth IRA distributions.
Under IRS Publication 590-B, Roth IRA money generally comes out in this order:
- Regular contributions
- Conversion and rollover contributions, generally oldest first
- Earnings
Regular Roth IRA Contributions
If you have contributed $40,000 of your own after-tax money to Roth IRAs over the years and have never withdrawn any of that contribution basis, the IRS ordering rules generally treat the first $40,000 of distributions as a return of regular contributions.
Those regular contributions generally come back out without federal income tax or the 10% additional tax. You do not need a college exception to withdraw your own Roth contributions.
Before You Tap Your Roth IRA for College, Find Your Basis
Contribution basis, conversions, and earnings can all coexist inside the same Roth IRA. Before using retirement money for tuition, reconstruct what you have actually contributed and what you have already withdrawn.
- Reconstruct your Roth contribution history.
- Separate regular contributions from conversions.
- Account for previous Roth IRA withdrawals.
- Know how much retirement money you are permanently redirecting to college.
Enter your email below and I’ll open my Roth IRA Basis Reconstruction Worksheet.
Email is required to access the worksheet. Newsletter signup is optional. Unsubscribe anytime.
What Happens If You Reach Roth IRA Earnings?
This is where the old shorthand about “the five-year rule” causes trouble.
A Roth IRA distribution is completely tax-free as a qualified distribution only when the Roth five-year requirement is met and the distribution meets one of the IRS qualifying conditions, such as being made after age 59½, because of disability, after death, or under the limited first-home rule.
Paying college tuition is not one of those Roth qualified-distribution conditions.
Instead, qualified higher-education expenses appear on a different IRS list: the exceptions to the 10% additional tax on early IRA distributions. In plain English, if you reach taxable Roth earnings before your distribution is otherwise qualified, education expenses may remove the 10% additional tax while the earnings themselves can still be included in taxable income.
Watch the Two Rules
“No 10% additional tax” and “tax-free Roth withdrawal” are not the same thing. This distinction is the part I would write in the margin before using a Roth IRA for tuition.
If the different Roth five-year clocks are giving you a headache, my Roth IRA five-year rule guide owns that deeper explanation.
Roth IRA vs. 529 Plan for College
The Roth IRA’s biggest advantage is flexibility. The 529 plan’s biggest advantage is that it was actually built for education.
| Question | Roth IRA | 529 plan |
|---|---|---|
| Primary purpose | Retirement | Education |
| FAFSA asset treatment | Retirement account value is excluded as an asset | A parent-held education savings account is generally reported as a parent asset for a dependent student |
| Using contributions/principal | Regular Roth contributions generally come out tax- and penalty-free | Basis is part of the education account and qualified withdrawals receive favorable tax treatment |
| Earnings used for qualified education | May still be taxable if the Roth distribution is not otherwise qualified; education may waive the 10% additional tax | Qualified distributions are generally federally tax-free |
| Unused money | Remains retirement money | Can often change beneficiaries; qualifying unused funds may also be eligible for a limited 529-to-Roth rollover |
| What you sacrifice by spending it | Scarce retirement contribution space and future tax-free growth | Money earmarked primarily for education uses |
The 529 has become more flexible than its old reputation suggests. Federal rules now allow certain long-held 529 accounts to make direct transfers to the beneficiary’s Roth IRA, subject to annual Roth contribution limits, a $35,000 lifetime rollover cap, account-age rules, and other requirements. My 529-to-Roth IRA rollover guide covers that separate decision.
The FAFSA Trap: Roth Assets and Roth Withdrawals Are Treated Differently
Here is the distinction worth remembering:
- The Roth IRA account balance is a retirement asset. Under the current federal FAFSA rules, retirement-plan values such as IRAs and 401(k)s are excluded from reportable assets.
- A Roth IRA distribution is different. Current FAFSA calculations use tax information that includes adjusted gross income and untaxed IRA distributions other than rollovers.
The 2026–27 Federal Student Aid Handbook specifically excludes retirement plans from FAFSA assets while stating that distributions can count as income.
Why Timing Matters
FAFSA generally works from an earlier tax year. For example, the 2026–27 FAFSA uses 2024 federal tax information. That lag means a Roth IRA distribution made during one calendar year may affect an aid year later than families intuitively expect.
This is why the blanket advice to “hide college money in a Roth because FAFSA doesn’t count retirement accounts” is incomplete. The account can be excluded as an asset while the distribution later becomes part of the income calculation.
Do Roth Withdrawals Cut Financial Aid by 50%?
Do not use that as a rule of thumb. The actual Student Aid Index calculation depends on who owns the income, household information, allowances, tax data, other income, assets, and the applicable FAFSA formula. A Roth distribution can worsen need-based aid eligibility, but there is no responsible way to tell a family that a $20,000 parental Roth withdrawal automatically costs $10,000 of financial aid.
The More Useful FAFSA Question
Do not ask, “What percentage of this Roth withdrawal will FAFSA take?” Ask: Which tax year will this distribution appear in, whose IRA is it, and will the student still file a FAFSA that uses that tax year?
If you need the broader federal-aid mechanics rather than the Roth-specific issue, use my FAFSA guide.
What I Have Seen Families Miss
In practice, the dangerous part was rarely that a family did not know a Roth IRA existed. The dangerous part was that they focused on one favorable feature—“the Roth doesn’t count as a FAFSA asset” or “I can get my contributions out”—and stopped the analysis there.
That is exactly the kind of decision where a technically true sentence can still lead you to the wrong conclusion.
When I Would Consider Using a Roth IRA for College
I would not make “never touch the Roth” an absolute rule. There are situations where using Roth contribution basis can be reasonable. But I would want the family to clear several gates first.
- Your own retirement remains comfortably funded after the withdrawal. Not “probably okay.” Run the retirement numbers without assuming you will replace the Roth money later.
- You know exactly which Roth dollars will be distributed. Regular contribution basis, conversions, and earnings do not have identical tax treatment.
- You have checked the FAFSA tax-year timing. Determine whether the distribution will enter a future FAFSA used by the student.
- You have compared the alternatives. Scholarships, current cash flow, 529 funds, federal student loans, and other dedicated education resources may protect retirement assets better.
- You are not spending Roth money merely because it feels “free.” Tax-free access does not mean zero economic cost.
Michael’s Decision Rule
Use the Roth because it is the best remaining source of money—not because it is the easiest account to raid. If taking the withdrawal solves college but creates a retirement shortfall, you have not solved the family’s financial problem. You have moved it ten or twenty years down the road.
The opportunity cost deserves its own line on the decision sheet. A hypothetical $20,000 left invested for 20 years at 7% annual growth would grow to about $77,000 before considering investment fees or taxes. That is not a forecast. It simply demonstrates what compounding makes possible—and what permanently leaves the Roth when the money is spent today.
What to Use Before Your Roth IRA for College
1. Scholarships, Grants, and Current Cash Flow
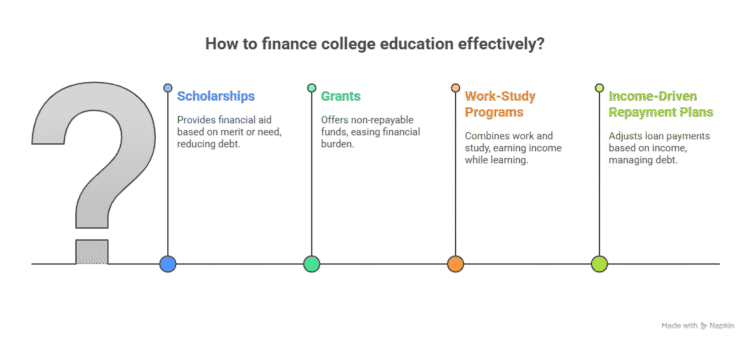
Money that does not have to be repaid or pulled from retirement deserves the first look. The family’s target also matters: paying 100% of college is a very different financial commitment from helping with tuition while the student contributes through work, aid, or borrowing.
2. 529 Plan Money Already Saved for Education
A 529 exists for this job. Under IRS rules, earnings on qualified 529 distributions are generally federally tax-free when used for qualified education expenses. For families worried about overfunding, beneficiary changes and the newer limited 529-to-Roth rollover rules have reduced some of the old inflexibility concerns.
For the general rules and common overfunding questions, see my 529 plan FAQ.
3. Federal Student Loans
Debt is not automatically better than a Roth withdrawal, but neither is a Roth withdrawal automatically better than debt. Federal student loans can preserve retirement capital and give the family time to decide later who ultimately helps repay the balance. Compare the interest cost with the retirement capital you would permanently remove.
4. A Smaller Roth Withdrawal Instead of an All-or-Nothing Choice
The decision does not have to be “Roth or no Roth.” A family may use cash flow and 529 funds, accept some federal borrowing, and use a limited amount of Roth contribution basis only for a remaining gap. That can preserve more retirement flexibility while still solving the immediate tuition problem.
Bottom Line: Protect the Roth Unless the Tradeoff Is Worth It
You absolutely can use a Roth IRA for college. Sometimes that flexibility is valuable.
But do not let “I can withdraw it” quietly become “there is no cost to withdrawing it.” Regular contributions, conversions, and earnings follow different Roth rules. The college exception concerns the 10% additional tax; it does not automatically make Roth earnings tax-free. And FAFSA can ignore the Roth balance as an asset while still counting distributions in the income calculation.
My default is therefore simple: retirement money stays retirement money until the family proves that using it for college is the better trade. College has scholarships, payment plans, lower-cost schools, work income, 529 plans, and borrowing options. Retirement gives you far fewer ways to replace twenty years of lost compounding.
