

The Social Security Disability 5-year rule usually means this: if your disability begins at age 31 or older, you generally need at least 20 Social Security work credits from the 10 years immediately before your disability began. Since you can earn up to four credits per year, people often shorten that to “worked 5 of the last 10 years.”
That shorthand is useful, but it creates two big misunderstandings. First, younger workers have different rules. Second, your work credits do not simply vanish after five years. The real issue is whether enough of your credits still fall inside the recent-work window when Social Security determines your disability insured status.
There is another reason this topic gets messy. Social Security has several completely different rules that also use a five-year period, including Expedited Reinstatement, the Trial Work Period’s rolling 60-month window, and the newer five-year past-relevant-work rule. This guide separates them so you can figure out which one actually matters to you.
Show the quick version
- Main rule: For most workers age 31 or older, SSDI's recent-work test generally requires at least 20 credits during the 40 calendar quarters before disability began. That is the source of the 5-of-10-year shorthand.
- 2026 credits: In 2026, one Social Security credit is earned for each $1,890 of covered earnings, up to four credits for the year. Four credits therefore require $7,560 of covered earnings.
- Younger workers: Workers who become disabled before age 31 can qualify under shorter recent-work rules. Workers who are statutorily blind have a different insured-status rule and do not use the same recent-work test.
- Date Last Insured: Your DLI is the last day you meet SSDI insured-status requirements. For SSDI, Social Security generally must establish that your disability began on or before that date.
- Not the same rule: EXR, the Trial Work Period's rolling 60 months, and SSA's five-year past-relevant-work lookback are separate rules. Do not use one as a substitute for another.
Jump to what you need:
- What is the SSDI 5-year rule?
- How do work credits work in 2026?
- What if I am under 31?
- What is my Date Last Insured?
- Do SSDI work credits expire?
- Which other Social Security 5-year rule am I seeing?
On This Page
- What Is the Social Security Disability 5-Year Rule?
- How Social Security Work Credits Work in 2026
- What If You Become Disabled Before Age 31?
- Date Last Insured: The Date That Makes the 5-Year Rule Real
- Do SSDI Work Credits Expire?
- Why the Disability Onset Date Matters So Much
- Four Different Social Security “5-Year Rules” People Mix Together
- The Newer 5-Year Past Relevant Work Rule Is Not a Work-Credit Rule
- How to Check Whether the 5-Year Rule May Be a Problem for You
- Social Security Disability 5-Year Rule FAQ
- My Take: Find the Date Before You Obsess Over the Rule
- How We Verified This
What Is the Social Security Disability 5-Year Rule?
For SSDI, Social Security requires you to have worked both long enough and recently enough under Social Security-covered employment. Those are related but separate tests.
For someone who becomes disabled at age 31 or older, the recent-work rule generally requires at least 20 credits during the 40 calendar quarters ending with the quarter the disability began. Forty quarters equals 10 years. Twenty credits is the maximum you can earn in five years. That is where the familiar “5 of the last 10 years” description comes from.
The Social Security Administration’s disability eligibility guidance describes the same general rule as 40 total credits, with 20 earned in the last 10 years, while noting that younger workers may qualify with fewer credits.
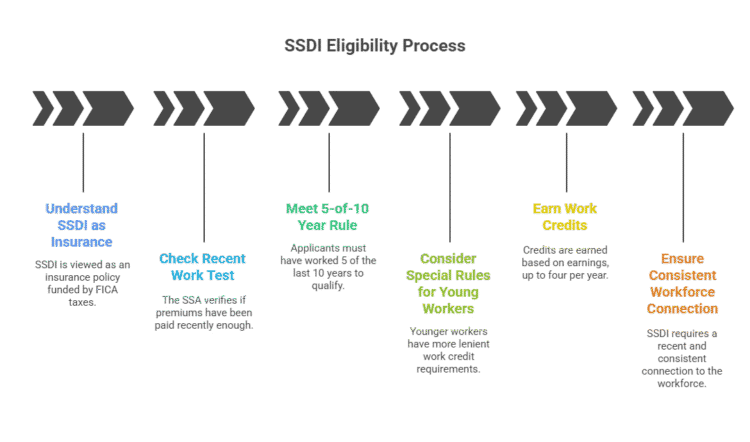
Think of SSDI as insurance tied to your work record. Years of paying Social Security taxes can build the coverage, but for most nonblind workers the program also asks whether enough of that covered work was recent when the disability began.
One mistake I saw people make around Social Security was assuming, “I worked for 25 years, so I must qualify.” A long career can satisfy the duration requirement while a long gap out of covered work can still create a recent-work problem. SSDI eligibility is not based only on lifetime credits.
How Social Security Work Credits Work in 2026
In 2026, you earn one Social Security credit for each $1,890 of covered wages or self-employment income, up to four credits for the year. Once you have $7,560 of covered earnings in 2026, you have earned all four credits available for that year.
Importantly, you do not have to earn one credit in each calendar quarter. Since 1978, credits are based on total yearly earnings. Someone who earns enough early in the year can earn all four annual credits before December.
Earning more than the minimum number of credits does not make your SSDI check larger by itself. Social Security uses your covered earnings history to calculate the benefit amount. Credits are the eligibility gate.
Recent-work test vs. duration-of-work test
The “5-year rule” is only the recent-work side of the equation. Social Security also has a duration-of-work test that asks whether you accumulated enough total work credits for your age when disability began.
That distinction matters more as you get older. A person who becomes disabled at age 50, for example, generally needs more total credits than someone who becomes disabled at age 32, even though the 20-in-40 recent-work requirement can apply to both.
What If You Become Disabled Before Age 31?
The five-of-ten shorthand does not fit younger workers very well. Social Security uses shorter recent-work tests because someone in their 20s has not had enough time to build a long earnings record.
| Age when disability begins | General recent-work rule |
|---|---|
| Before 24 | You may qualify with 6 credits earned during the 3-year period ending when your disability begins. |
| Age 24 through 30 | You generally need credits for working about half the time between age 21 and when your disability begins. |
| Age 31 or older | You generally need at least 20 credits during the 10-year period immediately before disability begins. |
Social Security also says that a worker whose disability is based on statutory blindness does not have to meet the same recent-work test. The duration-of-work requirement still matters.
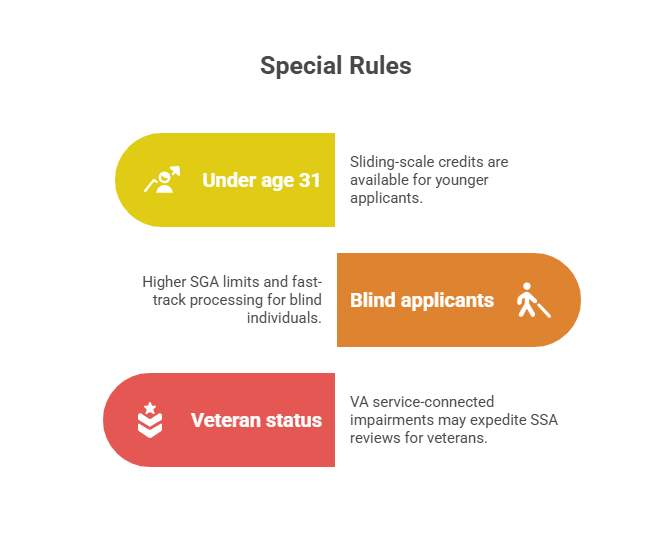
Veterans can also encounter expedited disability-claim processing in specific circumstances, but military status does not replace the SSDI work-credit rules. Keep the processing question separate from the insured-status question.
Date Last Insured: The Date That Makes the 5-Year Rule Real
Your Date Last Insured (DLI) is the last day you meet Social Security’s disability insured-status requirements. SSA’s policy defines it as the last day of the last calendar quarter in which you remain insured for disability benefits.
For an SSDI claim, Social Security generally must establish that your disability began on or before your DLI. That does not mean SSA has to approve your claim before the DLI passes. It means the evidence has to support an established onset date that is no later than your DLI.
This is exactly where a lot of reader confusion shows up. People see a DLI in the past and assume their current application is automatically dead. That is not the right question. The controlling question is whether Social Security can establish that you met its disability standard while you were still insured.
You can sometimes apply after your Date Last Insured and still qualify for SSDI if the evidence establishes disability on or before the DLI. The problem is evidentiary. The farther the relevant period is in the past, the harder it may be to prove what your functional limitations were then.
Do SSDI Work Credits Expire?
Your credits remain on your Social Security earnings record. What can expire is your disability insured status.
The recent-work test uses a moving window tied to when disability began. If you stop working in Social Security-covered employment, older credits gradually fall outside that recent-work window. Eventually you can reach a Date Last Insured even though your lifetime earnings record still shows all the credits you previously earned.
That is why “my work credits expired” is understandable shorthand but technically sloppy. Your earnings record did not get erased. The question is whether you were still insured for SSDI when your disability began.
Your work credits do not disappear. Their position in the recent-work window changes.
Why the Disability Onset Date Matters So Much
The date you put on an application is your alleged onset date. Social Security ultimately determines an established onset date from the medical and other evidence. For SSDI, that established onset date generally cannot be after your DLI.
This is not a reason to invent an earlier date. It is a reason to think carefully about when your condition actually became severe enough to meet Social Security’s disability standard and whether the medical and work evidence supports that period.
If your condition worsened gradually, there may not be one dramatic day when everything changed. Medical records, work attempts, accommodations, absences, reduced duties, treatment history and the point when you could no longer sustain work can all become important evidence. For a disputed onset date or a DLI problem, this is where qualified disability representation can be useful.
Four Different Social Security “5-Year Rules” People Mix Together
The phrase “Social Security 5-year rule” is genuinely ambiguous. Here are the four concepts most likely to show up in your search results.
Who it affects: New SSDI applicants, especially age 31 and older.
What five years means: Generally 20 credits, equal to five years of maximum credits, must fall within the 10-year recent-work window.
This page owns this rule.
Who it affects: Certain former SSDI or SSI beneficiaries whose benefits ended because of work and earnings.
What five years means: You generally must request EXR within 60 months of the month benefits ended. The current impairment must be the same as or related to the original disabling impairment, and other requirements apply.
Who it affects: Current SSDI beneficiaries testing work.
What five years means: Your nine Trial Work Period service months do not have to be consecutive. They are counted within a rolling 60-month period.
Who it affects: Disability claimants when SSA evaluates whether they can perform past relevant work.
What five years means: Since June 22, 2024, SSA generally looks at work performed during the five years before it decides the claim, rather than the old 15-year period.

For EXR, SSA says a qualifying person may be able to restart benefits without a new initial application and may receive provisional benefits for up to six months while the agency reviews the request. After an approved EXR, a new Trial Work Period does not begin immediately. SSA’s Red Book says a new TWP becomes available after the person completes a 24-month Initial Reinstatement Period of payable benefits.

For the Trial Work Period, SSA’s 2026 threshold is $1,210 in monthly earnings for an employee to count a month as a TWP service month. After the nine-month TWP, the 36-month Extended Period of Eligibility uses the separate 2026 SGA amounts of $1,690 per month for nonblind beneficiaries and $2,830 for beneficiaries receiving disability due to blindness.
The fact that several SSA rules use five years does not make them interchangeable. Work credits decide insured status. EXR is a reinstatement pathway. The Trial Work Period governs work incentives. Past relevant work is part of the medical-vocational disability decision.
The Newer 5-Year Past Relevant Work Rule Is Not a Work-Credit Rule
Beginning June 22, 2024, Social Security reduced the period it generally considers for past relevant work from 15 years to five years. That change applies during the disability evaluation when SSA asks whether you can still perform past work.
It does not replace the SSDI recent-work-credit test. You can pass the 20-in-40 insured-status test and still be denied because SSA decides you are not medically disabled. You can also have severe medical limitations but fail the SSDI insured-status test because your covered work was too far in the past.
Those are different gates. Keeping them separate makes Social Security’s letters much easier to interpret.
How to Check Whether the 5-Year Rule May Be a Problem for You
- Review your Social Security earnings record. Sign in to your my Social Security account and make sure covered earnings are not missing.
- Identify when you believe your disability became severe enough to prevent substantial work. Do not choose a date merely to fit the credits.
- Ask SSA for your Date Last Insured if it is not clear. Your DLI turns the abstract five-year rule into a concrete date.
- Compare the onset period with the DLI. If the disability may have begun before the DLI, gather evidence from that period.
- If you are under 31 or statutorily blind, do not use the standard five-of-ten shortcut. Your insured-status rule may be different.
If your SSA earnings record is incomplete, the recent-work calculation can be wrong. Compare your record with W-2s, tax returns or self-employment records and follow SSA’s process for correcting an earnings record before assuming your insured status is final.
Social Security Disability 5-Year Rule FAQ
Is the SSDI 5-year rule a deadline to apply?
No. For most workers age 31 or older, it is shorthand for the recent-work requirement that generally calls for 20 credits in the 10 years before disability began. Your Date Last Insured is important because SSA generally must establish disability on or before that date, but an application can sometimes be filed after the DLI.
How many SSDI work credits do I need in 2026?
The answer depends on your age when disability begins. For most people age 31 or older, the recent-work test generally requires 20 credits in the prior 10 years, while the duration-of-work test can require additional lifetime credits. Younger workers can qualify with fewer recent credits.
How much do I have to earn for one work credit in 2026?
In 2026, one credit requires $1,890 in covered earnings. You can earn no more than four credits for the year, so $7,560 of covered earnings earns all four 2026 credits.
If my Date Last Insured passed while my claim is pending, do I automatically lose?
No. The key issue is whether SSA can establish that your disability began on or before your DLI. It is common for a DLI to pass while an application or appeal is still being decided. The evidence for the insured period is what matters.
Can going back to work give me SSDI insured status again?
Covered work can add new credits and can change insured status, but the exact result depends on your age, existing credit history and when disability begins. Do not assume a short job automatically restores SSDI eligibility. Check the updated earnings record and DLI with SSA.
Does the 5-year recent-work rule apply to SSI?
No. Supplemental Security Income is a needs-based disability program and does not require an SSDI work-credit record. SSI has its own income, resource and disability rules. Expedited Reinstatement, however, can apply in a different form to some former SSI recipients whose payments ended because of earned income.
My Take: Find the Date Before You Obsess Over the Rule
Social Security’s wording makes this sound like a credits problem. In practice, the useful sequence is more concrete.
Check your earnings record. Find your Date Last Insured. Identify when the disability actually became work-preventing. Then ask whether the evidence connects those dates.
That is far more useful than simply counting back five years from today. The five-year rule looks backward from the relevant disability period, not from whatever date you happen to be reading this article.
How We Verified This
These are the authorities and references used to verify the material facts in this article.
