
Ready to take charge of your financial future but not sure where to start?

If you’re trying to get control of your money but aren’t sure where to start, short-term financial goals are the place to begin.
Here’s something powerful: breaking your big financial aspirations into smaller, actionable steps makes your objectives not only achievable but empowering.
This guide covers what short-term financial goals actually are, real examples, and the strategies that help people stick with them.
Short-term financial goals refer to objectives you’re aiming to hit within one to three years — things like tackling debt, setting a budget, starting an emergency fund, or saving for a near-term expense like a down payment on a home or a car.
Drawing on years of working with clients on exactly this, here’s how to set short-term goals that actually hold up, plus realistic examples you can adapt to your own numbers.
On This Page
- Key Takeaways Ahead
- What Are Short-Term Financial Goals?
- Why Are Short-Term Financial Goals Important?
- Examples of Shorter Term Financial Goals
- How to Set and Achieve Your Immediate Financial Goals
- Challenges You Might Face
- Balancing Short-Term and Long-Term Financial Goals
- Measuring Success: Are You on Track?
- Key Takeaways: Building Momentum with Short-Term Goals
Key Takeaways Ahead
What Are Short-Term Financial Goals?
Short-term financial goals are milestones you’re aiming to hit within one to three years. Think of them as stepping stones toward bigger goals like retirement or owning a business.
Short-term goals differ from long-term objectives because they prioritize immediate needs and manageable wins, like paying off a credit card, saving for a vacation, or building an emergency fund.
Success in these areas lays the foundation for greater financial security down the line.
Common Short-Term Goals

Emergency Fund
Building an emergency fund covering 3-6 months of living expenses is a fundamental short-term objective. It provides a financial cushion and helps you avoid high-interest debt when unexpected expenses come up, according to SoFi’s guide to short-term financial goals.
Debt Management
Paying off credit card debt is a priority for many people — the average credit card APR has stayed above 20% through late 2025, according to Federal Reserve data.
Some other common short-term savings goals typically include:
- Vacation funds
- Wedding savings
- Car down payments
- Home renovation funds
Example of Goal Setting
Consider this practical example: to save $9,000 for an emergency fund within 12 months, you’d need to set aside $750 a month through automatic transfers — an approach Citizens Bank also recommends for short-term saving.
This systematic approach removes the temptation to spend and ensures steady progress toward your goal.
Why Are Short-Term Financial Goals Important?
Imagine standing at the base of a mountain. You can see the peak—your long-term dreams—but reaching it feels impossible. Short-term goals are like the steps carved into the rock, guiding you upward one achievable step at a time.
Money is consistently one of the top sources of stress for Americans — the APA’s Stress in America survey has found roughly two out of three adults name finances as a significant stressor in recent years. Tackling small goals can reduce that anxiety, build confidence, and create momentum for the bigger challenges.
You’re not alone in finding this hard — it’s one of the most common struggles I saw in nearly three decades as a financial planner. The good news: a few well-chosen, concrete goals can make it manageable.
Short-Term Impact:
• Credit utilization reduction
• Emergency preparedness
• Stress reduction
Long-Term Benefits:
• Improved borrowing rates
• Investment opportunities
• Wealth building foundation
Financial Goal Prioritization Strategy
High-Priority Goals:
✓ High-interest debt elimination (20%+ APR credit cards)
✓ Emergency fund establishment (3-6 months expenses)
✓ Employer 401(k) match capture (100% ROI)

Medium-Priority Goals:
✓ Short-term savings objectives (vacation, wedding)
✓ Credit score improvement
Low-Priority Goals:
✓ Luxury purchases
✓ Optional upgrades
Current Financial Challenges
The CFPB’s Emergency Savings and Financial Security report found emergency savings vary widely: 24% of consumers have no savings set aside for emergencies, 39% have some savings but less than a month’s income saved, and 37% have at least a month of income in reserve. Separately, the same research found:
- 16% of consumers say their typical monthly spending exceeds their income
Ask Yourself:
- What’s one financial win you’d like to achieve this month?
- How would your stress levels change if you had an emergency fund covering three months of expenses?
Examples of Shorter Term Financial Goals
Setting and achieving personal monetary objectives is an important part of successful financial planning. To reach a desired level of financial security, it helps to have short-term objectives that get you there.
For Individuals
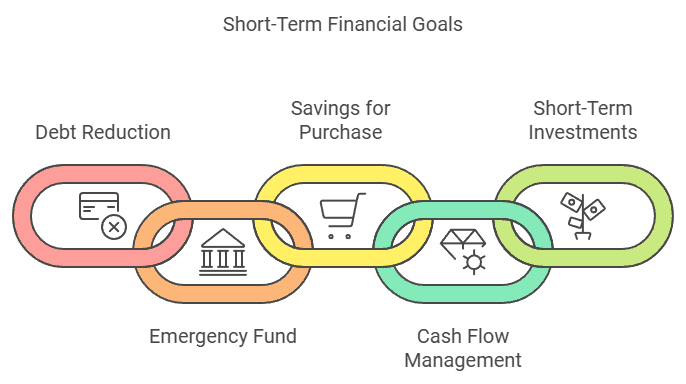
- Debt Reduction: Pay off a high-interest credit card within six months. Use methods like the snowball (starting with smaller debts) or avalanche (prioritizing higher-interest debts) approaches.
- Emergency Fund Creation: Save $1,000 in three months for unexpected expenses like car repairs or medical bills.
- Savings for a Purchase: Set aside $2,000 for a new laptop or furniture upgrade.
For Businesses
- Cash Flow Management: Increase working capital by reducing unnecessary expenses over a quarter.
- Short-Term Investments: Allocate funds for a marketing campaign with a projected ROI within 90 days.
- Team Development: Budget for employee training programs to improve productivity within six months.
What This Looks Like in Practice
A few patterns show up again and again in the goal-setting work I’ve done with clients over the years:
Utilization-driven credit repair. The biggest lever most people have on their credit score isn’t paying off every dollar of debt — it’s getting credit utilization under 30%. That single change, sustained over a year or more, tends to move scores more than almost anything else.
Small, consistent investing. You don’t need thousands of dollars to start. A modest, automated weekly contribution that increases gradually over time compounds into a meaningful balance — the amount matters less than the consistency.
Redirecting side income. People who turn a hobby into modest side income, and then automatically route that money toward a specific goal instead of everyday spending, tend to make faster progress than people relying on their main paycheck alone.
The common thread: none of these require starting with a lot of money. They require starting with what you have and staying consistent.
How to Set and Achieve Your Immediate Financial Goals

- Get Crystal Clear on Your Priorities
Begin by asking yourself, What’s the most pressing issue I need to address? Write down your goals and rank them by urgency.
For instance:
* Emergency fund
* Debt repayment
* Saving for a holiday
Remember, the more specific your goals, the better. Instead of saying, “Save money,” try, “Save $500 in three months by cutting dining-out expenses.”
- 23 Money Savings Challenge To Try
- How To Save $10000 In 3 Months
- Develop a Short-Term Financial Plan
A strong financial plan ensures you stay on track. Here’s an example of a short-term financial plan:
| Goal | Time Frame | Action Steps | Resources Needed |
|---|---|---|---|
| Emergency Fund | 3 months | Save $200/month Cancel unused subscriptions | High-interest savings account |
| Pay Off Credit Card | 6 months | Pay $300/month Focus on highest interest debt | Debt snowball calculator |
- Break Down Goals into Actionable Steps
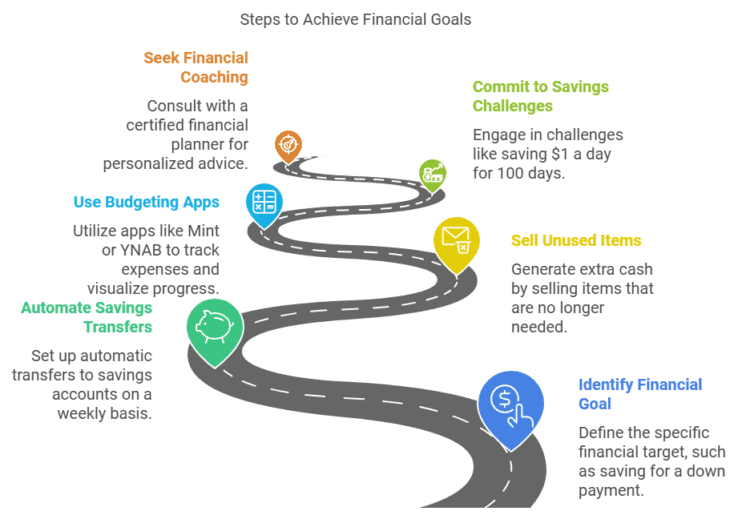
If your goal is saving for a down payment, actionable steps might include:- Automating savings transfers weekly.
- Selling unused items for extra cash.
- Using a budgeting app to track spending.
- Utilize Smart Tools and Resources
- Budgeting Apps: Try apps like Mint or YNAB to track expenses and visualize progress. Read my reviews on The Most Popular Budgeting Apps for more.
- Savings Challenges: Commit to a money-saving challenge, such as saving $1 a day for 100 days.
- Financial Coaching: Seek advice from a certified financial planner for a personalized approach.
SMART Goal Framework
To effectively achieve short-term financial targets, implement the SMART framework:
| Component | Description |
|---|---|
| Specific | Define exact amounts and purposes |
| Measurable | Set concrete dollar amounts |
| Achievable | Align with financial capacity |
| Relevant | Match your priorities |
| Time-bound | Establish clear deadlines |
Once you’ve set SMART goals, the next step is choosing where to actually put the money.
Recommended Savings Vehicles
| Account Type | Best For | Features |
|---|---|---|
| High-yield Savings | Most short-term goals | Earns interest, highly liquid |
| Money Market | Emergency funds | Higher interest rates than traditional savings |
| Certificate of Deposit | Fixed-term savings | Guaranteed returns |
| Brokerage Account | Growth potential | Higher risk, more flexibility |
Challenges You Might Face
Even with the best intentions, life can throw curveballs. Here are common obstacles I’ve seen clients face, and how to work around them:
- Unexpected Expenses: Build flexibility into your plan by allocating 10% of your budget for “miscellaneous.”
- Loss of Motivation: This one is vital to your success. Celebrate small wins to stay engaged, like treating yourself to a favorite meal after reaching a mini-milestone.
- Economic Fluctuations: Adjust your strategy to align with changing circumstances, such as inflation or job changes.
Common Financial Obstacles & Solutions
Common Barriers:
• Instant gratification bias
• Loss aversion
• Analysis paralysis
Recommended reading: “Atomic Habits” by James Clear
Obstacle → Solution
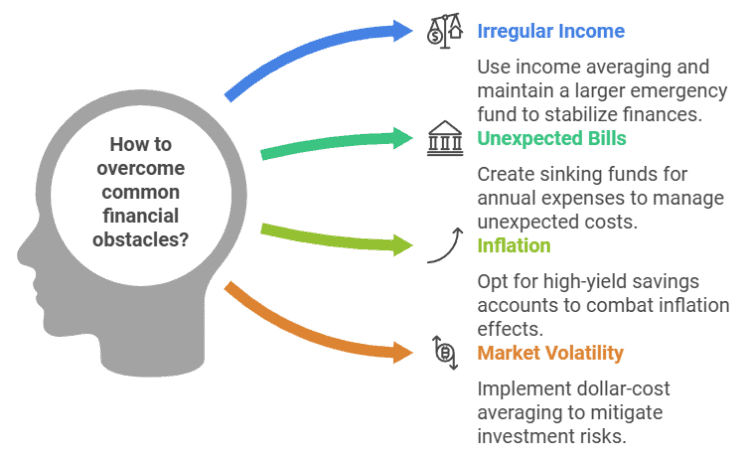
• Irregular Income → Income averaging + larger emergency fund
• Unexpected Bills → Sinking funds for annual expenses
• Inflation (was 8.5% in 2022) → High-yield savings accounts
• Market Volatility → Dollar-cost averaging
• Lifestyle Creep → 50/30/20 budgeting rule
Balancing Short-Term and Long-Term Financial Goals
Something I emphasized often with clients: every day, you’re financially living three lives.
- Yesterday: You live the financial decisions you have made in the past.
- Today: Many people forget to live this life. Start enjoying today.
- Tomorrow: Save, save, save.
For more on this balance, see the CFPB’s guide on saving for short- and long-term goals.
But how do you strike a balance?
The key is integration. For example:
- If you’re saving for a home down payment (short-term), also contribute a small percentage to your 401(k) (long-term).
- Use debt repayment momentum to fuel longer-term investments in mutual funds or a Roth IRA.
- Don’t stop! When you pay off a debt, roll those payments into your next debt or future savings — it has a snowball effect.
This university explainer on balancing long- and short-term financial planning covers the tradeoffs in more depth.
Thought Experiment:
If you could fast-forward five years, what small financial habit today would make the biggest difference?
Measuring Success: Are You on Track?
Regularly evaluate your progress. Create checkpoints monthly or quarterly to ensure you’re aligned with your objectives. For instance:
- Did you save the planned amount last month?
- Are you making consistent debt repayments?
Quick Tip: Use visual tools like bar charts to track savings growth. Seeing progress can be incredibly motivating!
Financial Progress Tracking Methods

Daily:
• Expense logging
• Budget checking
Weekly:
• Account reconciliation
• Progress visualization
Monthly:
• Goal milestone review
• Budget adjustment
Quarterly:
• Major goal evaluation
• Strategy refinement
Psychological Techniques:
• Visual progress tracking (charts/graphs)
• Money journaling
• Accountability partnerships
• Reward milestones
Key Takeaways: Building Momentum with Short-Term Goals
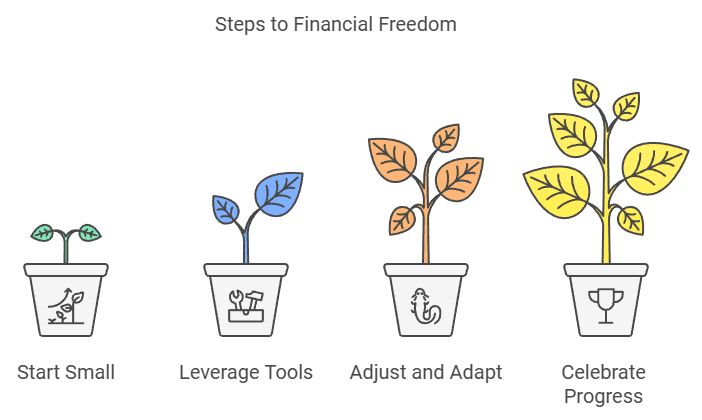
Based on what I’ve seen work — and not work — here are my top tips:
- Start Small: Focus on manageable objectives, like saving $100 this month.
- Leverage Tools: Automate your savings or use a debt tracker.
- Adjust and Adapt: Stay flexible; financial plans often need tweaking.
- Celebrate Progress: Recognize your achievements, no matter how small.
Taking control of your finances begins with one action. Whether it’s downloading a budgeting app, scheduling a consultation with a financial advisor, or making your first debt repayment, each step moves you closer to financial freedom.
Final Aha Moment:
Your financial journey is uniquely yours. But the strategies to succeed—goal setting, discipline, and actionable planning—are universal. What’s the first short-term goal you’ll tackle today?
