

If you’re trying to figure out how to avoid paying capital gains tax on inherited property, don’t start with tax tricks. Start with the gain. In many inheritances, the step-up in basis has already erased most of the appreciation that happened during the previous owner’s lifetime.
That means the smartest strategy may be much simpler than a trust, exchange, or complicated tax maneuver: establish the correct inherited basis, measure the appreciation that happened after the death, then choose a strategy that actually fits what you’re doing with the property.
Quick Answer
You can legally reduce or sometimes eliminate capital gains tax on inherited property by using the stepped-up basis correctly, selling before much post-death appreciation occurs, qualifying for the Section 121 home-sale exclusion, offsetting gains with capital losses, using a 1031 exchange for qualifying investment property, structuring an eligible installment sale, or donating property when charitable giving is genuinely the goal. The right move depends on the property’s basis, how you use it, your other income and gains, and whether you actually need the sale proceeds. First calculate the real gain; then choose the tax strategy.
After nearly three decades in financial planning, that’s the sequence I would use with almost any inherited-property decision. The tax code has plenty of levers. Pulling one before you know the size and source of the gain is how a simple situation becomes an expensive project.
Start Here: What Did You Inherit, and What Are You Considering?
If you’re not sure which tax rules matter yet, use the inherited-asset strategy finder below. It helps you sort the first questions by what you inherited, what you plan to do with it, and whether the basis documentation is already in place.
Inherited Asset Tax & Decision Pathfinder
Identify the valuation, basis, income-tax, ownership and administration questions to answer before selling, holding, distributing or retitling inherited property.
Your Inherited-Asset Review Checklist
Likely federal tax character
Basis and valuation questions
Questions before taking action
Records to collect
Professional review
Do not assume this result establishes your basis or tax
How the result was produced
This tool does not calculate tax, establish basis, determine legal ownership, interpret a will or trust, or recommend whether to sell, hold, donate, distribute or retitle property.
Property acquired from a decedent often receives a basis related to fair market value at death, but alternate valuation elections, estate-tax consistency rules, community-property treatment, joint ownership, prior gifts, income in respect of a decedent and other exceptions may apply.
Traditional retirement accounts, annuities and other income-in-respect-of-a-decedent assets generally require different analysis from ordinary capital assets. Life-insurance proceeds, businesses, collectibles and depreciated property can also raise specialized issues.
State and foreign rules may affect inheritance tax, estate tax, income tax, property tax, transfer tax, probate and filing obligations.
This tool provides general education, not individualized tax, legal, accounting, appraisal, estate-planning, investment or financial advice. Michael Ryan is a retired financial planner and financial educator, not a practicing attorney, CPA, appraiser or investment adviser.
Quick Links: How to Reduce Capital Gains Tax on Inherited Property
Why Capital Gains Tax on Inherited Property Is Usually a Basis Question First
For federal tax purposes, the basis of inherited property is generally its fair market value on the date of death. IRS Publication 551 explains the inherited-property basis rules and the limited circumstances in which another estate-tax valuation may control.
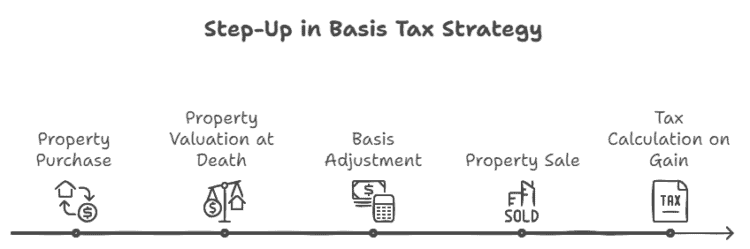
Suppose your father bought a house for $150,000. It was worth $500,000 when he died, and you later sold it for $515,000. Under the general step-up rule, you don’t start the gain calculation at his $150,000 purchase price. You generally start around the inherited $500,000 basis, adjusted for any later basis changes and sale-related items that apply.
That’s the first big reframe: you are usually planning around post-death appreciation, not a lifetime of appreciation that belonged to the person who died.
First, Calculate Whether There Is Much Gain to Avoid
A gain-only capital-gains tax calculator can give you false confidence because the federal long-term rate depends on your taxable income, not just the size of this one gain. An inherited property can also involve state tax, the 3.8% Net Investment Income Tax, depreciation issues, or a home-sale exclusion.
The useful first calculation is the one you can trust without pretending to know the entire tax return:
Estimated gain = sale proceeds − selling costs − adjusted inherited basis
| Item | Amount |
|---|---|
| Sale proceeds | $515,000 |
| Selling costs | − $30,000 |
| Adjusted inherited basis | − $500,000 |
| Estimated result | $15,000 loss before other adjustments |
That example is intentionally simple. Improvements, depreciation, ownership percentages and other adjustments can change the final number. And as the IRS explains for personal-use property losses, a loss generally isn’t deductible just because the arithmetic is negative.
If you need the mechanics of the gain calculation or Form 1099-S reporting, use my companion guide to capital gains tax on inherited property and Form 1099-S. That page owns the calculation-and-reporting job; this one owns the strategy decision.
Selling Costs Reduce the Gain — They Aren’t a Separate Loophole
Real-estate commissions and certain other selling expenses can affect the amount of gain you report. Keep the closing statement and supporting records. I would treat this as getting the gain right, not as a stand-alone tax strategy.
Michael’s First Question
Before asking, “How do I avoid the tax?” ask, “What is the gain after the step-up and selling costs?” If that answer is small, don’t build a complicated strategy to solve a tax bill that barely exists.
6 Legal Strategies to Reduce Capital Gains Tax on Inherited Property
Once you know there is a real taxable gain, the property’s job determines which strategies are actually available. A house you’re selling next month, a home you’re moving into, and a rental you’re keeping as an investment are three different tax problems.
| Your plan | Strategy to examine | Main catch |
|---|---|---|
| Sell now | Sell before much post-death appreciation builds | Selling sooner does not guarantee zero gain |
| Move in | Section 121 home-sale exclusion | You must satisfy ownership and use rules |
| Realize other investment losses | Capital-loss netting | Do not create a bad investment decision just for a tax loss |
| Keep as investment | 1031 exchange later | Property must qualify as investment/business real estate |
| Sell and receive payments over time | Installment sale | Interest and special rules apply; it defers recognition rather than erasing gain |
| Give it away | Charitable contribution | You give up the property/proceeds and substantiation rules can be significant |
1. Sell Soon If Selling Was Already the Plan
If the inherited property was worth $500,000 at death and sells soon afterward for roughly the same net amount, there may be little post-death gain to tax. That’s why “sell soon” shows up so often in inherited-property tax advice.
But timing is not magic. The sale price can rise, the basis can be disputed, and selling costs or later improvements can change the calculation. Sell quickly because it fits the family’s plan—not because a calendar date guarantees a tax-free result.
2. Use the Section 121 Home-Sale Exclusion If You Truly Qualify
If you actually make the inherited home your main home, IRS home-sale guidance says the Section 121 exclusion generally requires you to have owned the home for at least two years and used it as your main home for at least two years during the five-year period ending on the sale date. When the requirements are met, up to $250,000 of gain may be excluded, or up to $500,000 on many joint returns.
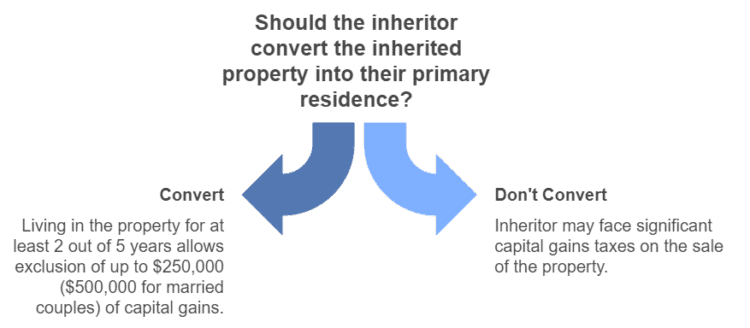
That sounds simple until siblings are involved. If one heir lived in Mom’s house for years before inheriting it, that does not automatically mean the heir satisfied the ownership test during those same years. Ownership and use are separate requirements.
For the deeper eligibility rules, rental-use complications and exclusions, see my guide to capital gains tax on a home sale.
3. Offset Capital Gains With Capital Losses
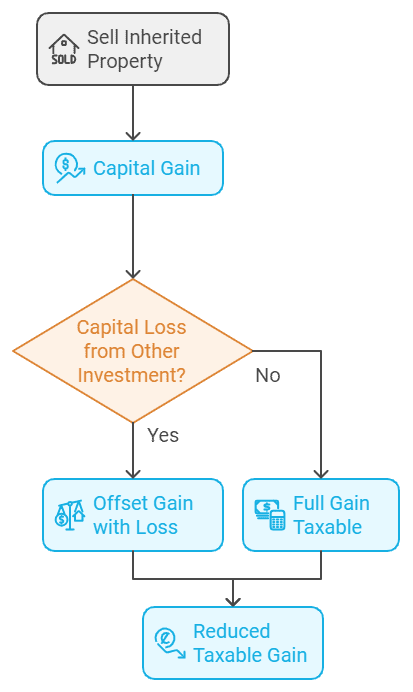
IRS Publication 550 explains how capital gains and losses are netted. If selling inherited property creates a real capital gain, reviewing the rest of your taxable portfolio before year-end can be worthwhile.
What I would not do is manufacture a bad investment decision solely to create a tax loss. A $1 tax deduction is not worth losing $1 just to get it.
4. Use a 1031 Exchange Only for Qualifying Investment or Business Property
A Section 1031 exchange can defer gain when qualifying real property held for investment or business use is exchanged for qualifying replacement real property. IRS Form 8824 instructions make the boundary clear: Section 1031 does not apply when the relinquished property was used solely as your personal residence at the time of the exchange.
This is where “I inherited a house” is not enough information. If the property was your personal-use family home after inheritance, you cannot turn it into a 1031 exchange merely by wanting the tax result. If it was genuinely held for investment and the transaction qualifies, the exchange may defer recognition of gain.
The timing and replacement-property rules are strict, so use my full 1031 exchange guide before treating this as your plan.

What Renting the Property Does — and Does Not — Do
Renting an inherited property does not itself defer the capital gain. It delays the sale because you are choosing not to sell yet. While you rent it, depreciation rules can apply, and depreciation can create additional tax consequences when the property is later sold.
Rent because the property works as an investment after expenses, management, concentration risk and your own goals—not because “rent it” sounds like a free tax strategy. If you later hold it for qualifying investment use, a 1031 exchange may become relevant, but that is a separate rule with separate requirements.
5. Consider an Installment Sale When the Buyer Will Pay Over Time
If you finance the buyer and receive at least one payment after the year of sale, an eligible installment sale can spread recognition of part of the gain across the years you receive payments. IRS Publication 537 explains that each payment can include interest, return of basis and taxable gain.
This is a deferral and cash-flow strategy, not an erase-the-gain strategy. Interest is generally taxable as ordinary income, special rules apply to some property and related-party transactions, and the buyer’s credit risk becomes part of your financial life. If you need all the cash at closing, the tax benefit may not compensate for becoming the bank.
6. Donate the Property When Giving It Away Is Actually the Goal
If you donate appreciated property directly to a qualified charity rather than selling it yourself, you generally are not personally recognizing a capital gain from your own sale because you did not sell the property. But that does not mean “donate it and deduct the full market value” is automatically correct.
IRS Publication 526 explains that charitable deductions for property can depend on the property, how long it was held, the recipient organization, percentage-of-income limits and substantiation. Noncash gifts can also trigger appraisal and Form 8283 requirements. Treat this as a charitable-planning decision first and a tax consequence second.
The Strategy Filter
Don’t ask which tactic saves the most tax in a vacuum. Ask what you want the property to do: sell it, live in it, hold it as an investment, finance the buyer, or give it away. The tax strategy should follow the economic decision—not replace it.
That distinction is worth keeping. It prevents a classic planning mistake: letting a tax benefit turn into the reason you keep a property you don’t want, become a landlord you never wanted to be, or make a charitable gift you cannot afford.
Keep the Inheritance Tax Plan Practical
Once you know the post-death gain and the property’s real job, the next decision usually gets much simpler.
- Know when stepped-up basis has already done most of the work.
- Separate true tax deferral from simply postponing a sale.
- Match Section 121, 1031, installment-sale and charitable rules to the facts that actually qualify.
Get inherited-property, capital-gains and next-money-move guidance from Michael Ryan Money.
Planning Ahead: A Lifetime Gift Can Give Up the Step-Up
A lifetime gift is a pre-death estate-planning decision for the current owner, not a post-inheritance tax strategy for the heir. And for appreciated property, gifting during life can create the opposite basis result from inheriting it at death.
IRS basis guidance generally gives gifted property a carryover-basis framework, while inherited property generally receives a date-of-death fair-market-value basis. In 2026, the annual gift-tax exclusion is $19,000 per recipient and the federal basic exclusion amount is $15 million, but those gift-tax limits do not magically create a stepped-up basis for a lifetime gift.
There are legitimate estate-planning reasons to make lifetime gifts. “It avoids capital gains tax for the recipient” is not a safe blanket reason. For many appreciated assets, gifting during life can hand the recipient a much lower basis than inheriting the same asset later.
2026 Long-Term Capital Gains Rates: Why Gain Alone Doesn’t Tell You the Tax
Inherited capital property is generally treated as long-term regardless of how long you personally held it. For 2026, IRS Revenue Procedure 2025-32 sets the following maximum taxable-income amounts for the 0% and 15% long-term capital-gains rate bands:
| Filing status | 0% rate applies through | 15% rate applies through | 20% above |
|---|---|---|---|
| Single / all other individuals | $49,450 | $545,500 | $545,500 |
| Married filing jointly / surviving spouse | $98,900 | $613,700 | $613,700 |
| Head of household | $66,200 | $579,600 | $579,600 |
Here’s the part a simple gain-only tax calculator misses: those thresholds apply to taxable income, not just to the inherited-property gain in isolation. A $100,000 gain can land differently for someone with little other taxable income than for someone whose other income already fills the lower capital-gain bands.
Some higher-income taxpayers may also owe the 3.8% Net Investment Income Tax, and state capital-gains taxes vary. That’s why I would estimate the gain here and calculate the actual tax only with the rest of the return in view.
Before You Choose a Strategy, Check These Six Facts

- What is the documented date-of-death value? If the basis is wrong, every later strategy calculation starts wrong.
- Who owns what percentage? With siblings or other co-heirs, proceeds, basis and selling costs generally need to follow the actual ownership interests.
- How has the property been used since inheritance? Personal residence, rental and investment use can lead to very different Section 121, depreciation and 1031 consequences.
- What other income, gains and losses do you have? The capital-gain rate bands and NIIT can change with the rest of your tax picture.
- What changed after you inherited it? Capital improvements can increase adjusted basis, while depreciation and other adjustments can reduce it. Those post-inheritance changes can materially alter the gain you are actually planning around.
- Which state taxes the transaction? Federal basis rules do not mean every state produces the same after-tax result. Check my state capital gains tax guide for the state-level layer.
Michael’s Decision Rules for an Inherited Property
This is where I would stop looking for a universal “best strategy.” The right move changes with the size of the gain, what you want from the property, how much liquidity you need, and whether the records are clean enough to support the tax position.
- If the gain is tiny: don’t over-engineer the answer. A simple sale may beat months of complexity.
- If you genuinely want the home: evaluate Section 121 because you want to live there, not because a tax exclusion talked you into a house.
- If it is a real investment: compare keeping/renting, selling, and a qualifying 1031 exchange on their investment merits after tax.
- If you need liquidity: a tax-deferral strategy that locks up proceeds may solve the wrong problem.
- If the records are messy: spend the first professional dollar on basis, ownership and transaction documentation before hunting for an advanced strategy.
A Common Sibling Problem
Three siblings inherit a house equally. One wants cash now, one wants to rent it, and one wants to move in. There isn’t one “best tax strategy” for the house because there isn’t one shared financial goal anymore. Before anyone starts talking about a 1031 exchange or the home-sale exclusion, the family needs to settle ownership, timing and who is actually doing what with the property.
How to Keep More of an Inherited Property Without Letting Tax Drive the Whole Decision
The best way to avoid unnecessary capital gains tax on inherited property is usually not to start with “avoid tax.” Start with four numbers and one decision: the inherited basis, sale value, selling costs, ownership share—and what you actually want the property to do.
Once those are clear, the strategy list gets shorter fast. Sell soon if selling already makes sense. Use Section 121 if it truly becomes your home and you qualify. Use 1031 only for real investment property. Use losses, installment treatment or charitable giving only when they fit the rest of your financial plan.
Good tax planning should make a good financial decision cheaper. It should not turn a bad financial decision into a tax strategy.
Frequently Asked Questions
Do I Have To Pay Capital Gains Tax On Inherited Property?
Not simply because you inherited it. Federal capital gain generally becomes relevant when you sell and the net sale amount exceeds your adjusted inherited basis. Because inherited basis is generally tied to fair market value at the date of death, a sale near that value may produce little or no gain.
What Is the Stepped-Up Basis and How Does It Work?
Inherited property generally receives a basis tied to fair market value on the date of death, subject to exceptions. That means pre-death appreciation is generally not part of the heir’s later capital-gain calculation. You then adjust that inherited basis for later items that apply before calculating the sale gain or loss.
Can I Avoid Capital Gains Tax by Living in the Inherited Property?
Possibly. Section 121 can exclude up to $250,000 of gain, or up to $500,000 for many joint filers, when the ownership, use and other eligibility rules are met. Generally you must own and use the home as your main home for at least two years during the five-year period ending on the sale date.
Can I Use a 1031 Exchange for Inherited Property?
Only when the real property is held for qualifying investment or business use and the exchange meets Section 1031 requirements. A home used solely as your personal residence does not qualify for Section 1031 merely because you inherited it.
How Do Multiple Heirs Handle Capital Gains on Inherited Property?
Each heir generally reports the proceeds, basis and selling costs allocable to that heir’s actual ownership interest. The deed, estate records and closing documents should support the ownership percentages rather than relying on an informal split after the sale.
Sources
- IRS Publication 551 — Basis of Assets
- IRS — Sale of Residence: Ownership and Use Tests
- IRS — Instructions for Form 8824, Like-Kind Exchanges
- IRS Publication 537 — Installment Sales
- IRS Revenue Procedure 2025-32 — 2026 Inflation Adjustments
- IRS — Net Investment Income Tax
- IRS — Frequently Asked Questions on Gift Taxes
- IRS Publication 526 — Charitable Contributions
- IRS Publication 550 — Investment Income and Expenses
- IRS — Losses on Homes, Stocks and Other Property
