

Are financial advisor fees tax deductible in 2026? For most individual investors, no. Personal investment-advisory and financial-planning fees are not deductible on your federal Form 1040 under current law.
But the word advisor on an invoice does not settle the tax treatment. A fee tied directly to operating a business, a special cost created only because assets sit in a trust or estate, and investment interest are different tax categories with different rules.
I have had versions of this conversation with clients more than once. A client I’ll call Amanda expected her annual advisory fee to be deductible and went looking for the place to enter it in her tax software. Her instinct was understandable: if you pay a professional to help manage money that produces taxable income, it feels like the fee should reduce that taxable income. Federal tax law does not currently work that way for most individual investors.
Quick Answer
For an individual investor, ordinary financial-planning and investment-advisory fees are generally not deductible on the federal individual income tax return in 2026. The One Big Beautiful Bill Act removed the old 2026 sunset from Internal Revenue Code Section 67(g), so the suspension of miscellaneous itemized deductions subject to the 2% floor continues under current law. Business-related professional fees may qualify when they are ordinary, necessary, and directly related to operating the business. Trust and estate fees require a separate analysis, and ordinary investment advice is not automatically deductible there either.
Key Takeaways Ahead
Why Financial Advisor Fees Are Not Tax Deductible for Most Individuals in 2026
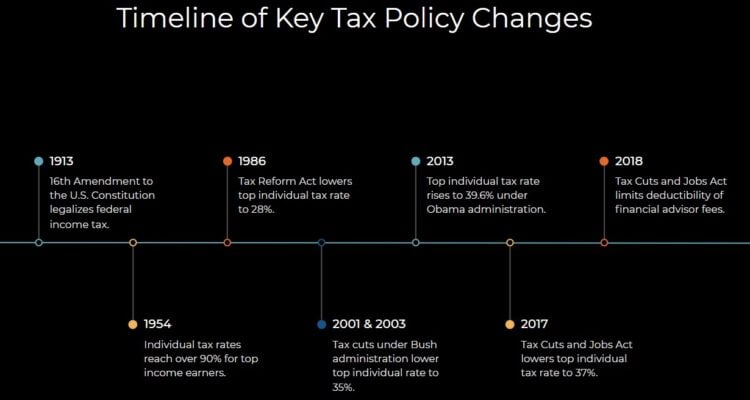
Before 2018, some investment-advisory and tax-related expenses could be claimed as miscellaneous itemized deductions to the extent the total exceeded 2% of adjusted gross income. The Tax Cuts and Jobs Act suspended those deductions for tax years 2018 through 2025.
That rule was originally scheduled to expire after 2025. It did not. Section 70110 of Public Law 119-21, enacted July 4, 2025, removed the January 1, 2026 end date from Section 67(g). Under current federal law, the old miscellaneous itemized deduction for ordinary personal investment-advisory fees does not return in 2026.
Watch the Word “Permanent”
You will see this change described as permanent. In tax-law shorthand, that means the statute no longer contains the old automatic sunset. It does not mean a future Congress is incapable of changing the law again. For a 2026 federal return, though, the personal deduction has not come back.
The Fee Classification Test: What Did You Actually Pay For?
This is the mental model I would use before trying to force an advisor invoice onto a tax return:
The tax return does not care that the invoice says “financial advisor.” It cares what the fee was actually for.
| What the fee was for | 2026 federal treatment | What to check |
|---|---|---|
| Personal financial planning or investment management | Generally not deductible on Form 1040 | Whether the fee is a personal miscellaneous investment expense |
| Professional services directly related to operating a sole-proprietor business | May be deductible to the extent ordinary, necessary, and business-related | Separate business work from personal planning |
| Investment advice for a trust or estate | Ordinary investment advice is generally not deductible; qualifying incremental trust/estate-specific costs may be | Whether the charge exists only because the property is held in the trust/estate; bundled fees may need allocation |
| Separately billed IRA trustee administrative fee paid personally | Not deductible as a miscellaneous itemized deduction | Do not confuse account-level fee payment with a personal income-tax deduction |
| Interest on money borrowed for taxable investments | Potentially deductible under separate investment-interest rules | Form 4952 and the net-investment-income limitation |
A robo-advisor does not get a different personal deduction merely because the portfolio management is automated. If the charge is an ordinary personal investment-management fee, it falls on the same side of the line as a traditional advisory fee.
Business Owners: Only the Business-Related Portion May Be Deductible
Owning a business is not a magic switch that makes your personal wealth-management fee deductible.
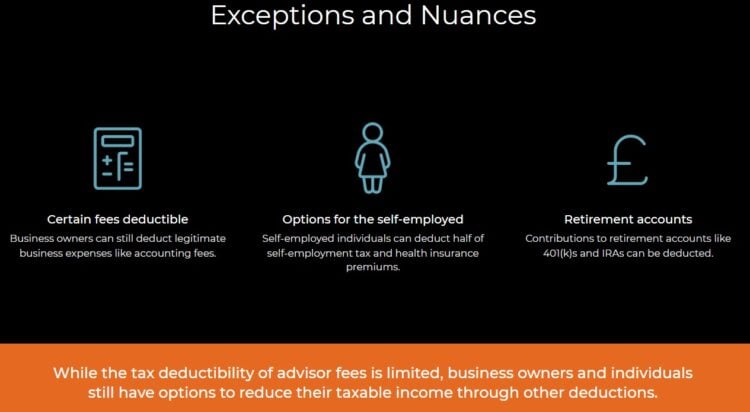
The IRS Tax Guide for Small Business says legal and professional fees are deductible on Schedule C when they are ordinary and necessary expenses directly related to operating the business. If one invoice includes both business work and personal work, the personal portion is generally not deductible as a business expense.
Example
Suppose a self-employed consultant pays one professional for two different jobs: advice on business cash-flow systems and personal retirement/investment planning. The fact that the same advisor provided both services does not make the entire bill a Schedule C expense. The business-related portion needs to stand on its own as an ordinary and necessary business cost, with records that support the allocation.
Trusts and Estates: Ordinary Investment Advice Is Not Automatically Deductible
This is an area where the old version of this article was too broad. A trust or estate does not get to deduct ordinary investment-advisory fees merely because the trust or estate paid them.
The 2025 IRS instructions for Form 1041 say fees for investment advice that would commonly or customarily be provided to an individual investor are not deductible by an estate or non-grantor trust. Certain incremental costs can be deductible when the extra charge exists because the advice is being provided to a trust or estate rather than to an individual.
The IRS also addresses bundled fees. When one fiduciary, attorney, accountant, or other fee combines deductible trust-administration work with costs that an individual would commonly incur, allocation may be required. In plain English: “the trust paid it” is not the test.
Michael’s Take
Trust and estate fees are where I would be least willing to guess from the invoice title. Ask the fiduciary, CPA, or attorney what services are inside the fee and how the deductible portion was determined. The tax treatment follows the service—not the stationery.
Tax Rules Get Easier When You Classify the Transaction First
This advisor-fee question is a good example: the same-looking payment can change tax treatment depending on whether it was personal advice, business work, trust-specific administration, or something else entirely.
Get Financial Clarity by email for more plain-English breakdowns of the tax and planning distinctions that actually change the answer.
IRA Fees: A Personal Deduction and an Account-Level Charge Are Different Questions
Be careful not to turn two separate questions into one.
- Question 1: Can you claim an IRA-related fee as a personal itemized deduction? Under current law, ordinary investment fees and separately billed IRA trustee administrative fees paid personally are not deductible as miscellaneous itemized deductions.
- Question 2: Can a particular fee be charged to or paid from the retirement account itself? That depends on what the fee is for, the account arrangement, and the custodian’s rules. An account-level fee payment is not the same thing as taking a personal tax deduction.
IRS Publication 529 specifically lists investment fees and separately billed IRA trustee administrative fees among miscellaneous deductions that individuals cannot currently deduct. If an advisor wants to charge a broader planning fee to an IRA, I would confirm the fee allocation and account treatment with the custodian and tax professional rather than assuming every planning service belongs inside the IRA.
Investment Interest Can Still Be Deductible, but It Is a Different Rule
Investment interest is one of the most useful distinctions on this page because it often gets lumped together with “investment expenses.” It should not be.
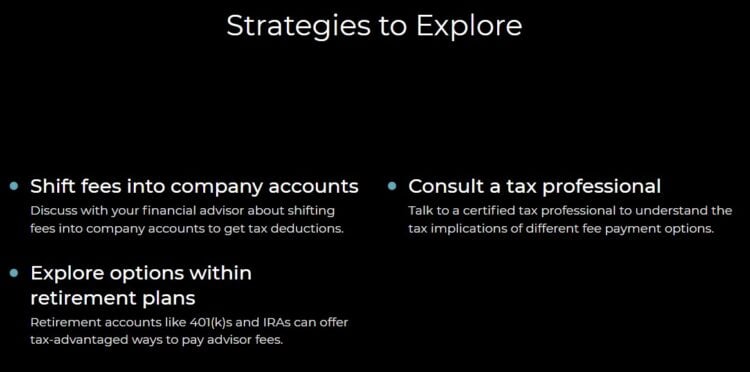
If you borrow money to buy or carry property held for investment, the interest may qualify for an investment-interest deduction. IRS Form 4952 is used to calculate the current deduction and any amount carried forward, and the deduction is generally limited to net investment income.
That limitation matters. Qualified dividends and net capital gain do not automatically count the same way as ordinary investment income for this calculation; elections and special rules can change the result. So I would not use a shortcut like “margin interest × your tax bracket” without first working through Form 4952.
Simple Example
If you have $8,000 of otherwise qualifying investment interest but only $5,000 of net investment income under the Form 4952 rules, the current-year deduction is generally limited by that $5,000 of net investment income. Form 4952 also tracks disallowed investment interest that may carry forward. This is a different deduction from an advisory fee.
What Changed From the Old 2% AGI Rule?
The Short Timeline
- Before 2018: Certain investment and advisory expenses could be miscellaneous itemized deductions, but only the total above the 2% AGI floor was deductible.
- 2018-2025: The Tax Cuts and Jobs Act suspended those miscellaneous itemized deductions.
- July 4, 2025: Public Law 119-21 removed the scheduled January 1, 2026 end date from Section 67(g).
- 2026: The old personal deduction has not returned under current federal law.
That history is worth knowing because older articles, forum posts, tax books, and even saved planning notes may still say “the deduction comes back in 2026.” That was the law before the 2025 legislation changed it.
What to Do With Your Advisor Fee Statement at Tax Time
Instead of asking only, “Can I deduct this advisor fee?” walk through the invoice this way:
- Identify who incurred the expense. Was it you personally, your sole-proprietor business, a trust, or an estate?
- Identify the actual service. Portfolio management, personal planning, business tax work, trust administration, investment interest, and account administration are not interchangeable tax categories.
- Split mixed invoices. If one professional did both personal and business work—or a trust fee combines investment advice and fiduciary administration—ask for documentation that supports the allocation.
- Match the expense to the correct return and rule. A valid Schedule C expense, Form 1041 deduction, or Form 4952 investment-interest deduction does not revive the old Schedule A advisor-fee deduction.
- Keep the statement and supporting records. The more an exception depends on what work was actually performed, the more useful a detailed invoice becomes.
And if your real question is whether you are paying too much for advice rather than whether the fee is deductible, that is a different decision. The deduction does not determine whether an advisor is worth the cost.
The Bottom Line on Deducting Financial Advisor Fees
For most individual investors, the 2026 answer is straightforward: personal financial advisor and investment-management fees are not deductible on the federal individual income tax return.
The useful part is knowing when to stop treating every professional fee as the same thing. Business services, trust-specific costs, IRA-related charges, and investment interest each have their own rules. Classify the service first. Then decide which tax rule applies.
Do not focus on the fee you cannot deduct. Focus on whether you are getting enough planning, tax awareness, and investment value to justify the fee you are actually paying.
Sources
- Public Law 119-21, Section 70110 — termination of the old Section 67(g) sunset
- IRS Publication 334 — business expenses and legal/professional fees
- IRS Instructions for Form 1041 — investment-advisory, incremental, and bundled trust/estate fees
- IRS Publication 529 — investment fees and IRA trustee administrative fees
- IRS Form 4952 — investment interest expense deduction
- IRS Publication 550 — investment income and investment-interest reporting
Tax note: This article covers general U.S. federal tax rules as of August 31, 2026. State tax treatment and individual facts can differ. For a mixed business/personal fee, trust or estate allocation, IRA charge, or investment-interest deduction, use the current tax forms and instructions and consider confirming the treatment with a qualified tax professional.
