When you inherit a house with siblings, you generally have three practical choices: sell the property and divide the proceeds, arrange for one sibling to buy out the others, or keep the property together.
None is automatically best.
Start by checking who has authority over the house, what debt remains, and whether everyone can afford the plan they prefer.
On This Page
- Before You Decide, Who Actually Owns the House?
- Sell, Buy Out, or Keep the House: What Does Each Option Pay?
- How to Buy Out a Sibling From an Inherited House
- What If One Sibling Wants to Sell and Another Refuses?
- Keeping the House Together: Who Pays the Bills?
- What Taxes Apply When Siblings Sell or Buy Out an Inherited House?
- Before Anyone Signs, Get Six Things in Writing
- So Should You Sell, Buy Out, or Keep the House?
Before You Decide, Who Actually Owns the House?
Being named in a will does not necessarily give you immediate authority to sell a house. The property might still be in probate, held by a trust, or subject to an executor’s authority. Even after it passes to heirs, the form of title matters.
- Title: Who is named on the recorded deed?
- Authority: Does an executor, administrator, trustee, or group of owners control the transaction?
- Shares: What percentage does each heir actually own?
- Debt: What mortgage, liens, taxes, and other obligations remain?
- Occupancy: Does anyone have separate legal rights to live there?
If the owner died without a will, start with my guide to transferring property after death without a will, which addresses Texas-specific inheritance questions. This article focuses on the financial decision once the relevant rights and authority are established.
Sell, Buy Out, or Keep the House: What Does Each Option Pay?
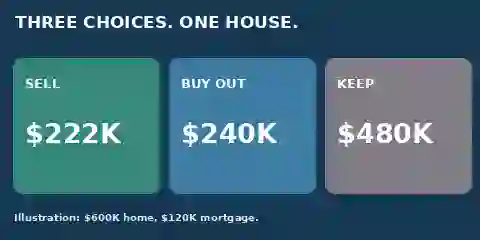
Imagine two siblings with equal interests in a house worth $600,000. It has a $120,000 mortgage. An open-market sale would incur an assumed $36,000 in selling expenses. These are hypothetical numbers, and we are leaving out other liens, estate expenses, tax and reimbursement adjustments to isolate the decision.
| Item | Amount |
|---|---|
| Current house value | $600,000 |
| Mortgage payoff | $120,000 |
| Equity before adjustments | $480,000 |
| Assumed selling expenses | $36,000 |
Here’s the distinction I want families to understand: Home value, equity, sale proceeds and taxable gain are four different numbers. Mixing them up can create a fairness argument when the siblings are actually using different definitions.
Why are the sale and buyout numbers $18,000 apart? The $222,000 sale payout and $240,000 starting equity share differ by $18,000 per heir because the sale assumes $36,000 in third-party selling expenses. A $231,000 midpoint is one possible negotiating illustration, not a legal valuation rule or an automatically fair price. Real appraisal, title, loan and legal costs, timing, future sale exposure and any lawful credits change the economics. Neither side automatically owns half of a commission that was never paid.
Free resource
Take this resource with you
Enter your email once and I will send the resource straight to you.
Choose the resource only or the resource plus Financial Clarity. The resource is delivered either way.
How to Buy Out a Sibling From an Inherited House
Agree on a defensible valuation
Choose an independent appraisal or another written valuation method everyone accepts. An online estimate is a conversation starter, not necessarily the right settlement value. Decide what happens if two appraisals differ before ordering them.
Calculate equity and separate disputed adjustments
Subtract secured debt from the agreed value. Then separately review documented taxes, insurance, repairs, improvements and any other claims. Paying expenses does not automatically change someone’s deeded ownership percentage. Whether payments justify reimbursement or an offset depends on documents, facts and state law.
Test the financing before promising a payout
In our example, a sibling with no cash who wants to retain the house might need financing to deal with the existing $120,000 mortgage and a proposed $240,000 payout. That could mean roughly $360,000 in financing before transaction costs, depending on how the loan is handled. Income, credit, debt, property condition and lender rules matter. A fair offer that cannot be funded is not a completed deal.
Don’t confuse an inherited mortgage with new buyout financing
Federal due-on-sale exceptions protect certain transfers related to death. The Consumer Financial Protection Bureau explains inherited-mortgage successor rules. These protections have conditions. They do not require a lender to advance new money for a sibling buyout, release every borrower from liability or approve a refinance.
Set a closing deadline and a fallback
Put the valuation, payout method, financing deadline, closing terms and temporary expense responsibilities in writing. If the financing falls through, the agreement should say what happens next. Waiting indefinitely rarely makes the bills smaller.
What if three siblings inherit the house, or shares aren’t equal? Do not divide by two. Establish the legal interests first. Three equal interests in the $480,000 illustrative equity start at $160,000 each before adjustments; the $444,000 outside-sale proceeds start at $148,000 each before taxes. In some estates, other estate assets might support an authorized distribution that balances inheritances without creating permanent co-ownership. That depends on the will, trust, estate obligations and state law, not an automatic right of the executor.
What If One Sibling Wants to Sell and Another Refuses?
One heir may need cash for retirement or debts. Another may want to live in the family home. Neither person’s preference automatically erases the other’s legal rights. First identify whether the house is still controlled by an estate or trust or is already owned directly by the heirs.
Can one sibling force the sale?
Sometimes a co-owner can ask a court for partition, potentially resulting in division or sale. But there is no nationwide promise of an immediate sale at a particular price. State law, title, estate status, occupancy protections and the property’s characteristics matter. Some states have special heirs-property safeguards. For example, Texas Property Code Chapter 23A provides procedures for qualifying heirs-property cases. Consult a lawyer in the state where the property is located before threatening a lawsuit.
What if one sibling lives there rent-free?
The resident sibling may have paid the taxes and repairs. The other may feel excluded from a jointly owned asset. Gather payment records and any occupancy agreements. Neither automatic back rent nor automatic reimbursement is safe to assume. A local lawyer can explain the relevant accounting and offsets.
When someone agrees to buy out the others but never closes, use the written deadline and fallback. An informal promise is not a financing plan.
Keeping the House Together: Who Pays the Bills?
Here’s a question worth asking: if this house had not been inherited, would these siblings voluntarily buy it together today? If not, don’t assume inheritance makes them compatible property partners.
| Expense | Annual amount |
|---|---|
| Property taxes | $7,000 |
| Insurance | $4,000 |
| Maintenance and reserves | $6,000 |
| Utilities and miscellaneous | $3,000 |
| Total before mortgage | $20,000 |
If two equal owners agree to split these hypothetical costs, that’s $10,000 each per year before mortgage payments, extraordinary repairs and other expenses. Can both reliably pay? Who approves a roof replacement? Who makes decisions if one sibling stops contributing?
Renting it out is a business decision
Gross rent is not profit. Budget for vacancy, repairs, taxes, insurance, management, debt service and reserves. Decide who manages tenants, approves spending, distributes cash and can trigger a sale. A co-ownership agreement should define the exit path before a disagreement arises.
What Taxes Apply When Siblings Sell or Buy Out an Inherited House?
Under the general federal rule in IRS Publication 551, inherited property generally receives a basis related to fair market value at death, subject to important exceptions and valuation rules. A later sale uses adjusted basis, selling expenses and other applicable facts. The cash received is not automatically the taxable gain. A buyout may have different consequences from an estate distribution.
For the detailed reporting rules, see my inherited-property capital gains and Form 1099-S guide. For separate planning strategies, see how to reduce capital gains tax on inherited property. Those pages own the tax calculations; this one owns the decision about the shared house.
Before Anyone Signs, Get Six Things in Writing
- Confirm who has legal authority to act and what each person owns.
- Agree on an appraisal method and valuation date.
- Document debt, expenses and any disputed adjustments separately.
- Require a financeable buyout offer and a closing deadline.
- Assign taxes, insurance, mortgage and occupancy costs while deciding.
- Agree on mediation, voluntary sale or another lawful next step if talks fail.
This is a discussion checklist, not a binding property agreement. A local estate or real-estate attorney should prepare or review the legal documents.
So Should You Sell, Buy Out, or Keep the House?
Sell when the heirs need liquidity, can’t fund a buyout or don’t want a continuing property partnership. Buy out when one heir genuinely wants the house, can finance a fair agreement and can afford the ongoing bills. Keep together only when everyone agrees on use, costs, decision rights and an exit plan.
No universal rule can settle a family disagreement. Start with the deed, an agreed valuation and the actual debt. Give the family a deadline. You don’t all have to want the same outcome, but you do need a workable way to reach one.
