

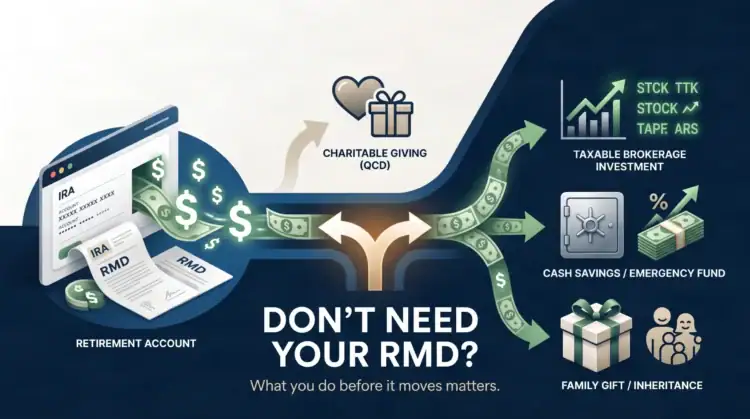
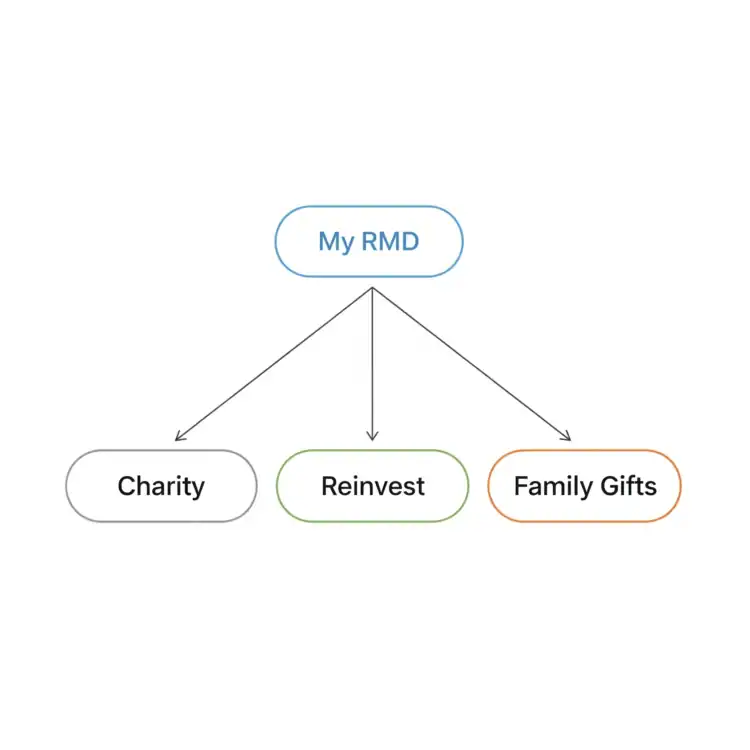
If you have to take an RMD but do not need the money for living expenses, you have several good options: give eligible IRA dollars directly to charity through a QCD, stay invested by moving securities in kind to a taxable account, reinvest cash in a taxable brokerage account, add the money to cash reserves, or gift the after-tax proceeds.
But there is one question I would answer before choosing any of them: Has the RMD already been distributed? That line matters. Some of your best tax moves have to happen before the money lands in your checking or brokerage account. Once it does, you still have plenty of choices—but you cannot rewind the transaction and make it a QCD or roll the RMD back into a retirement account.
Quick Answer
- Giving to charity? Check whether a qualified charitable distribution (QCD) should happen directly from your IRA before you take the RMD in cash.
- Want to stay invested? Consider an in-kind distribution to a taxable brokerage account or reinvest the cash after the distribution.
- Want to help family? Use after-tax proceeds for gifts or a 529 contribution, subject to the normal gift-tax and 529 rules.
- Thinking Roth IRA? An RMD cannot be rolled into a Roth IRA. A separate Roth IRA contribution may be possible only if you have enough taxable compensation and otherwise qualify.
Key Takeaways Ahead
Before You Decide: Has the RMD Already Been Distributed?
After nearly 30 years as a financial planner, I saw this question come up when retirees had pensions, Social Security, or other assets already covering their spending: the RMD was mandatory, but the cash was not actually needed. The mistake was treating “I have to withdraw it” as if it also meant “I have to stop planning with it.”
This is the distinction I wish more RMD articles led with. The IRS tells you how much must leave the retirement account. It does not tell you that the money has to sit in cash afterward.
Before the distribution, you may still have choices about how the RMD leaves the account. That can include a QCD from an eligible IRA or an in-kind distribution of securities. After the distribution, the RMD is out. You can spend, save, invest, or gift the proceeds, but the tax character of the RMD does not disappear just because you move the money somewhere else.
Michael’s Decision Rule
Do not start with, “Where should I reinvest this?” Start with, “Is there anything I should do before this becomes a normal retirement-account distribution?” That one question separates QCD planning from everything you can still do after the money is already yours.
What to Do With an RMD You Don’t Need: 6 Options
Your best choice depends on the job you want the money to do. The table below is the shortest way I know to sort the options.
| Your goal | Option to consider | Important timing or tax point |
|---|---|---|
| Give to charity | Qualified charitable distribution (QCD) | Must be made directly from an eligible IRA to an eligible charity; do this before taking that amount as cash. |
| Stay invested | In-kind distribution to a taxable brokerage account | The fair market value counts toward the RMD; the taxable portion follows the normal tax rules for that retirement-account distribution. |
| Reinvest for long-term growth | Cash RMD, then taxable brokerage investment | For a traditional IRA, the taxable portion follows the normal distribution rules; future dividends, interest and gains then follow taxable-account rules. |
| Increase liquidity | Savings, money market or cash reserve | Useful when the money may be needed soon; do not take investment risk solely because you feel compelled to “put it back to work.” |
| Help family | Gift cash or fund a 529 | You must first complete the RMD under the retirement-account tax rules; separate gift-tax and 529 rules then apply to what you give. |
| Add money to a Roth IRA | Separate Roth IRA contribution if eligible | The RMD itself cannot be rolled over. You need taxable compensation and must satisfy the contribution rules. |
1. Use a QCD if Charity Is Already Part of Your Plan
If you are at least age 70½ and already plan to give to charity, a qualified charitable distribution may deserve the first look. Under IRS Publication 590-B, a QCD is generally a distribution made directly by the IRA trustee to an eligible charitable organization. It can count toward your RMD while the qualifying amount is excluded from income.
For 2026, the indexed QCD exclusion limit is $111,000 per eligible IRA owner. That is a ceiling, not a target. The practical value of a QCD is that the charitable dollars can satisfy part or all of an IRA RMD without first increasing adjusted gross income.
Timing Trap
If you take the RMD in cash first and then write a personal check to charity, that later gift does not retroactively turn the earlier distribution into a QCD. If QCD treatment matters, coordinate the direct IRA-to-charity transfer before you distribute those dollars to yourself.
That distinction can matter beyond federal income tax because RMD income can affect other calculations tied to income. If Medicare premiums are part of your concern, see the deeper comparison of QCDs versus ordinary charitable donations for IRMAA.
2. Reinvest the RMD in a Taxable Brokerage Account
Yes, you can reinvest an RMD. You just cannot roll the RMD back into the IRA, 401(k), or another retirement plan as an eligible rollover distribution. The IRS rollover rules specifically exclude required minimum distributions from rollover treatment.
Once the RMD is properly distributed, though, the proceeds are yours. If you do not need the cash, you can move the after-tax amount into a taxable brokerage account and invest it according to your overall allocation and time horizon.
The tax wrapper changes. Inside the traditional IRA, growth was generally tax-deferred. In the taxable account, interest, dividends and realized gains can create current or future tax consequences. That does not make reinvesting a bad idea. It means the investment choice should fit its new account.
You May Be Able to Take the RMD In Kind
If your real goal is simply to stay invested, you may not need to sell a holding just to buy it again outside the IRA. Fidelity’s current guidance explains that an in-kind RMD can transfer securities from a tax-deferred account to a taxable brokerage account without selling them first. The fair market value at distribution counts toward the RMD; the taxable portion follows the normal rules for that retirement-account distribution, and the fair market value generally becomes the new basis in the taxable account.
Michael’s Take
I would not sell a perfectly good investment merely because the RMD rule says assets must leave the IRA. The rule requires a distribution, not necessarily a trip to cash. If the holding still belongs in your portfolio, an in-kind transfer is worth asking the custodian about.
3. Can You Put an RMD Into a Roth IRA?
Not as a rollover or Roth conversion. The RMD must come out first because it is not rollover-eligible. This is where the reinvestment question gets subtle: receiving an RMD and qualifying for a separate Roth IRA contribution in the same year are two different transactions governed by different rules.
There is a different route, but the distinction matters. If you have enough taxable compensation for the year and otherwise qualify, you may make a normal IRA or Roth IRA contribution under the regular contribution rules. For 2026, the combined traditional-and-Roth IRA contribution limit is $7,500, or $8,600 if you are age 50 or older, subject to the compensation limit and Roth income phaseouts. The IRS 2026 IRA contribution rules control that contribution—not the fact that you received an RMD.
In plain English: money is fungible, but the rules are not. You can receive an RMD and separately qualify to contribute to a Roth IRA in the same year. You cannot label the RMD itself a Roth rollover and make the required distribution disappear.
4. Add It to Cash Reserves—or Spend It
Reinvesting is not automatically the sophisticated choice. If the RMD arrives when your cash reserve is thin, a home repair is coming, you expect large medical or travel expenses, or you simply want more spending room, keeping some or all of the proceeds liquid can be perfectly rational.
This is where “I don’t need the RMD” deserves a second question: Don’t need it for what? You may not need it for this month’s bills, but it might reduce the amount you otherwise have to sell from a taxable portfolio next year.
For a traditional IRA, an RMD is generally included in taxable income except to the extent the distribution represents previously taxed basis. Spending the money instead of reinvesting it does not change that tax treatment. If you want a deeper explanation of how the income is characterized—and why an RMD is not earned income—see how RMD withdrawals are taxed.
5. Gift the After-Tax Proceeds or Fund a 529
If your own plan is well funded, an RMD can become part of your giving plan. After the distribution, you can give cash to children, grandchildren or other people, or contribute to a 529 plan for education.
Do not confuse the federal annual gift-tax exclusion with a maximum gift. For 2026, the IRS annual exclusion is $19,000 per recipient per donor. Gifts above the exclusion can create Form 709 reporting and may use part of the donor’s lifetime exclusion; they do not automatically mean gift tax is due.
If you are funding a Roth IRA for a working child or grandchild, the same rule from the prior section applies: the recipient needs sufficient taxable compensation and must meet the normal IRA contribution requirements. Your gift can provide the cash; it does not create contribution eligibility.
6. Use Part of the RMD to Cover Taxes
An RMD can solve a tax-payment problem too. IRS Publication 590-B explains that federal income tax is generally withheld from traditional IRA distributions unless you choose otherwise. Many retirees use withholding from retirement distributions rather than sending every estimated-tax payment separately.
The right withholding amount depends on your whole tax picture, not just the RMD. Pension income, Social Security, capital gains, Roth conversions, state taxes and other income can all change the answer. The useful point here is simpler: before automatically reinvesting 100% of the distribution, make sure you have reserved enough cash for the tax bill.
A Simple Example
Suppose your RMD is $30,000 and you do not need it for monthly spending. That does not mean your choice is “reinvest $30,000 or waste it.” You might use part for withholding, move the remaining cash to a taxable account, or—if charity was already in the plan—satisfy some of the RMD with a QCD before the rest is distributed. One RMD can serve more than one job.
What About QLACs, Roth Conversions and Reducing Future RMDs?
Those are important strategies, but they answer a different question. A qualified longevity annuity contract (QLAC), Roth conversions, and planned withdrawals before RMD age can change future required distributions. They are not ways to undo a current-year RMD after it is already due or distributed.
I would keep those two planning jobs separate. First, satisfy and use this year’s RMD correctly. Then, if the recurring RMD is larger than you want, model whether future tax-bracket management, charitable planning, or other retirement-income changes actually improve the long-term result. Do not make a large Roth conversion simply because the phrase “tax bomb” sounds scary.
Which RMD Option Fits Your Goal?
- You already give to charity: check QCD eligibility before taking the RMD in cash.
- You want to stay invested: compare an in-kind distribution with a cash distribution followed by taxable reinvestment.
- You want more liquidity: keep enough in cash for near-term spending and taxes.
- You want to help family: gift after-tax proceeds or consider a 529 contribution under the normal gift and education-account rules.
- You want money in a Roth IRA: test separate contribution eligibility; do not try to roll the RMD itself into the Roth.
- You want smaller RMDs in future years: treat that as a separate forward-looking tax-planning decision.
Before the Money Moves
- Confirm the RMD amount and which account must satisfy it.
- Decide whether any eligible IRA amount should go directly to charity as a QCD.
- If you want to remain invested, ask whether an in-kind distribution is available.
- Decide how much cash to reserve for taxes and near-term spending.
- Only then decide where the remaining after-tax proceeds should go.
And do not let strategy distract from compliance. If you are unsure whether the RMD itself has been fully satisfied by the deadline, handle that first. The separate guide to the RMD deadline and missed-RMD penalty rules owns that problem.
Bottom Line: The Best RMD Move Depends on Timing and Purpose
An RMD you do not need is not automatically a tax problem, and it is not automatically an investment problem. It is a decision-sequencing problem.
Before the distribution, ask whether a QCD or in-kind transfer better fits your goal. After the distribution, decide whether the proceeds belong in a taxable portfolio, cash reserve, gift, 529 plan or your spending plan. If a Roth IRA is part of the idea, remember that the RMD cannot be rolled over; any Roth contribution has to qualify on its own.
That is the piece I would not leave until December: first decide what has to happen before the RMD leaves the retirement account. Then decide what you want the money to do for the rest of your life.
Sources
- Internal Revenue Service — Publication 590-B, Distributions from IRAs
- Internal Revenue Service — Rollovers of retirement plan and IRA distributions
- Internal Revenue Service — 2026 IRA contribution limits
- Internal Revenue Service — Gift tax FAQs and annual exclusion
- Fidelity Investments — RMD requirements and in-kind distributions
