Is VGLI worth it? It can be an excellent deal for a veteran who cannot qualify for reasonably priced private insurance. For a healthy veteran needing coverage for a fixed 10-, 20-, or 30-year period, a level-premium private term policy may cost less. The mistake is deciding from a rate chart alone. A cheaper quote is not replacement protection until the insurer accepts you and the new policy is in force.
Here is the practical test: What amount of coverage does your family need, for how long, what can you actually qualify for, and what will the premiums become? The right answer may be VGLI, private term, some of each, or less coverage as your obligations shrink.
A rule worth protecting
Never cancel an in-force VGLI policy because an agent gave you an attractive quote. Confirm the replacement insurer has approved the application, the issued policy matches the promised terms, and coverage has started before requesting cancellation. If private underwriting goes badly, your existing VGLI may be the protection you cannot cheaply replace.
On This Page
- VGLI vs. private life insurance: the decision in one minute
- How much does VGLI cost in 2026?
- The 2026 VGLI premium holiday changes the cancellation decision
- The 240-day VGLI rule: a deadline you cannot treat casually
- When keeping VGLI is the better decision
- When private term insurance may be a better fit
- Can you convert VGLI to permanent coverage without a medical exam?
- What actual veterans are asking—and what the answers miss
- A safer five-step VGLI replacement checklist
- What changes at 50, 60 and retirement?
- Frequently asked VGLI questions
- The bottom line: buy the protection you need, not just the cheapest premium
- Sources and rate verification
VGLI vs. private life insurance: the decision in one minute
| Your situation | Usually worth investigating | The hidden question |
|---|---|---|
| Recently separated; health uncertain | Enroll in VGLI while eligible | Will the 240-day no-health-review window close before private coverage is issued? |
| Healthy; need coverage for 20 years | Compare private level-term quotes | What happens after the term ends? |
| Medical conditions or tobacco use | Price VGLI alongside actually approved quotes | Is the private offer standard, rated, excluded or declined? |
| Near retirement, debts lower | Recalculate necessary death benefit | Do you need $500,000—or a smaller bridge? |
| Need lifelong coverage | Consider VGLI and participating permanent conversions | How do the future premium and permanent-policy costs compare? |
VGLI is group term life insurance offered after service. Unlike a 20-year level-premium policy, its premiums rise by five-year age band. Unlike most medically underwritten private coverage, timely VGLI enrollment has a no-health-review window. VA explains the differences at its insurance comparison page.
How much does VGLI cost in 2026?
What aging does to a $500,000 VGLI premium
Age 50–54
$145/month
$1,740 in a normal 12-month year
Age 60–64
$425/month
$5,100 in a normal 12-month year
Age 70–74
$1,075/month
$12,900 in a normal 12-month year
Illustration uses the VA age-band schedule for $500,000 of coverage; it does not subtract the special November 2026–January 2027 premium holiday. The comparison is not a quote for private insurance.
These are the official monthly rates effective July 1, 2025 for $500,000 of VGLI coverage. Multiply by 12 for an ordinary full premium-paying year. The special 2026–27 premium holiday changes the amount some existing policyholders actually pay during those three months; it does not change the published age-band rate schedule.
| Age | Monthly for $500,000 | 12-month annual cost |
|---|---|---|
| 29 or younger | $30 | $360 |
| 30–34 | $40 | $480 |
| 35–39 | $50 | $600 |
| 40–44 | $70 | $840 |
| 45–49 | $95 | $1,140 |
| 50–54 | $145 | $1,740 |
| 55–59 | $250 | $3,000 |
| 60–64 | $425 | $5,100 |
| 65–69 | $690 | $8,280 |
| 70–74 | $1,075 | $12,900 |
| 75–79 | $1,925 | $23,100 |
| 80+ | $2,200 | $26,400 |
Source: VA official VGLI rate chart. For example, age 50–54 is $145 monthly or $1,740 for 12 months. Age 60–64 is $425 monthly or $5,100 for 12 months. Neither $6,600 at age 50 nor $13,200 at age 60 is correct under this schedule. The rate can also differ from a person’s actual annual bill when payment-frequency discounts or the premium holiday apply.
There is an important comparison trap in those numbers. A 35-year-old buying a 20-year private term policy locks in a premium for that contract period, while VGLI crosses several age bands. Comparing one month at age 35 with one month at age 55 does not describe 20-year cost. Equally, comparing a private quote given to a person in excellent health with VGLI offered to a veteran with difficult-to-insure health is not a fair comparison.
Financial Clarity Newsletter
The coverage mistake is often a timing mistake. Get straightforward retirement, insurance and money-decision guidance from a retired financial planner.
Get one practical money decision at a time, without an insurance sales pitch.
The 2026 VGLI premium holiday changes the cancellation decision
Time-sensitive VA benefit: November 2026–January 2027
Veterans with VGLI coverage active November 1, 2026 generally receive a premium holiday covering November, December and January while keeping coverage. Coverage canceled or lapsed by October 31 is not eligible. Before making a change, check the VA premium holiday FAQs for rules affecting your effective date, past-due premiums and payment method.
For someone with $500,000 of VGLI at age 50–54, three waived monthly premiums would ordinarily equal $435. At age 60–64, three months at the listed rate would equal $1,275. Those are examples using an unchanged monthly rate; coverage effective partway through the window may receive fewer waived months. The VA says the required first premium for a newly effective policy is not waived.
- VA/Prudential AutoPay or eligible automatic deductions: VA says payments will pause and then resume automatically.
- Your bank’s bill-pay instructions: VA says you should contact the bank to stop recurring payments effective November 1, 2026 and restart effective February 1, 2027.
- Annual or other advance payments: VA says affected premium amounts are credited on a following billing statement.
- Past-due balances: the holiday does not forgive amounts already owed.
- Cancellation requested during the holiday: VA says reductions and cancellation requests take effect after the holiday ends January 31, 2027.
None of that makes it wise to keep unneeded insurance forever. It means the exact timing of an otherwise sensible switch matters unusually much this fall.
The 240-day VGLI rule: a deadline you cannot treat casually
VA says SGLI generally continues for 120 days after separation. Eligible veterans may apply for VGLI within 240 days of separation without proof of good health. Application is available for 1 year and 120 days after separation, but applying after day 240 requires evidence of good health. Those are two different deadlines, and confusing them can cost you the central benefit of VGLI.
A reader who plans to shop for private insurance should not wait until day 239 to discover that underwriting will take longer. Decide whether to take VGLI as a temporary bridge and compare alternatives while your guaranteed-access period remains open. Start with the VA VGLI application instructions.
When keeping VGLI is the better decision
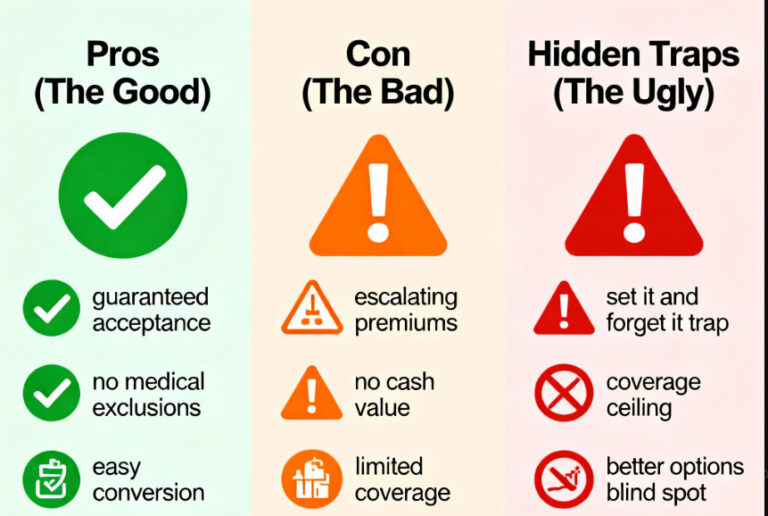
One of the strongest reasons to keep VGLI is not the price; it is insurability. Private companies evaluate health, tobacco use and other characteristics. A service-connected disability rating does not automatically predict the private insurer’s decision. What matters is the particular condition, its treatment, the insurer’s guidelines and the quote actually issued. A private company can offer a higher premium, less coverage, altered terms, or no policy.
A veteran who has an established medical condition, cannot meet normal underwriting requirements, or has an unpredictable future need for insurance should be especially careful before surrendering renewable VGLI. VA explains that VGLI may continue throughout life if premiums are paid, whereas fixed-term private coverage ends at the contractual term unless renewed or converted under its conditions.
Another option is to keep a smaller VGLI amount instead of thinking in all-or-nothing terms. A spouse may need $150,000 for remaining expenses rather than the $500,000 needed decades earlier when children were small and a mortgage was large. The coverage decision should begin with the beneficiary’s actual shortfall.
A visual decision path: protect coverage before chasing price
1. KEEP
Stay covered while you check eligibility, VA deadlines and any premium-holiday benefit.
2. COMPARE
Get actual underwritten private offers for the same death benefit and coverage period.
3. SWITCH ONLY IF APPROVED
Cancel VGLI only after replacement coverage is issued and in force—and only if switching improves your situation.
When private term insurance may be a better fit
A healthy veteran who needs predictable protection for a fixed window—until a mortgage is repaid or a child becomes financially independent—should compare individual life insurance options. A level-premium private term policy can eliminate future age-band premium increases during its guaranteed term. But it will not automatically continue at the same rate after that term.
Get a real quote for the same death benefit, an appropriate duration, and the applicant’s actual health history. Check any rating, exclusion, renewal premium, conversion right and final issued documents. A “starting at” advertisement or sample price for a healthy 30-year-old is not your policy.
Can you convert VGLI to permanent coverage without a medical exam?
Yes. VA permits VGLI policyholders to convert to individual permanent life insurance with participating insurers without proving good health. This is not the same as buying inexpensive level-premium term insurance. Permanent coverage usually has a materially different premium structure and may be expensive, especially at older ages. Before converting, request an illustration that shows guaranteed obligations and policy values, compare multiple eligible companies, and confirm exactly what existing coverage would be replaced. VA VGLI eligibility and conversion details are the authoritative starting point.
What actual veterans are asking—and what the answers miss
In a 2025 r/LifeInsurance VGLI discussion, a retired service member asked whether $400,000 of coverage was worth keeping as premiums rose. Some replies emphasized buying private term; another warned to secure a replacement before giving up coverage that may not be available again. That caution is the part worth carrying into a decision, while a forum reply is not evidence of what any particular insurer will offer.
A 2026 r/VeteransBenefits conversation raised a different problem: a veteran with service-connected health conditions found private quotes extremely expensive and was unsure where to turn. The lesson is not that every disabled veteran should buy the same plan. It is that the comparison must include who can actually obtain enough coverage.
Other threads show a false choice between term and whole life. The useful question is whether the family needs protection for a defined period, for life, or simply until accumulated assets can support survivors. Permanent insurance can be a legitimate tool, but an expensive policy does not become suitable merely because it lasts longer.
A safer five-step VGLI replacement checklist
- Measure the remaining need. Add dependent support, final expenses, debts and income replacement; subtract resources that can genuinely support survivors.
- Compare matching benefits. Request at least two individually underwritten proposals with the same benefit and the term your family actually needs.
- Check the issued policy. Confirm rate class, premium guarantee, exclusions, conversion options, beneficiaries and the coverage effective date in writing.
- Protect continuity. Keep VGLI active until replacement coverage is unquestionably in force. Consider retaining a smaller amount if justified.
- Make the cancellation deliberate. Check holiday timing, confirm VA/OSGLI procedures, document the effective cancellation date, and update your survivor records. For the beneficiary and document side of this decision, see what happens to your money and who can act.
The most expensive insurance mistake is not always a high premium
Sometimes it is canceling a policy you cannot get back. A good comparison weighs the actual price against the cost of being wrong.
Financial Clarity Newsletter
If your insurance needs are changing as retirement approaches, get the next clear question to ask and the action to take.
Get one practical money decision at a time, without an insurance sales pitch.
What changes at 50, 60 and retirement?
At 50, a veteran paying $145 a month for $500,000 should look ahead rather than judge only today’s bill. On reaching age 55, the listed monthly rate becomes $250; at 60, it becomes $425. Those differences matter if coverage still serves a genuine family need, but they are not proof that switching is possible or advisable for a particular veteran.
In my years working with families on financial planning, one recurring problem was keeping an old decision on autopilot after the household changed. The number of people depending on earnings can fall, assets may grow, and debts may disappear. That should trigger a fresh insurance-needs calculation—not a reflexive surrender of valuable coverage. This is a general planning judgment, not a claim about a specific veteran client.
Ask the harder question: if you died next month, exactly which bills or goals could your surviving family not fund? If the answer is “none,” the right move may be reducing coverage, not replacing one expensive policy with another.
Frequently asked VGLI questions
Is VGLI better than private life insurance?
Not universally. VGLI may be much more valuable to someone whose health makes private coverage costly or unavailable. Healthy veterans with a fixed-duration coverage need should obtain actual private level-term quotes before deciding.
Does VGLI have a medical exam?
Eligible applicants enrolling within 240 days of leaving the military generally do not need to prove good health. After that period, until the 1-year-and-120-day deadline, VA requires health evidence.
Does VGLI expire at age 60?
No. Existing VGLI coverage can continue as long as required premiums are paid. Age 60 is relevant to the additional $25,000 coverage increase feature, not an automatic expiration date.
Does the premium holiday apply to VALife?
No. VA says the November 2026–January 2027 premium holiday applies to eligible VGLI coverage, not VALife, SGLI, FSGLI, TSGLI or S-DVI.
Should I cancel VGLI after I get a private quote?
No. A quote is not an issued, active replacement policy. Verify the new insurance is in force on the expected terms first.
The bottom line: buy the protection you need, not just the cheapest premium
VGLI is neither a rip-off nor a universal bargain. It buys an unusually important option for some veterans: continued term coverage that does not depend on future medical underwriting after timely enrollment. Private term may offer a far more predictable price for veterans who can qualify and have a defined period of need. Recalculate the amount your family needs, obtain actual quotes, and sequence any switch safely.
Sources and rate verification
- VA, VGLI premium schedule effective July 1, 2025
- VA, 2026–27 VGLI premium holiday FAQs
- VA, VGLI enrollment and 240-day rule
- VA, compare VGLI to private life insurance
Official VA premium schedule and premium-holiday eligibility checked October 21, 2026. Verify your own account status and insurer terms before making a change.
