


If you searched for Grid Code G because it appeared in a credit-monitoring alert or an old credit-report display, the short answer is simple: G means collection. It is a reporting code that describes an account being in collection status. It is not a secret penalty, it does not by itself prove that a debt was sold, and there is no separate “Grid Code G removal” process.
That distinction matters. You do not fix the letter G. You figure out whether the underlying collection account is yours, whether the information is accurate, and what your best next move is.
Grid Code G is best understood as a collection-status code in credit-reporting data. If the collection information is wrong, dispute the account. If it is accurate, paying or settling it may resolve the debt, but accurate negative information generally cannot be forced off your credit report simply because you paid it.
I would much rather have you spend ten minutes identifying the actual collection than ten hours trying to decode a letter. The code is the label. The account is the problem to solve.
Key Takeaways Ahead
What Grid Code G Actually Means
Grid Code G is not a score, a separate debt category, or a special punishment created by one credit bureau. In the credit-reporting data conventions historically associated with Metro 2 reporting, the letter G denotes collection in payment-history information.
You may see the phrase in a monitoring alert, a legacy report format, or a third-party credit product rather than on the modern consumer-facing report itself. Older forum examples show alerts labeled “Grid Code G (Collections),” which is why people still search the phrase years later.
Treat Grid Code G like the word collection printed in a tiny technical font. The useful questions are not “How do I erase the G?” They are: Whose debt is this? Is the balance right? Are the dates right? Who is reporting it? And what happens if I dispute, pay, or settle it?
What Grid Code G Does Not Tell You
The old version of this article made the code sound more specific than it is. A collection entry does not automatically tell you that the original creditor sold the debt to a debt buyer. A collection agency may own the debt, or it may simply be collecting for another company.
It also does not tell you whether the debt is legally enforceable, whether the amount is correct, whether the account is too old to report, or whether paying it will improve your score by a predictable number of points.
Those are separate questions governed by the facts of the account, credit-reporting rules, debt-collection law, your state law, and the scoring model a lender eventually uses.
A legitimate unpaid collection, an account that belongs to someone else, a duplicate collection, an incorrect balance, an obsolete reporting date, or a debt that is valid but too old for a collector to sue on can all require different responses. The letter G alone does not choose the response for you.
The 4-Step Plan for a Grid Code G Collection
If Grid Code G is what brought you here, use it as a trigger to inspect the collection carefully. Here is the order I would use.
Step 1: Pull the Actual Credit Reports and Identify the Collection
Start with the account, not the alert. Get your credit reports from the official source, AnnualCreditReport.com, and compare how the collection appears at Equifax, Experian, and TransUnion.
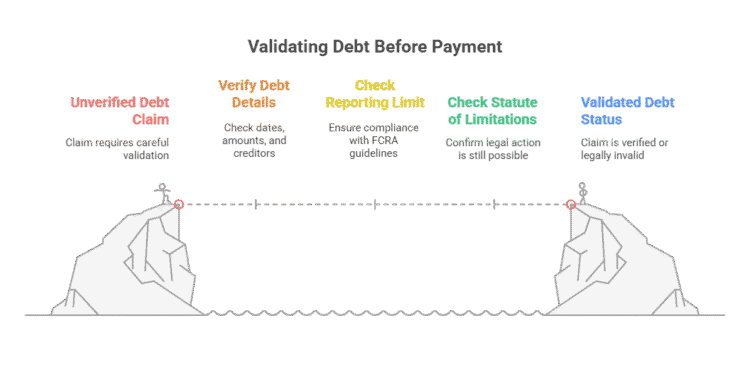
Write down the collection company, original creditor if shown, balance, account number, date opened, and date of first delinquency or other date information. Also note whether the same debt appears more than once.
This is where many mistakes become obvious. A name you do not recognize is not automatically fraud; a debt collector or debt buyer may appear under a company name you have never dealt with. But an unfamiliar account is absolutely a reason to verify before paying.
Step 2: Decide Whether You Are Disputing the Debt or Just Asking for Information
If a debt collector has contacted you, federal rules generally require the collector to provide validation information about the debt. The Consumer Financial Protection Bureau explains that the notice includes information about the debt and an end date for a 30-day dispute period.
If you send a written dispute or a qualifying request for original-creditor information within that period, the collector generally must pause collection of the disputed amount until it provides verification in response.
The 30-day rule is commonly misstated online. It is generally your window to preserve specific debt-validation rights after receiving the notice. It is not a universal rule that says the collector must answer you within 30 days or automatically delete the account.
Keep copies of everything you send and receive. The CFPB recommends keeping good records of communications with a collector. Written records matter far more than an argument over the phone.
Step 3: Dispute Inaccurate Credit Reporting with Both the Bureau and the Furnisher
If the collection account on your credit report is inaccurate, incomplete, duplicated, not yours, or cannot be verified, dispute the reporting itself. The CFPB recommends disputing inaccurate information with both the credit reporting company and the company that furnished the information.
A credit reporting company generally has 30 days to investigate a dispute, although some circumstances allow up to 45 days. If the furnisher determines that the information is wrong or cannot be verified, it must update or remove the information and notify the credit reporting companies it supplied.
Be specific. “Please remove this” is weaker than “This account is not mine,” “the balance is wrong,” “the same debt appears twice,” or “the date of first delinquency is inaccurate,” followed by documentation supporting the point.
Step 4: If the Collection Is Accurate, Choose a Resolution Strategy Instead of a Deletion Fantasy
If the debt is yours and the reporting is accurate, the decision changes. You may decide to pay in full, negotiate a settlement, ask whether the collector has a deletion policy, or get legal advice if the debt is old, disputed, large, or connected to a lawsuit.
The important point is that paying a valid collection and removing accurate credit-report information are not the same thing. The CFPB says accurate negative information generally cannot be forced off your report simply because it is negative.
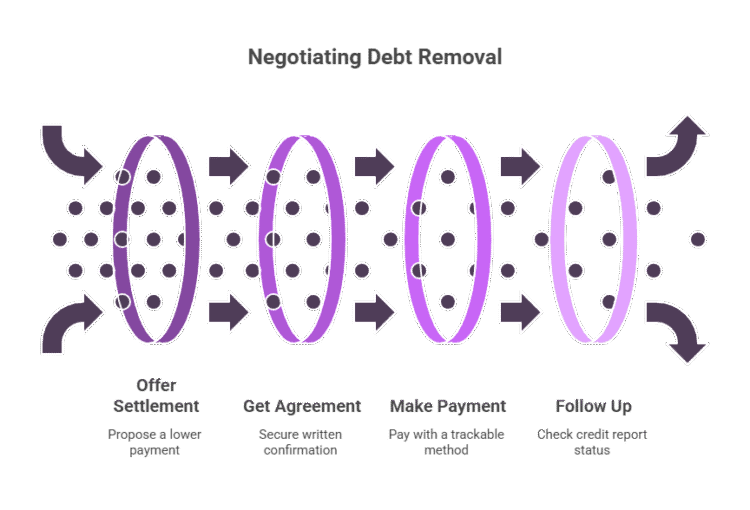
Some collection companies voluntarily delete certain paid or settled collection accounts under their own policies. Others do not. A so-called “pay for delete” request is therefore a negotiation, not a federal right and not something I would describe as guaranteed.
And be careful with very old debt. The statute of limitations for a lawsuit is a separate issue from how long information may appear on a credit report, and state law matters. Under the CFPB’s current Regulation F, a debt collector may not sue or threaten to sue to collect a time-barred debt. That does not automatically mean the debt disappears or that every form of collection activity is prohibited.
Can an Accurate Grid Code G Collection Be Removed?
Sometimes—but not because you discovered the code.
If the underlying collection reporting is inaccurate or cannot be verified after a proper dispute, the inaccurate information should be corrected or removed. Identity-theft information and duplicate reporting also have their own remedies.
If the collection is accurate, federal law generally allows most negative credit information to remain for roughly seven years. For collection and charge-off accounts, the reporting period is tied to the delinquency that led to the collection; simply selling or transferring the debt does not create a fresh seven-year clock.
Wrong information? Dispute it.
Right information but unresolved debt? Decide how to resolve the debt.
Right information and already resolved? Confirm the balance/status is updated, then understand that accurate history may remain until its reporting period expires.
This is why I would not pay a credit-repair company simply because it promises to “remove Grid Code G.” The CFPB specifically warns consumers to be skeptical of anyone claiming they can remove current, accurate negative information from a credit report.
Bottom Line: Fix the Collection, Not the Code
Grid Code G sounds like the sort of thing that requires a decoder ring. It does not.
It means collection. From there, your job is to identify the account, verify whether the debt and reporting are accurate, use your validation and dispute rights when appropriate, and then choose the right resolution if the debt is legitimate.
The most important correction to remember is this: there is no magic four-step process that guarantees an accurate collection disappears. There is, however, a very good four-step process for finding errors, protecting your rights, and making a better decision with the information in front of you.
If this collection is part of a larger debt problem, the next decision is usually not “Which code do I fight next?” It is how to prioritize cash flow, high-interest debt, emergency savings, and credit repair in the right order.
Sources and Further Reading
- Consumer Financial Protection Bureau: debt validation information and the 30-day dispute period
- Consumer Financial Protection Bureau: how to dispute an error on your credit report
- Consumer Financial Protection Bureau: removing accurate negative information
- Consumer Financial Protection Bureau Regulation F: time-barred debt
- Federal Trade Commission: date of delinquency and credit reporting
