

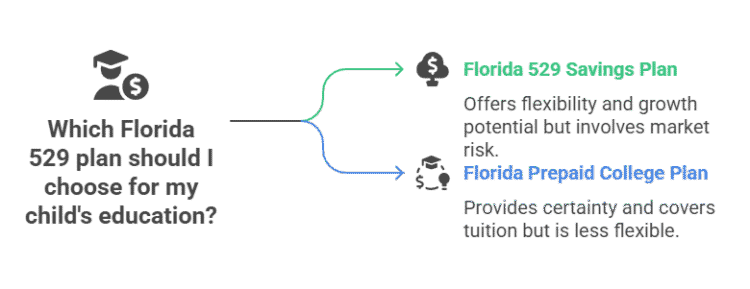
Florida has two state-sponsored 529 options: the Investment 529 Plan and Florida Prepaid 529 Plans. They sit under the same 529 umbrella, but they do different jobs. The Investment 529 is an investment account for a broad range of qualified education expenses. Florida Prepaid lets eligible families buy defined tuition or dormitory benefits in advance.
If you are trying to understand the Florida 529 landscape, this page is the overview. I’ll show you what each option does, the current tax rules, what 529 money can pay for, how Florida’s Investment 529 works, and one Florida-specific point that is easy to miss: living in Florida does not mean you have to use Florida’s Investment 529 Plan.
If your real question is which one should I choose?, that belongs on my Florida Prepaid vs. 529 decision guide. If you want the detailed mechanics of Florida Prepaid itself, use my Florida Prepaid College Plan guide.
Quick Answer
Florida’s Investment 529 is the flexible investing account. Florida Prepaid is the defined-benefit tuition and dormitory contract. You can use either one, both, or, for the investment side, even compare another state’s 529 savings plan. Florida has no personal state income tax, so there is no Florida income-tax deduction you lose by shopping around.
Show the quick version
- Two Florida 529 paths: Florida offers the Investment 529 Plan and Florida Prepaid 529 Plans. They solve different college-savings jobs.
- Investment 529: Flexible education investing with market risk. Florida residency is not required.
- Florida Prepaid: Defined tuition or dormitory coverage for eligible families, guaranteed by the State of Florida under the program rules.
- No Florida tax deduction: Florida has no personal state income tax, so the main 529 tax advantages for Florida families are federal.
- You can shop other states: Florida residents can generally use another state’s 529 savings plan, so compare the actual investments, costs and features.
- 2026 rules changed: Federal law now allows up to $20,000 per beneficiary per year for qualifying K-12 expenses, plus other qualified education uses.
On This Page
- Florida 529 Options at a Glance
- How the Florida Investment 529 Plan Works
- Florida 529 Investment Options, Fees and Contribution Rules
- Where Florida Prepaid Fits
- Florida 529 Tax Benefits
- What Can a 529 Pay For in 2026?
- Can Florida Residents Use Another State’s 529?
- Florida Prepaid or 529? Find Your Best Starting Structure
- What Happens to Unused 529 Money?
- Florida 529 FAQ
- Where to Go Next
- The Bottom Line
- How We Verified This
Florida 529 Options at a Glance
| Feature | Florida Investment 529 | Florida Prepaid 529 |
|---|---|---|
| Main job | Invest and save for a broad range of qualified education expenses | Buy defined future tuition or dormitory benefits |
| Investment risk | Yes. Account value can rise or fall | No market risk on the contracted benefit |
| Florida residency | Not required | Residency rules apply to new purchases |
| Contribution style | You decide how much and when to contribute | Price and payment depend on the plan purchased |
| Where it can be used | Eligible schools nationwide and other qualified uses | Designed around Florida public benefits, with plan value usable at eligible schools elsewhere |
| Best next question | How should I invest and what expenses do I want the money to cover? | How much tuition or housing certainty do I want? |
That is the ecosystem view. It is enough to understand the jobs. It is not meant to replace the deeper comparison page.
How the Florida Investment 529 Plan Works
The Florida Investment 529 Plan is Florida’s state-sponsored education savings account. You contribute money, choose from the plan’s available investment strategies, and use qualified withdrawals for eligible education expenses.
Florida residency is not required. Florida Prepaid’s current rules say the Investment 529 is available nationwide. The account is not guaranteed, and it is possible to lose money depending on the investments you choose.
There is no set use-it-by date for the Investment 529. If one beneficiary no longer needs the money, federal and plan rules may allow you to change the beneficiary to another eligible family member.
Michael’s Take
The Florida Investment 529 is the flexible tool. That is useful, but flexibility is not the same thing as safety. You still own the investment decision. As college gets closer, I would pay more attention to how much market risk is sitting inside money you expect to spend soon.
Florida 529 Investment Options, Fees and Contribution Rules
Florida currently offers three broad ways to invest inside the Investment 529:
- Enrollment Year Portfolio: a professionally managed option that automatically becomes more conservative as the student approaches college age.
- Static portfolios: diversified portfolios with allocations that stay generally constant rather than automatically changing with the beneficiary’s age.
- Individual fund options: a build-your-own approach for people who want more control over the mix.
Florida’s current investment-options page says more than 80% of new families choose the Enrollment Year Portfolio. That makes sense to me as a reminder that most families do not need to turn a college account into a hobby. If you do want more control, the plan also offers static portfolios and individual funds across cash, fixed-income, equity and specialty categories.
The Board currently charges a 0.00% administration fee on the Investment 529. That does not mean the investments are free. The underlying investment choices still have fund expenses, and those vary by option. Florida’s current program disclosure lists no minimum contribution and a $500,000 maximum aggregate account balance per beneficiary.
You can change how new contributions are invested at any time. Existing money can currently be reallocated among investment options up to twice per calendar year. Florida Prepaid publishes the current Investment 529 management rules here.
What I Would Actually Compare
Do not pick a 529 because one brochure says “low fee.” Compare the investment option you would really use, its underlying cost, how the risk changes over time, account usability, automatic contribution features and whether you are comfortable leaving the money invested through bad markets.
Where Florida Prepaid Fits
Florida Prepaid is also a 529 plan, but it works differently enough that it deserves its own guide.
Instead of investing toward an unknown future tuition bill, you purchase defined tuition or dormitory coverage under a contract. New Prepaid 529 Plans are now available year-round and are sold in one-year increments. Florida Prepaid describes the contracted benefits as guaranteed by the State of Florida.
This page intentionally stops there. For current coverage, eligibility, pricing, dormitory rules, refunds, scholarship treatment, out-of-state use and the 10-year benefit period, see my Florida Prepaid College Plan guide.
If you are deciding between Prepaid and an Investment 529, or wondering whether using both makes sense, use the Florida Prepaid vs. 529 comparison.
Florida 529 Tax Benefits
Florida has no personal state income tax, so there is no Florida state-income-tax deduction for contributing to a 529. The main tax benefits for Florida families are federal.
- Tax-deferred growth: investment earnings are not taxed each year while they remain inside the account.
- Tax-free qualified withdrawals: earnings are generally federal-income-tax-free when distributions are used for qualified education expenses and the federal requirements are met.
- Beneficiary flexibility: beneficiary changes can generally be made within the eligible-family rules without treating the change like an ordinary taxable withdrawal.
One coordination rule matters a lot. The same education expense generally cannot be used twice to create two federal tax benefits. If you are also claiming an education credit or using scholarship money, coordinate the expenses instead of assuming every school bill can support every tax break at once.
What Can a 529 Pay For in 2026?
For higher education, qualified 529 expenses can include tuition, required fees, books, supplies, computers and certain room-and-board costs when the federal enrollment requirements are met. Federal law also allows certain registered apprenticeship expenses, limited student-loan repayment and qualified postsecondary credential expenses.
For distributions made after December 31, 2025, federal law also allows up to $20,000 per beneficiary per year from qualified tuition programs for qualifying elementary and secondary education expenses. The permitted K-12 categories are broader than tuition alone. They can include curriculum and instructional materials, certain tutoring, testing, dual enrollment and qualifying educational therapies. IRS Topic 313 has the current federal 529 rules.
Keep the Receipts
“It was for school” is not the tax rule. Match the withdrawal to a qualified expense and keep documentation, especially for housing, K-12 costs, student loans, apprenticeships and less common education expenses.
Can Florida Residents Use Another State’s 529?
Yes, generally. This is one of the most useful Florida-specific points in the whole article.
Investor.gov says you can generally invest in almost any state’s 529 education savings plan regardless of where you live. Some states make their home-state plan especially attractive by offering residents a state income-tax deduction, credit or another benefit.
Florida does not impose a personal state income tax. So Florida residents do not have a Florida 529 income-tax deduction to preserve before comparing another state’s savings plan.
That does not mean another state’s plan is automatically better. It means Florida families can compare plans on the merits. Look at the actual investment options, underlying expenses, age-based choices, account usability, automatic contribution tools and other features that matter to you.
The Florida Advantage Here Is Freedom to Compare
In a state with a valuable home-state 529 tax deduction, shopping elsewhere can carry a tax cost. Florida does not create that particular hurdle. I would still start with Florida’s plan, but I would not stop comparing just because it has Florida in the name.
Florida Prepaid or 529? Find Your Best Starting Structure
Five questions. No fake “winner.” See whether your answers point more toward Florida Prepaid, an Investment 529, or using both.
Your starting structure to investigate
Why this showed up
Tradeoff to examine
Want to stress-test the result?
These do not restart the quiz. They show what could change the decision.
Florida Prepaid 529 Plans are guaranteed by the State of Florida under the plan's governing law and contract. The Florida Investment 529 Plan is not guaranteed and can lose value.
Plan eligibility, coverage, fees, refund provisions, investment options, qualified-expense rules, scholarship coordination, and tax rules can change. Verify current official documents before enrolling or changing a plan.
What Happens to Unused 529 Money?
Unused Investment 529 money is not automatically trapped.
Depending on the situation, you may be able to leave the money invested, change the beneficiary to another eligible family member, use it for another qualified education purpose, or take a nonqualified withdrawal and deal with the applicable tax consequences.
Federal law also allows qualifying 529-to-Roth IRA rollovers for the same beneficiary. The lifetime rollover limit is currently $35,000. Annual Roth IRA contribution limits apply, the 529 generally must have been open for at least 15 years, the transfer must meet the trustee-to-trustee rules, and recent contributions and earnings are restricted.
If that is the route you are considering, use my 529-to-Roth IRA rollover guide. The $35,000 headline is not the whole rule.
Florida 529 FAQ
Are 529 plans worth it in Florida?
They can be. Florida families still receive the federal 529 tax advantages even though Florida does not offer a personal state-income-tax deduction. Whether a 529 is useful depends on your time horizon, investment choices, expected education costs and how much flexibility you want.
Which 529 plan is best for Florida residents?
There is no single best plan for every Florida family. Start with Florida’s Investment 529, then compare the actual investment option you would use, its costs, risk structure, account features and usability with other state plans that are open to you.
Does Florida give a tax deduction for 529 contributions?
No Florida personal-income-tax deduction applies because Florida does not impose a personal state income tax. The main tax advantages are federal.
Can a Florida resident open another state’s 529?
Generally, yes. Investor.gov says investors can typically choose almost any state’s 529 education savings plan regardless of residence. Always check the specific plan’s eligibility and feature rules before opening an account.
Can I have both Florida Prepaid and an Investment 529?
Yes. They can do different jobs. Florida Prepaid can cover a defined tuition or dormitory benefit while an Investment 529 can cover other qualified education expenses. Whether that combination fits your family belongs in the Florida Prepaid vs. 529 decision guide.
Can the Florida Investment 529 be used outside Florida?
Yes. Florida says the Investment 529 can be used at eligible institutions nationwide, subject to the federal qualified-expense rules.
What if my child gets Bright Futures?
A scholarship does not automatically make a 529 useless. Investment 529 money can still pay other qualified education expenses, and federal rules provide special treatment for certain scholarship-related withdrawals. Florida Prepaid also has separate scholarship-use and refund rules under its contract.
The Bottom Line
Florida gives families two state-sponsored 529 tools, but the bigger lesson is not that you have to pick one Florida product and stop thinking.
Use the Investment 529 when you want flexible education investing. Use Florida Prepaid when you want defined tuition or dormitory coverage and meet the eligibility rules. And if you are using an Investment 529, remember that Florida’s lack of a personal state income tax gives you room to compare other states’ plans without protecting a Florida 529 tax deduction that does not exist.
Start with the job you need the money to do. Then compare the actual plan features that matter to that job.
How We Verified This
I checked the current Florida plan rules and federal 529 guidance before updating this page.
