


Most car insurance myths are harmless trivia. A red car does not cost more to insure. Fine. Good to know.
The myths I care about are the ones that can leave you paying a claim yourself: thinking “full coverage” means everything is covered, assuming anyone who borrows your car is automatically protected, or treating your state’s legal minimum as a recommendation.
Here is a typical version of the mistake: a young engineer is proud of the “full coverage” he bought. Then he actually reads the declarations page and realizes that phrase told him almost nothing about the gaps that matter to him. That is the problem with insurance shorthand: it sounds reassuring right up until you need the policy to write a check.
The 30-Second Answer
The expensive car insurance myths are usually about coverage, not price. “Full coverage” is not an official policy type. State minimum liability is a legal floor, not a personal recommendation. Insurance generally follows the car, but permissive-use rules, household drivers, exclusions, state law, and the exact policy can change the result. And telematics can raise a rate as well as lower it.
Before changing a policy because of something you heard online, check four lines on your declarations page: liability limits, comprehensive, collision, and uninsured/underinsured motorist coverage. Then check the deductibles and listed drivers.
Key Takeaways Ahead
The Car Insurance Myths That Can Actually Cost You Money
Google is full of myth lists. The useful question is not simply whether a statement is true or false. It is what changes on your policy if you believe it.
If you need a refresher on how liability, collision, comprehensive, UM/UIM, and other coverages fit together, my car insurance coverage guide owns that beginner job. Here, we are going after the misconceptions that cause bad decisions.
Myth #1: “Full Coverage” Means Everything Is Covered
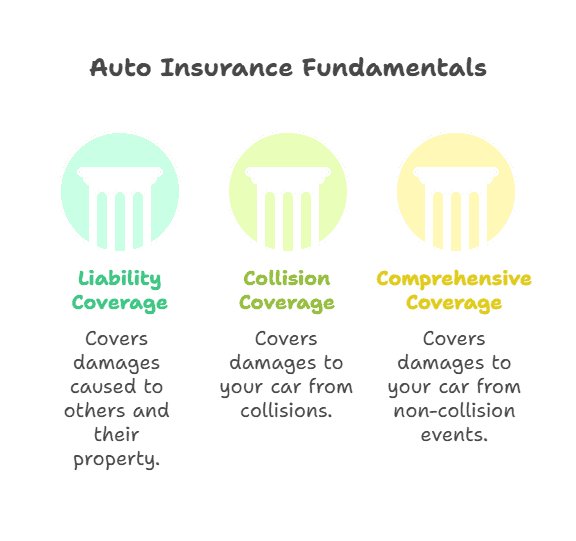
Reality: “Full coverage” is not an official insurance product. It is informal shorthand that usually means liability plus comprehensive and collision, along with whatever coverage your state requires.
That still does not mean every loss is covered. Rental reimbursement, roadside assistance, gap coverage, higher liability limits, uninsured/underinsured motorist protection, and other coverages may be separate. Policy exclusions and deductibles still apply.
Progressive’s current explanation of full coverage makes the same point: no policy protects you in every situation, and your declarations page is where you verify the coverages you actually bought.
The Expensive Mistake
Do not ask an agent, “Do I have full coverage?” Ask, “What are my liability limits, deductibles, collision and comprehensive coverages, UM/UIM limits, and the exclusions I should know about?” The second question can actually be answered from the policy.
Stop Letting Insurance Shorthand Make the Decision
Once you see why “full coverage” can hide the details that matter, the next step is learning which policy terms deserve a second look before renewal or a claim.
- Coverage gaps that sound harmless until a loss happens
- Deductible and liability-limit tradeoffs worth reviewing
- Car-insurance rules that change by state, policy, or driver
Get practical insurance checks like these in your inbox each week.
Myth #2: Once the Car Is Paid Off, You Should Drop Collision and Comprehensive
Reality: Paying off the loan changes what the lender can require. It does not tell you whether you can afford to lose the car.
Once there is no lender, collision and comprehensive are generally optional. The decision should compare the car’s current value, your deductible, the annual cost of those coverages, and whether replacing the vehicle out of pocket would hurt your finances.
Run This Test
Your paid-off car is worth $9,000 and you have a $1,000 collision deductible. If losing the car tomorrow would force you into debt or derail your emergency fund, “the loan is paid off” is a weak reason to drop the coverage. If the car is worth very little, the premium and deductible can change that answer.
The National Association of Insurance Commissioners’ consumer auto guidance notes that collision and comprehensive are not required by law, though a lender or lessor may require them. That is a requirement rule, not a keep-or-drop rule.
Myth #3: Insurance Follows the Car, So Anyone Who Drives It Is Covered
Reality: “Insurance follows the car” is a useful starting sentence, not a coverage guarantee.
Auto insurance generally follows the insured vehicle. If you give a licensed friend permission to borrow your car occasionally, your policy may provide primary coverage under what insurers call permissive use. But regular drivers, household members, excluded drivers, unlicensed drivers, non-permissive use, business use, state law, and policy language can change the result.
Progressive’s current permissive-use guidance describes “insurance follows the car” as a general rule with exceptions and says regular drivers should be listed on the policy.
Before You Hand Over the Keys
If someone lives with you or drives your car regularly, do not rely on the phrase “insurance follows the car.” Ask the insurer whether that person must be listed and whether any exclusion or permissive-use limitation applies.
Myth #4: The State Minimum Is Enough Insurance
Reality: State minimum means legal. It does not mean adequate for your finances.
Liability limits are the most your insurer will pay for a covered loss, subject to the policy. If you cause injuries or property damage above those limits, the unpaid amount can become your problem.
The NAIC’s consumer auto guidance explains that an auto policy is a legal contract with stated coverage limits, exclusions, and optional protections. The right liability limit depends on your state, assets, income, risk tolerance, other coverage, and what you can reasonably afford. That is why I would not turn “100/300” or any other rule of thumb into a universal recommendation.
The useful question is not whether you meet the legal minimum. It is whether your limits fit the loss you could realistically create or absorb.

Myth #5: Your Regular Credit Score Directly Sets Your Car Insurance Rate Everywhere
Reality: Where state law allows it, insurers may use a credit-based insurance score. That is not the same score a lender uses to decide whether to approve your mortgage or credit card.
The NAIC’s current credit-based insurance score guidance says these scores use information from credit history to estimate insurance loss risk. State laws limit or prohibit their use in different ways, so a sweeping rule like “only three states ban credit in insurance pricing” is no longer reliable.
If credit information affected an adverse insurance decision, check the notice from the insurer and your state insurance department rather than assuming your consumer credit score itself was plugged directly into the premium formula.
Insurance pricing can reflect many factors. Credit-based insurance scoring, where permitted, is only one part of the picture.
Two Popular Car Insurance Myths That Are Mostly Pricing Folklore
Myth #6: Red Cars Cost More to Insure
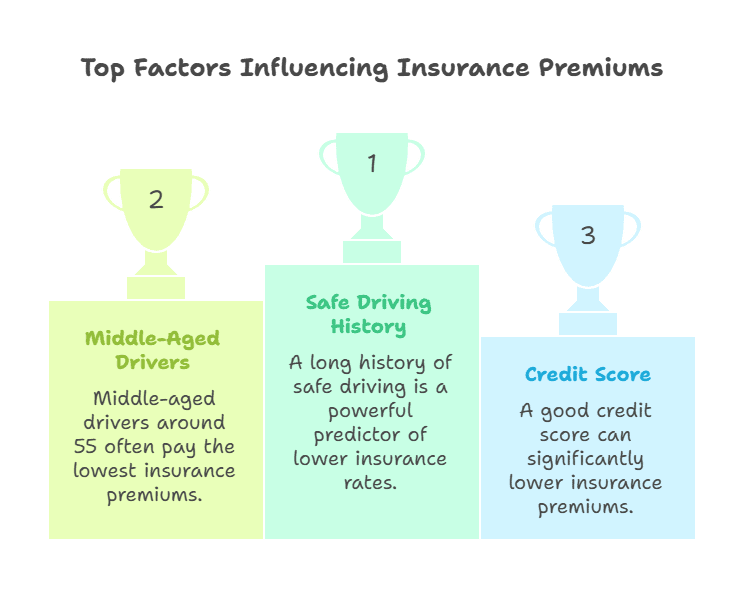
Reality: Paint color is not an auto insurance rating factor. Insurers care about the vehicle itself: make, model, repair cost, theft experience, safety record, and other rating variables allowed in your state.
The Insurance Information Institute’s auto insurance myth guide says vehicle color does not determine the price of auto insurance.
This is the classic insurance myth because it is memorable. It is also why I would not spend much time worrying about it. Nobody is financially exposed because the Mustang is red. The expensive myths are the ones that make you remove or misunderstand coverage.
Myth #7: Older Drivers Always Pay More
Reality: Age can affect auto insurance pricing where state law permits, but “older always costs more” is too simple. Rates reflect multiple factors, and some older drivers may qualify for discounts tied to driving courses, lower mileage, or other insurer and state rules.
The Insurance Information Institute notes that older drivers may qualify for discounts and that programs vary by state, insurer, and age. The practical move is to compare the renewal premium and available discounts, not assume your birthday alone determines the result.
The Newer Myths: EV Insurance and Telematics
Myth #8: Electric Vehicles Are Always Cheaper, or Always More Expensive, to Insure
Reality: Both “always” claims are wrong.
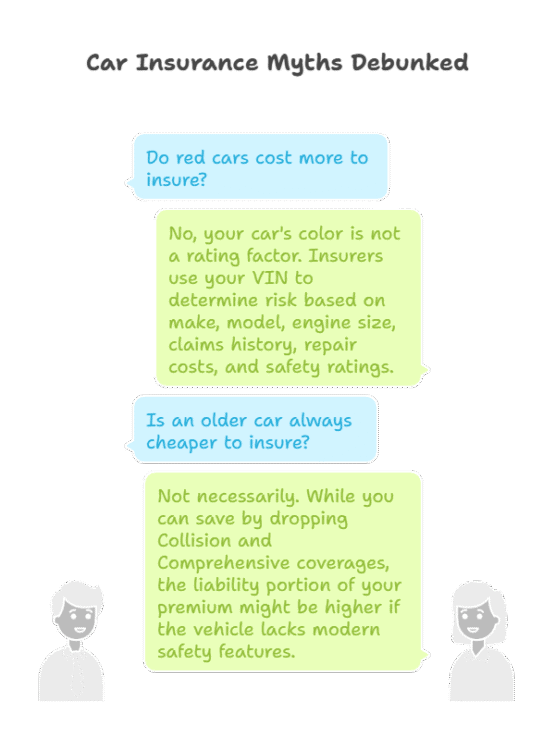
EVs have historically been more expensive to insure in many cases because some models cost more to repair or replace, and battery damage can be expensive. But rates vary by make and model, claims history, driver, location, coverage choices, and insurer.
Progressive’s October 2025 EV insurance review says some EV models may have insurance costs closer to comparable gas vehicles. So price the actual VIN you are considering instead of applying an “EV premium” rule to the whole category.
Myth #9: Telematics Can Only Lower Your Rate
Reality: A usage-based insurance program can reward safer or lower-risk driving, but some programs can also increase your rate based on the driving data they collect and the rules in your state.
For example, Progressive’s current Snapshot disclosure says the program considers behaviors such as hard braking, acceleration, late-night driving, mileage, and phone use. Progressive also says high-risk driving may increase the rate and that roughly 2 out of 10 participating drivers receive an increase.
That does not make telematics good or bad. It makes it a tradeoff. Before enrolling, ask what data is collected, whether participation can raise your rate, when the result is applied, and whether your state changes any of those rules.
The 5-Minute Car Insurance Myth Audit
Pull up your declarations page. You do not need to become an insurance adjuster. You just need to stop letting vague phrases make the decision.
Check These Before Your Next Renewal
- Liability limits: What is the most the policy pays for bodily injury and property damage?
- Collision and comprehensive: Do you carry them, what are the deductibles, and does keeping them still make sense for the vehicle?
- UM/UIM: What protection do you have if the other driver has no insurance or not enough insurance?
- Listed and excluded drivers: Is everyone who regularly drives the car handled correctly under the policy?
- Optional coverages: Rental reimbursement, roadside assistance, gap coverage, rideshare coverage, or anything else you are assuming is included.
- Telematics: If enrolled, can the program raise the rate and what driving data controls the result?
If the premium itself is the problem after you understand the coverage, that is a different job. My guide to lowering car insurance costs focuses on shopping, deductibles, discounts, and other premium-saving moves without confusing “cheaper” with “better covered.”
Frequently Asked Questions About Car Insurance Myths
What is the difference between collision and comprehensive coverage?
Collision coverage generally pays for covered damage to your car from a collision with another vehicle or object, subject to your deductible and policy terms. Comprehensive coverage generally applies to covered non-collision losses such as theft, vandalism, fire, weather, broken glass, or hitting an animal. Exact coverage and exclusions depend on the policy and state.
Does my insurance cover a rental car?
Your personal auto policy may extend some coverages to a rental car, but rental reimbursement for a temporary replacement vehicle after a covered loss is a separate coverage. Do not assume the phrase “full coverage” answers either question. Check your policy and the rental agreement before declining optional protection.
How can I lower my auto premium right now?
Start by comparing quotes using the same limits and deductibles, then review available discounts, your deductible choices, mileage or usage-based options, and whether optional coverages still fit your needs. Do not cut liability or physical-damage coverage blindly just to reach a lower premium.
Bottom Line: Read the Policy, Not the Myth
The red-car myth is trivia. The “full coverage” myth can write checks against your bank account.
That is the distinction I want you to remember. A useful car insurance question names the exact coverage, limit, deductible, driver, vehicle, or exclusion. If the answer is still just “full coverage,” “state minimum,” or “insurance follows the car,” you probably do not have enough information yet.
Before your next renewal, spend five minutes with the declarations page and verify what you are actually buying. You do not need the most insurance. You need to understand the insurance you chose and the financial risk you are keeping.
Sources
- National Association of Insurance Commissioners: Auto Insurance
- National Association of Insurance Commissioners: Consumer Auto Insurance
- National Association of Insurance Commissioners: Credit-Based Insurance Scores
- Insurance Information Institute: 8 Auto Insurance Myths
- Progressive: What Is Full Coverage Car Insurance?
- Progressive: Does Car Insurance Cover the Car or Driver?
- Progressive: Electric Vehicle Insurance Costs
- Progressive: Snapshot Usage-Based Insurance
